TWINO Update September 2026: FLEXI, up to 2% Cashback, Moneza Repaid – My Review
My latest TWINO update: why my portfolio is now 100% in FLEXI (6% fixed, daily interest, withdraw any time), what the regular ABS bring at up to 12%, how the extended cashback promotion with up to 2% works, that TWINO has fully repaid the Moneza claims from Russia – and how safe and regulated the platform really is. With all the numbers from my own account.
Table of contents
Time for a TWINO update. A lot has happened at the Latvian P2P platform over the past months: my portfolio is now 100% in FLEXI, the cashback promotion has been extended, the old Moneza claims from Russia have been fully repaid, and the app has grown up considerably. In this post I take you transparently through all the news, through my own account, and through the question of how safe TWINO actually is.
As always, first the most important note: this is not investment advice and not a buy recommendation, just my personal opinion and experience. P2P investments are high-risk – only invest money whose total loss you could handle. The TWINO link is a partner link: if you use it, you support my work at no extra cost to you.
My TWINO portfolio: 100% in FLEXI
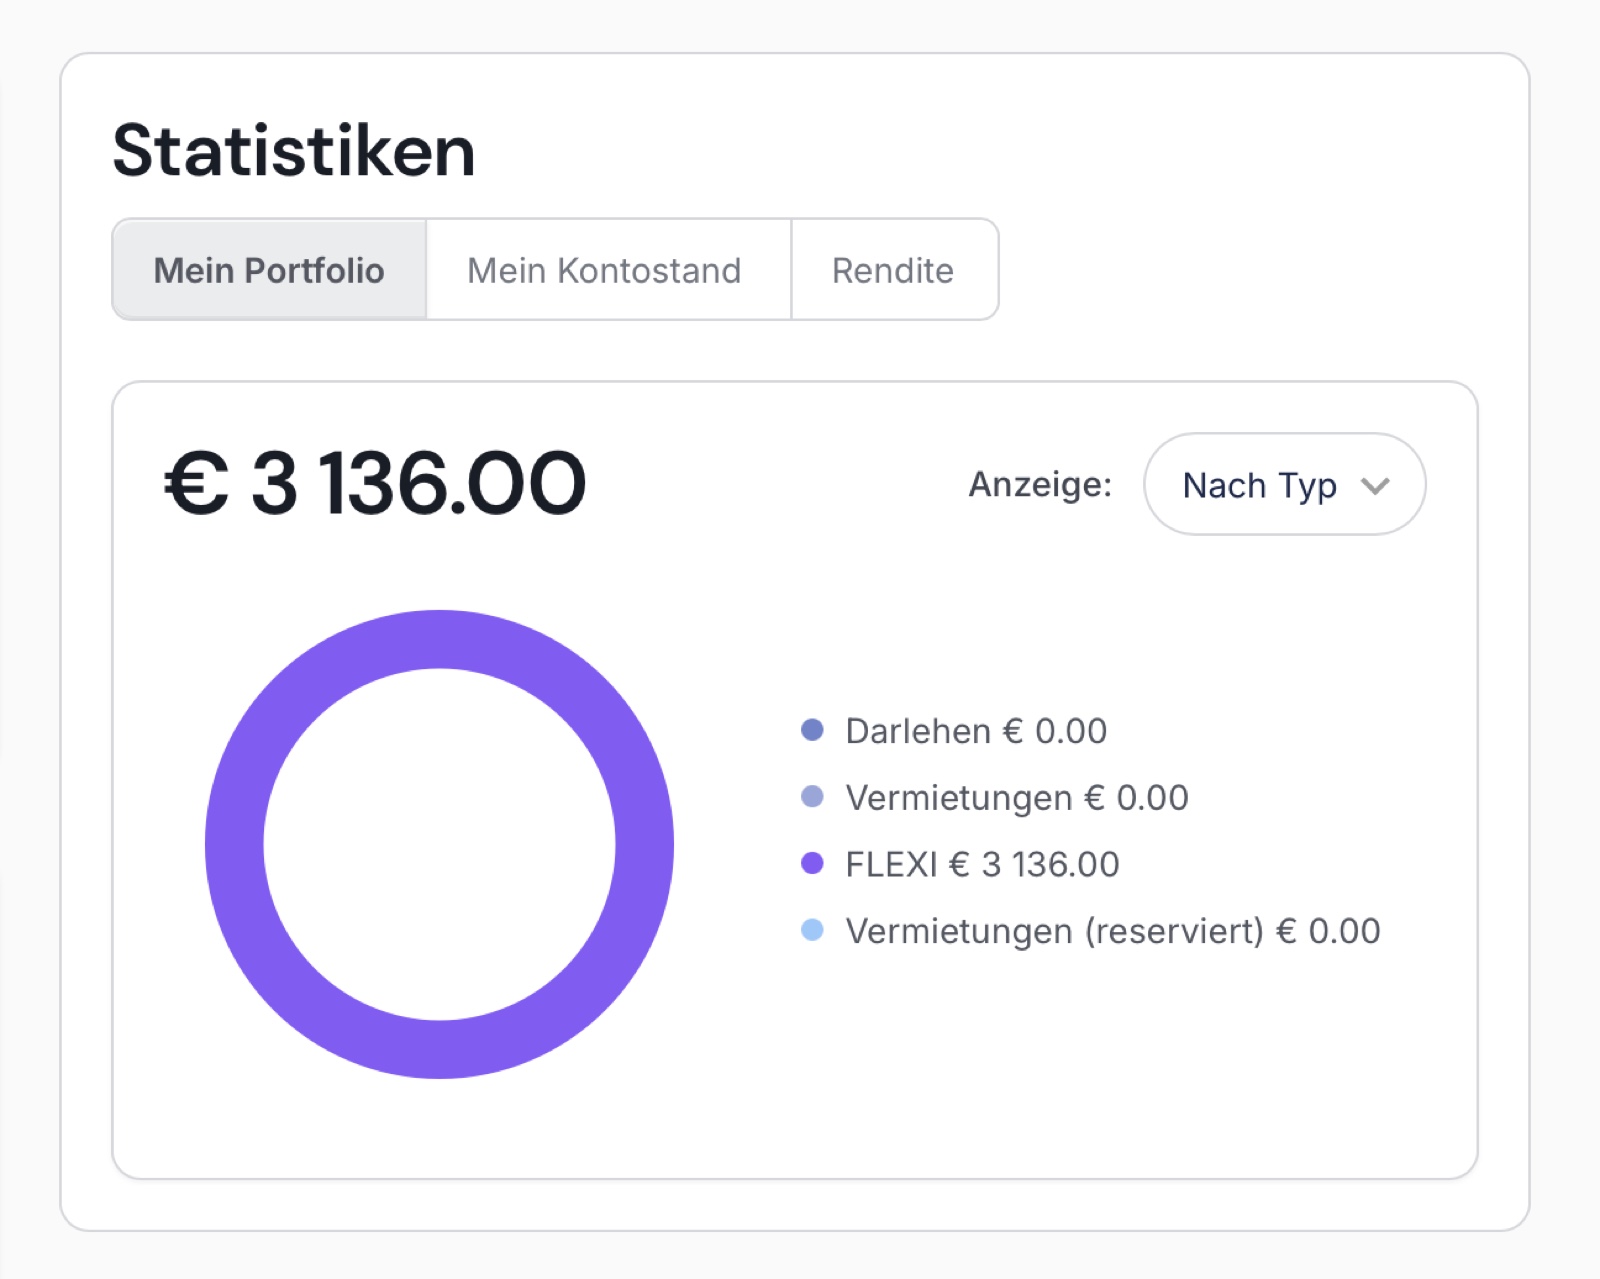
I've been investing with TWINO since April 2026 and have built up my account via a savings plan since then. It currently sits at around €3,138 – and is now entirely in FLEXI:
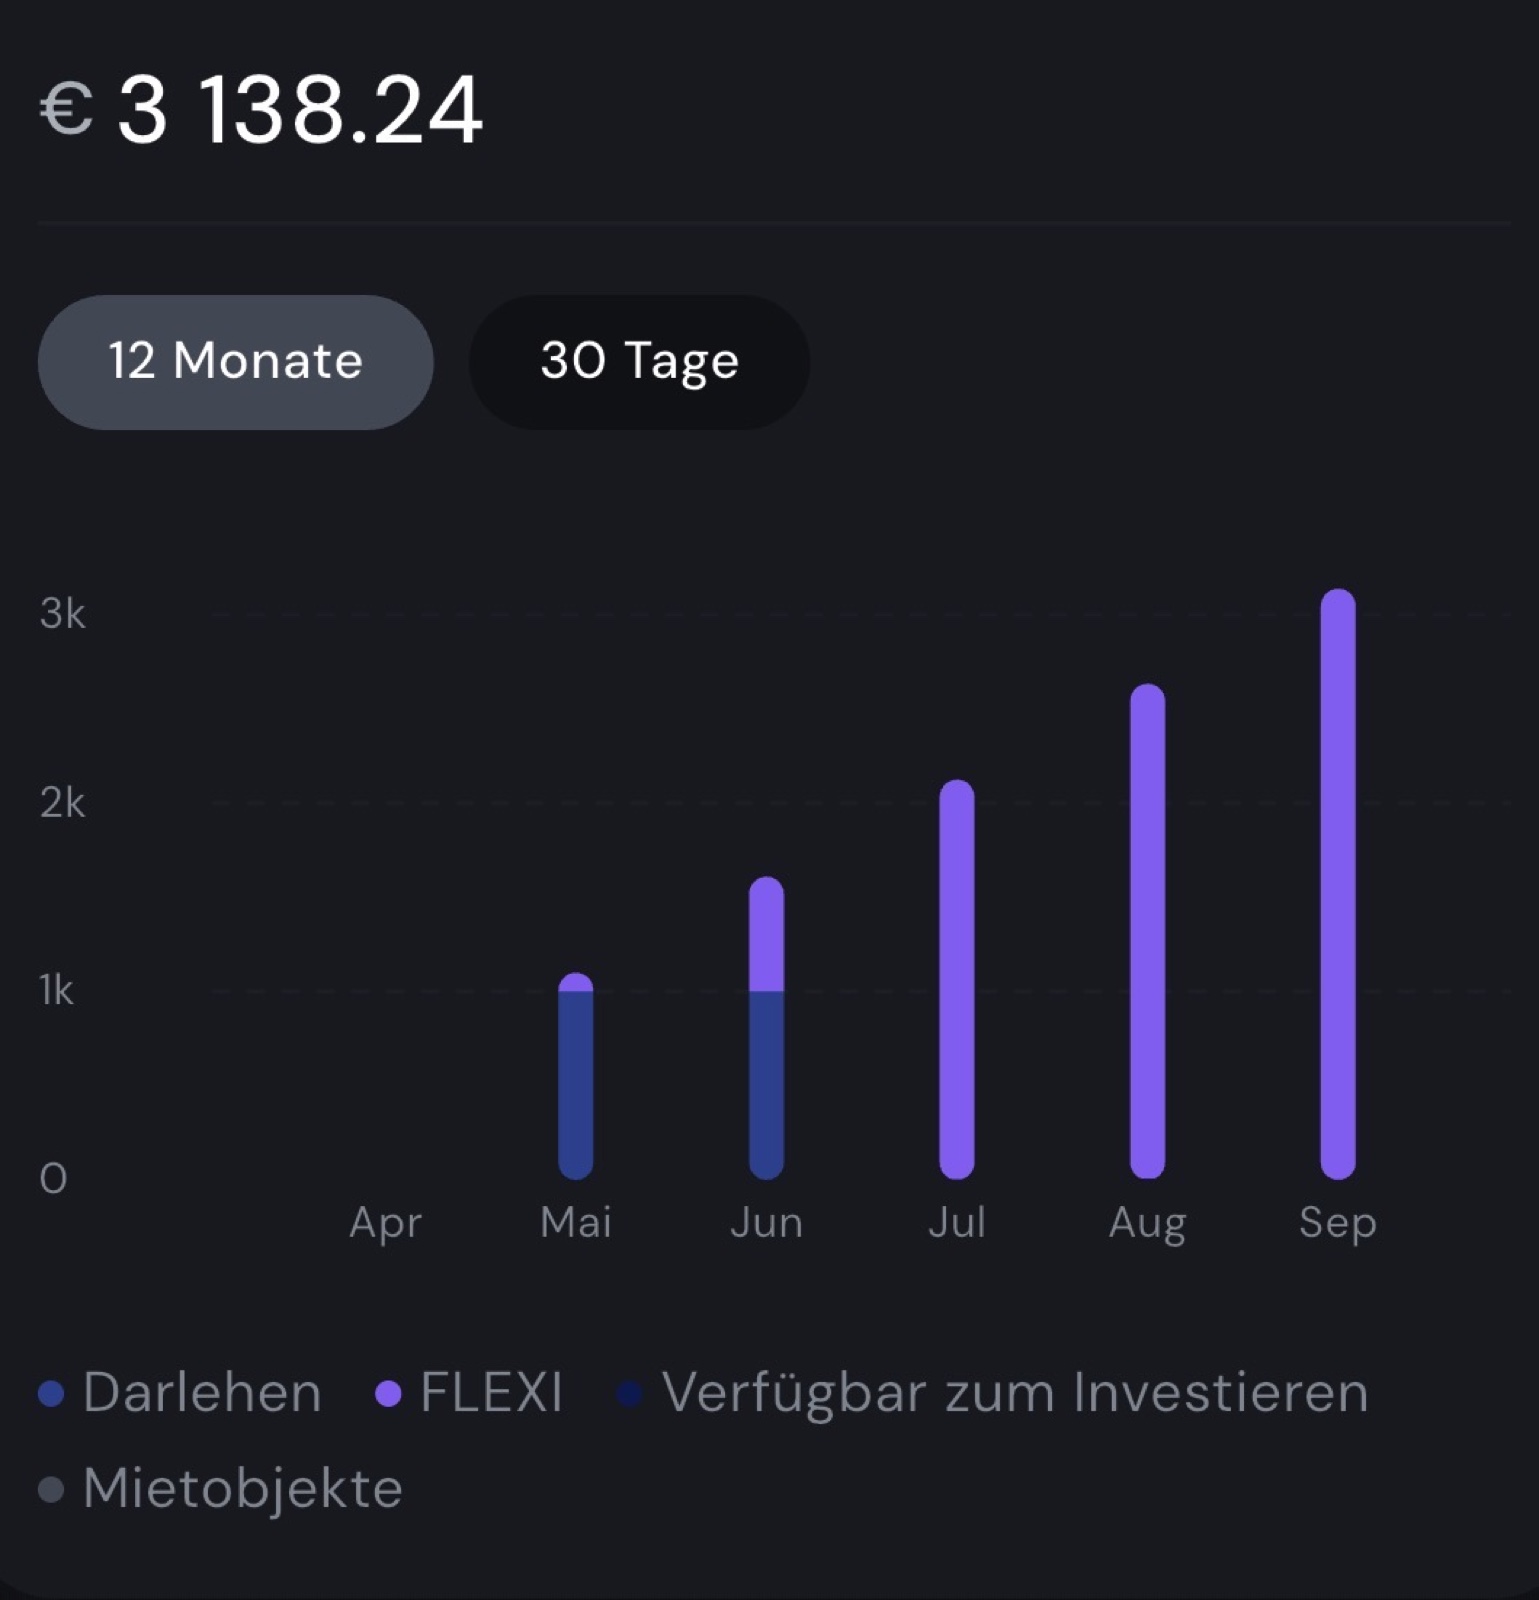
You can also nicely see how the account has grown since spring – first through individual loans, now almost entirely through FLEXI:
Why FLEXI? Because for me it's the simplest, most flexible building block – more on that in a second. My goal is to build up the FLEXI balance via a savings plan to the €10,000 limit (the maximum per investor in FLEXI, more below).
What is TWINO FLEXI?
FLEXI is TWINO's flexible product, introduced in April 2026. The key facts:
- 6% fixed annual return, accrued daily and paid out monthly
- withdraw any time – FLEXI is designed for instant liquidity
- invested in 12-month asset-backed securities (ABS) with consumer loans from Netcredit (Poland)
- maximum €10,000 per investor, up to 5 withdrawal requests per day
- entry from €10, no product fees
An honest addition: the 6% is fixed but not guaranteed, and FLEXI is not a savings account. TWINO itself notes that withdrawals can take longer in periods with many withdrawals – in the base prospectus the liquidity risk is rated "high". There's no deposit insurance.
Video: TWINO Update September 2026: FLEXI, up to 2% Cashback, Moneza Repaid – My Review
The full update is also available as a video – I walk through my TWINO account, FLEXI, the cashback promotion and the news. Feel free to watch, or read on below.
FLEXI or regular ABS: 6% or up to 12%?
Alongside FLEXI there are the regular ABS securities. The difference is essentially a trade-off between flexibility and return:
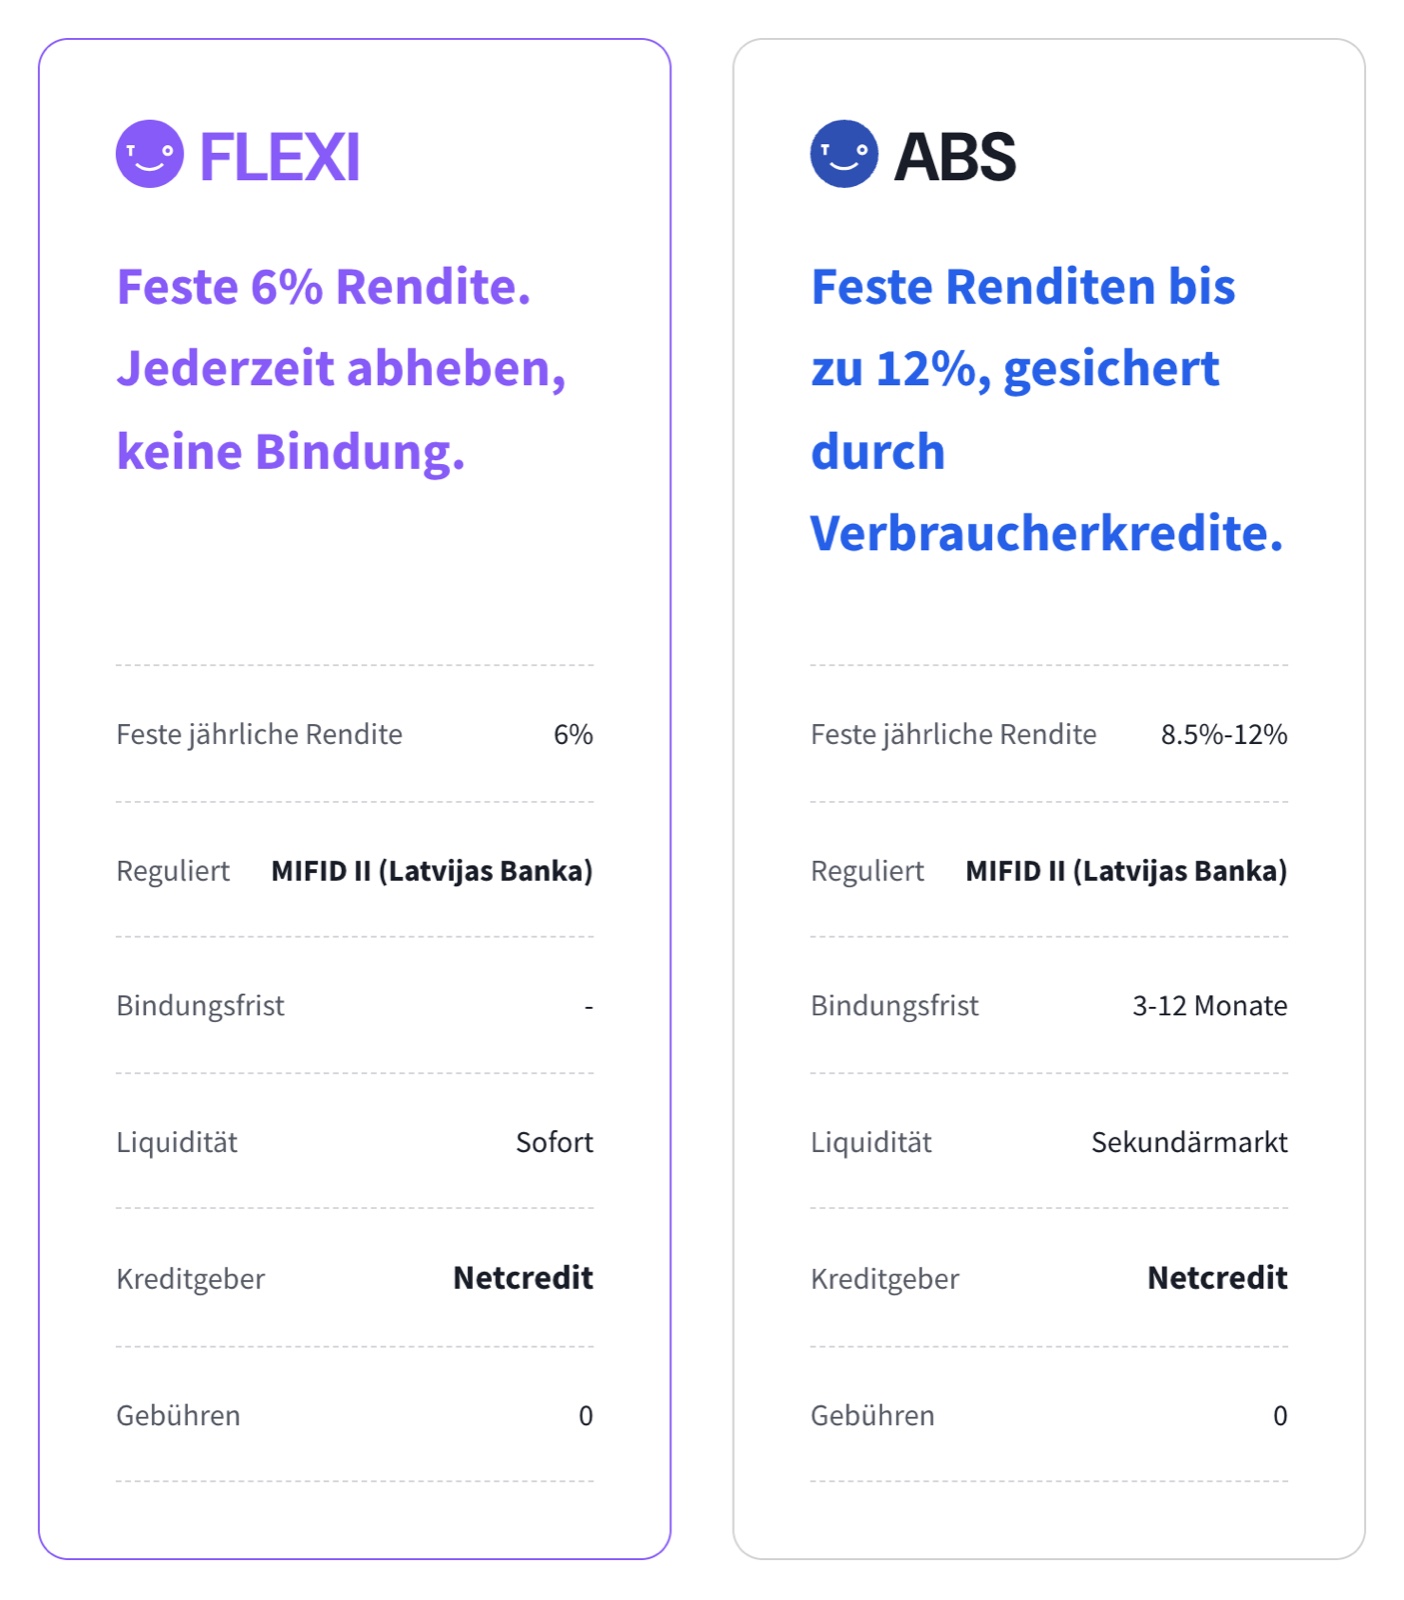
- FLEXI: 6% fixed, instantly liquid, no lock-up – ideal as a flexible building block.
- ABS: 8.5–12% fixed (12% for the 12-month term), but locked for 3–12 months, liquidity only via the secondary market.
Both are MiFID-II-regulated and run through the same loan originator (Netcredit). If you want the higher return and won't need the money for a while, you take ABS; if you want flexibility, you take FLEXI. I've deliberately chosen FLEXI – at least for the current build-up.
New: automatic repayments into the FLEXI wallet
A handy new feature since 11 August 2026: TWINO can automatically move eligible repayments (interest and/or principal) from your ABS in the main wallet into FLEXI, so the money doesn't sit around earning nothing. You activate this under the main wallet card in the dashboard. Important: only repayments are moved – your regular deposits stay untouched.
Current promotion: up to 2% cashback
TWINO has extended its cashback promotion – it currently runs until 14 December 2026. Through my link* you get, as a new customer, up to 2% cashback on your primary-market investments. Here's how it works:
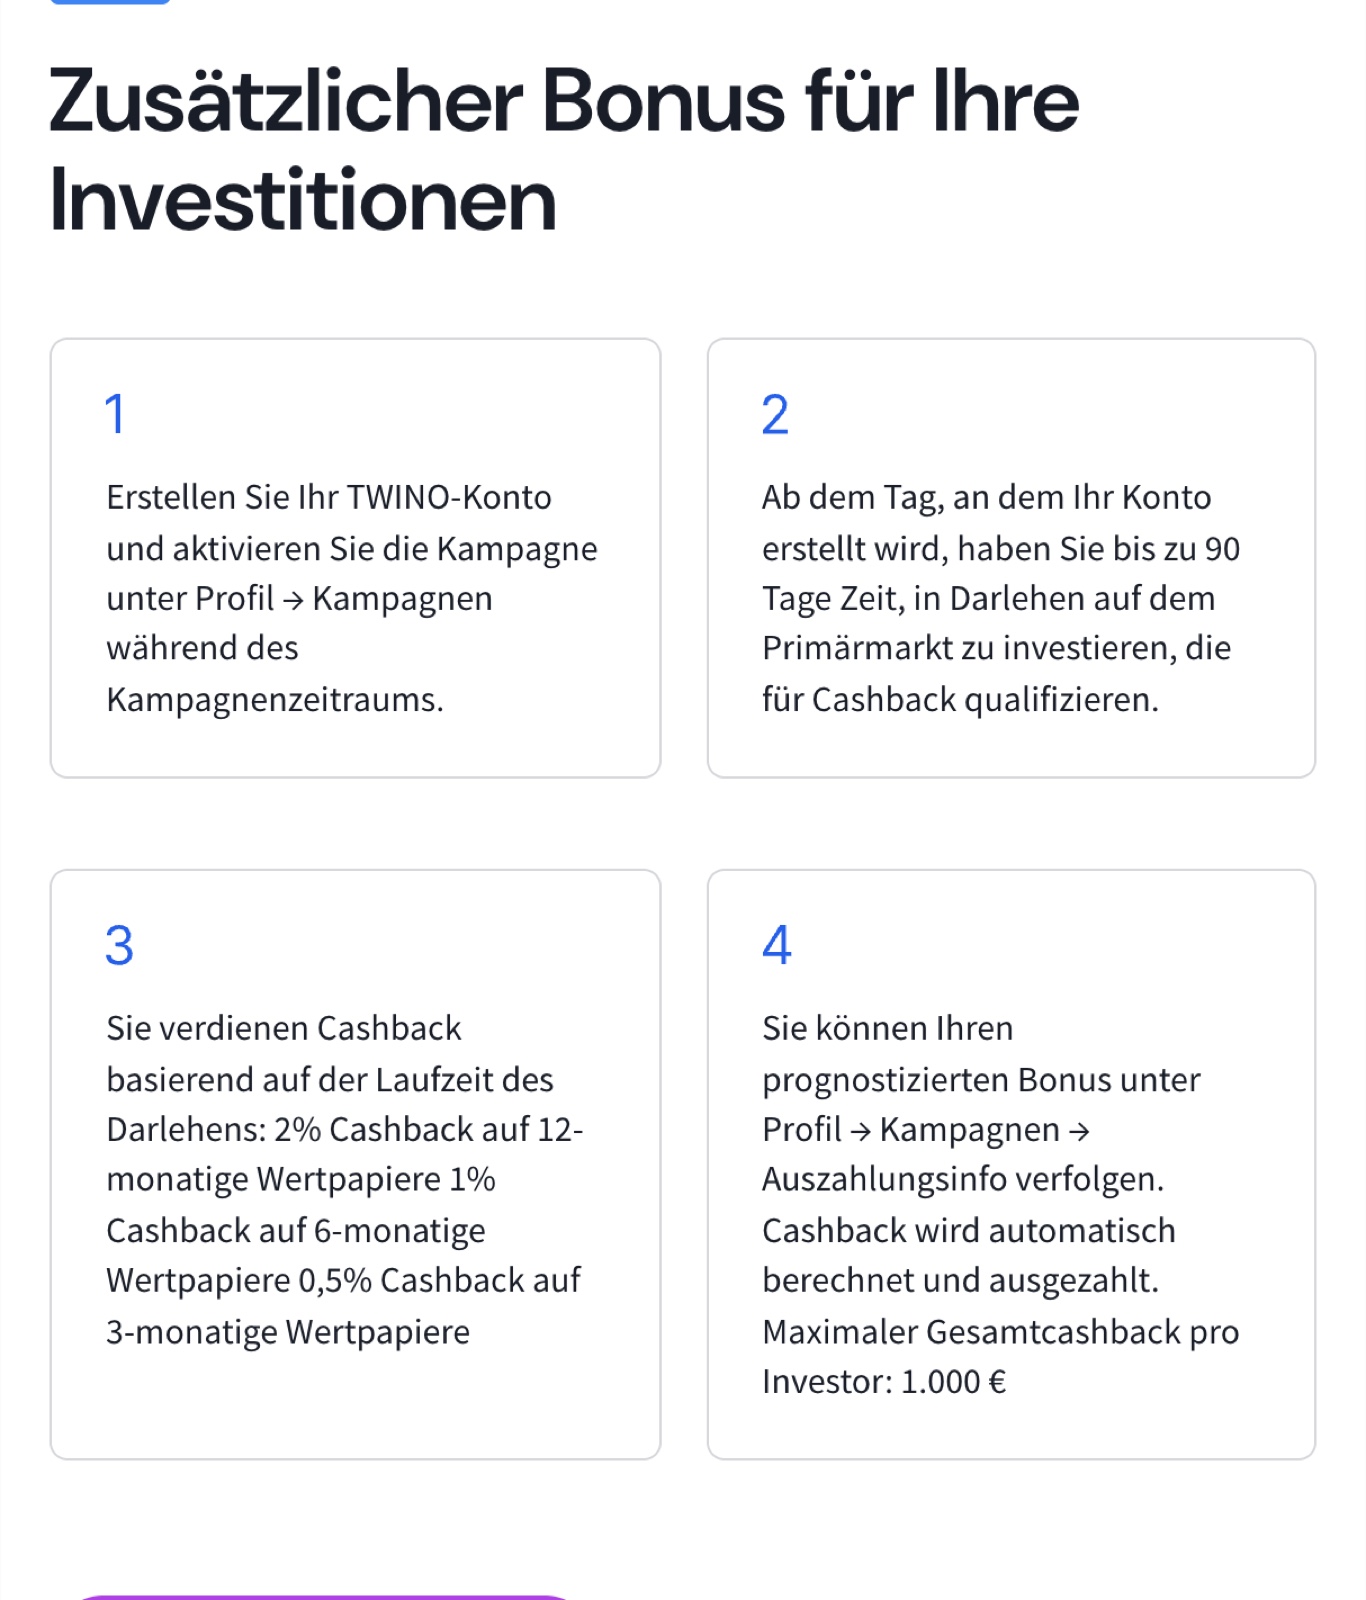
- Create account & activate: switch on the campaign under Profile → Campaigns.
- 90 days: from account creation you have up to 90 days to invest on the primary market.
- Tiered rates: 2% on 12-month, 1% on 6-month, 0.5% on 3-month securities.
- Cap: a maximum of €1,000 cashback per investor.
Two important restrictions I want to state clearly: FLEXI does not count toward the cashback – you have to invest in ABS on the primary market, hold the securities until repayment and not offer them for sale on the secondary market. And the promotion is for new customers. Check the current terms directly at TWINO before you start – deadlines and details can change.
Moneza fully repaid
Really good news for anyone who's known TWINO longer: the tiresome Moneza chapter from Russia is closed. In August 2026 TWINO completed the recovery of all outstanding investor funds related to Moneza, its former Russian loan originator.
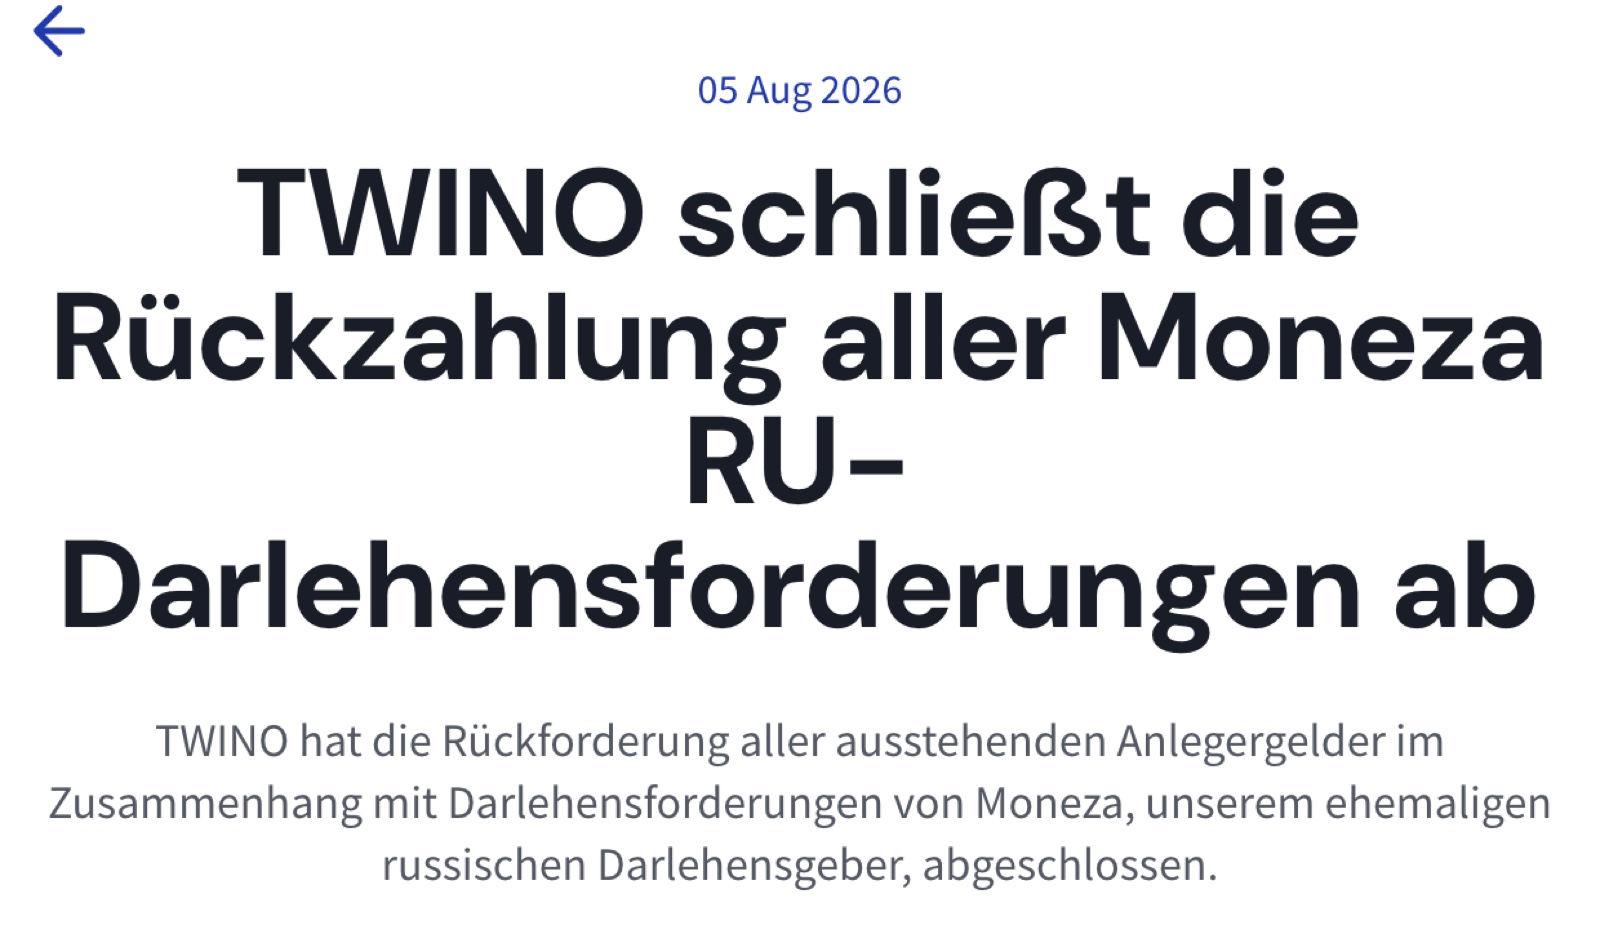
According to TWINO, the outstanding balance is zero, principal and interest have been recovered and paid out, and there is no remaining exposure to Moneza or Russia. After the war years, in which recovery was hampered by Russian capital controls, that's a clean close.
The app grows up
The TWINO app (launched in May 2026) was initially more of an MVP. With version 1.3.0 (September 2026) you can now invest manually on the primary and secondary markets, deposit, withdraw and move between wallets. One detail for the thorough: Auto-Invest is reachable from the app but opens the web view – here the app isn't fully native yet.
How safe is TWINO?
TWINO isn't an unknown newcomer: TWINO Investments AS is licensed by the Bank of Latvia (Latvijas Banka) as an investment firm under MiFID II (valid since 31 August 2021) and, since June 2026, additionally holds a MiCA authorisation. The platform has been around for over a decade.
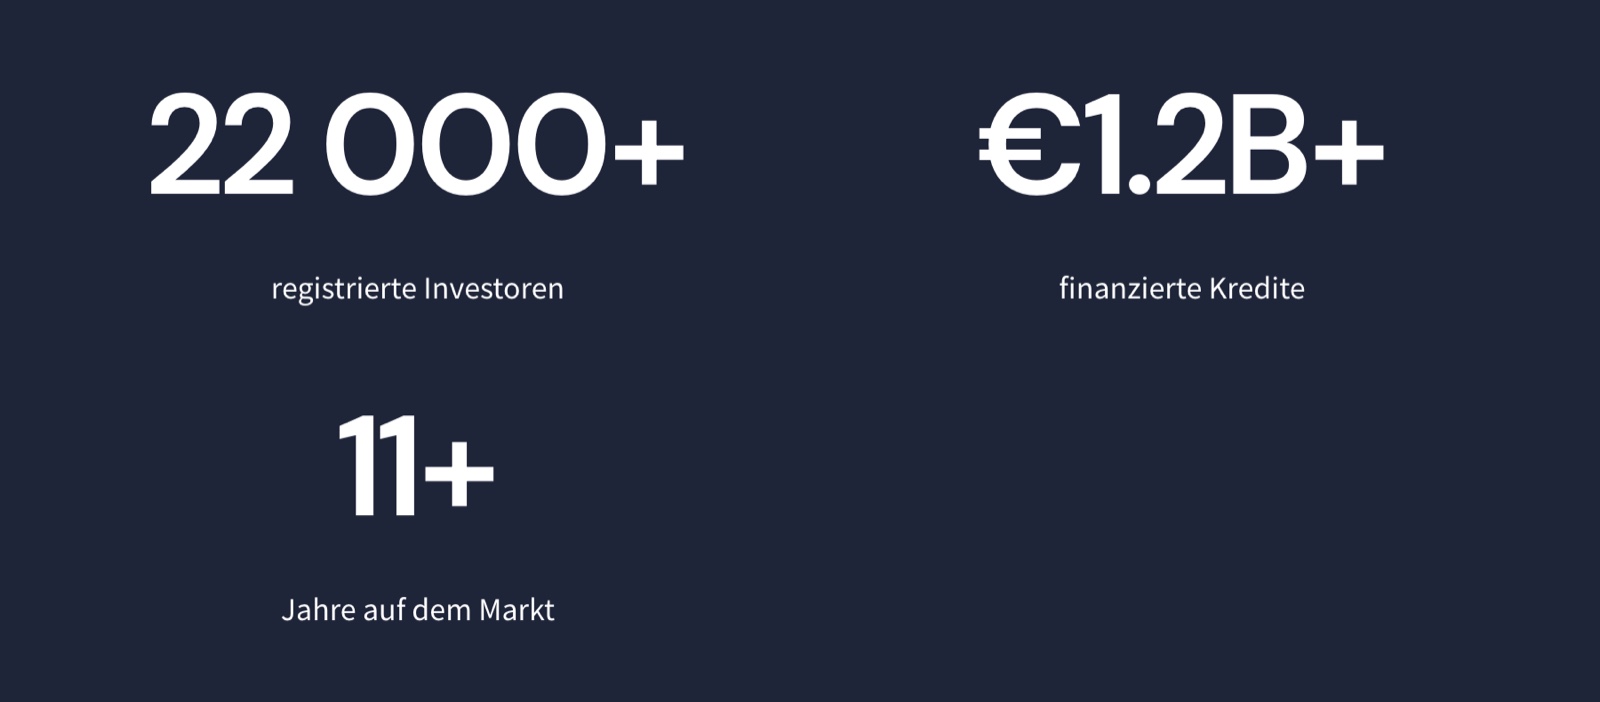
The numbers: 22,000+ registered investors, over €1.2B in loans funded, 11+ years on the market. There's EU investor compensation of up to €20,000 – but note: it only applies if TWINO itself fails, not for credit defaults or price losses. The credit risk still sits with you, and there's no deposit insurance like with an instant-access account.
Who is TWINO right for?
- want a flexible liquidity solution at 6% (FLEXI)
- want higher rates up to 12% (ABS) for fixed terms
- prefer a MiFID-II-regulated platform with a securities account
- want to grab the up to 2% cashback in ABS as a new customer
- need a guaranteed return or real deposit insurance
- depend on always-guaranteed instant availability
- only invest in FLEXI but still expect cashback
- can't bear the capital risk of consumer loans
My plan and verdict
My plan is clear: I'll keep topping up FLEXI via a savings plan at around €500 a month until I reach the FLEXI maximum of €10,000 – from the current ~€3,138 that's a good year away. For me, FLEXI is the flexible, no-fuss building block in the P2P space: 6% fixed, accrued daily, accessible any time.
Bottom line, TWINO is on a good run right now: FLEXI as a simple liquidity solution, up to 12% on the ABS, an ongoing cashback promotion, the closed Moneza chapter and a more grown-up app – all on a MiFID-II-regulated platform. The risks remain (no deposit insurance, capital at risk, FLEXI liquidity slower under stress), but for me the mix adds up. If you want to try TWINO, best to grab the cashback right away: go to TWINO through my link*.
Links marked with * are partner links. If you invest through them, you support my work – at no extra cost to you. Thank you!
Frequently asked questions
What is TWINO FLEXI and how does it work?
FLEXI is TWINO's flexible product: you get a fixed 6% annual return, accrued daily and paid out monthly, and you can generally withdraw your money at any time. Your money is invested in 12-month asset-backed securities (ABS) with consumer loans from Netcredit in Poland. The maximum is €10,000 per investor, with up to 5 withdrawal requests per day.
How high is the return on TWINO?
There are two routes: FLEXI pays a fixed 6% p.a. with full flexibility. The regular ABS securities pay a fixed 8.5–12% per year with a 3–12 month lock-up – 12% for the 12-month term. Higher return in exchange for less flexibility, that's the core of the decision. Both are fixed-rate but not guaranteed – your capital is at risk.
How quickly can I get my money out of FLEXI?
FLEXI is designed for instant liquidity: withdrawals are usually processed quickly. But TWINO itself notes that in periods with many withdrawals (e.g. crisis situations) it can take longer – in the base prospectus the liquidity risk is rated 'high'. There's no fixed payout deadline; bank transfers usually take up to 2 business days.
How does the TWINO cashback promotion with up to 2% work?
As a new customer you get up to 2% cashback on your primary-market investments through my link. You create your account, activate the campaign under Profile → Campaigns, and then have up to 90 days to invest. The rates are tiered: 2% on 12-month, 1% on 6-month and 0.5% on 3-month securities, capped at €1,000 per investor. The promotion currently runs until 14 December 2026 – check the terms before you start.
Does FLEXI count toward the cashback?
No. Per the campaign terms, FLEXI investments are excluded from the cashback – you have to invest in ABS on the primary market, hold the securities until repayment and not list them for sale on the secondary market. So if you only invest in FLEXI, you don't get cashback.
Is TWINO legit and regulated?
TWINO Investments AS is licensed by the Bank of Latvia (Latvijas Banka) as an investment firm under MiFID II (licensed since 31 August 2021) and, since June 2026, additionally holds a MiCA authorisation. There's EU investor compensation of up to €20,000 – but only in the event that TWINO itself fails, not for credit defaults or price losses. There's no deposit insurance like with an instant-access account.
Has the Moneza money from Russia been repaid?
Yes. In August 2026 TWINO completed the recovery of all outstanding investor funds related to Moneza, its former Russian loan originator. According to TWINO the outstanding balance is zero, principal and interest have been recovered and paid out, and there's no remaining exposure to Russia.
Can you invest in the TWINO app?
Yes, the app has come a long way: since version 1.3.0 (September 2026) you can manually invest on the primary and secondary markets, deposit, withdraw and move between wallets. Auto-Invest is reachable from the app but opens the web view – here the app isn't fully native yet.
Disclaimer
⚠️ Not investment advice
All content is for information and entertainment purposes only and does not constitute investment advice, a buy recommendation or an invitation to enter into a financial product. Please do your own research and make decisions based on your personal situation and risk tolerance.
📉 Risk warning & total loss
Investments in securities and other financial instruments generally carry significant risks (e.g. price, market, currency, volatility and credit risks). A total loss of the capital invested cannot be ruled out.
📊 Returns & forecasts
All performance figures, whether historical or as a forecast/estimate, are not a reliable indicator of future results. Capital and returns are not guaranteed.
🔍 Transparency & conflicts of interest
I strictly distinguish between facts and personal estimates. Important: I am often invested in the assets discussed myself, which can create a conflict of interest.
✅ DYOR (Do Your Own Research)
All information has been compiled carefully but is non-binding, without warranty and without any claim to completeness. Please inform yourself thoroughly and consider all opportunities and risks in depth before making an investment decision.
Advertising & affiliate notice
Links marked with * are advertising or affiliate links. If you sign up or buy something through such a link, I may receive a commission – at no extra cost to you. This supports my work.