Lendermarket Update October 2026: €8,169 in My Account, 1.5% Cashback & How I Invest via Auto Invest FLEX
My Lendermarket update for October: I have added another €2,000 and passed the €8,000 mark – account value €8,168.99, average interest rate 12.29%. I show you the current platform statistics (€694.4m invested, €62.4m active portfolio, default rate of 0.00% according to Lendermarket), my €168.49 of income, my late loans and my four portfolios in Auto Invest FLEX – including the 3.5% fee for an early exit. Plus: 1.5% cashback for new customers through my link, and why €10,000 is where I stop.
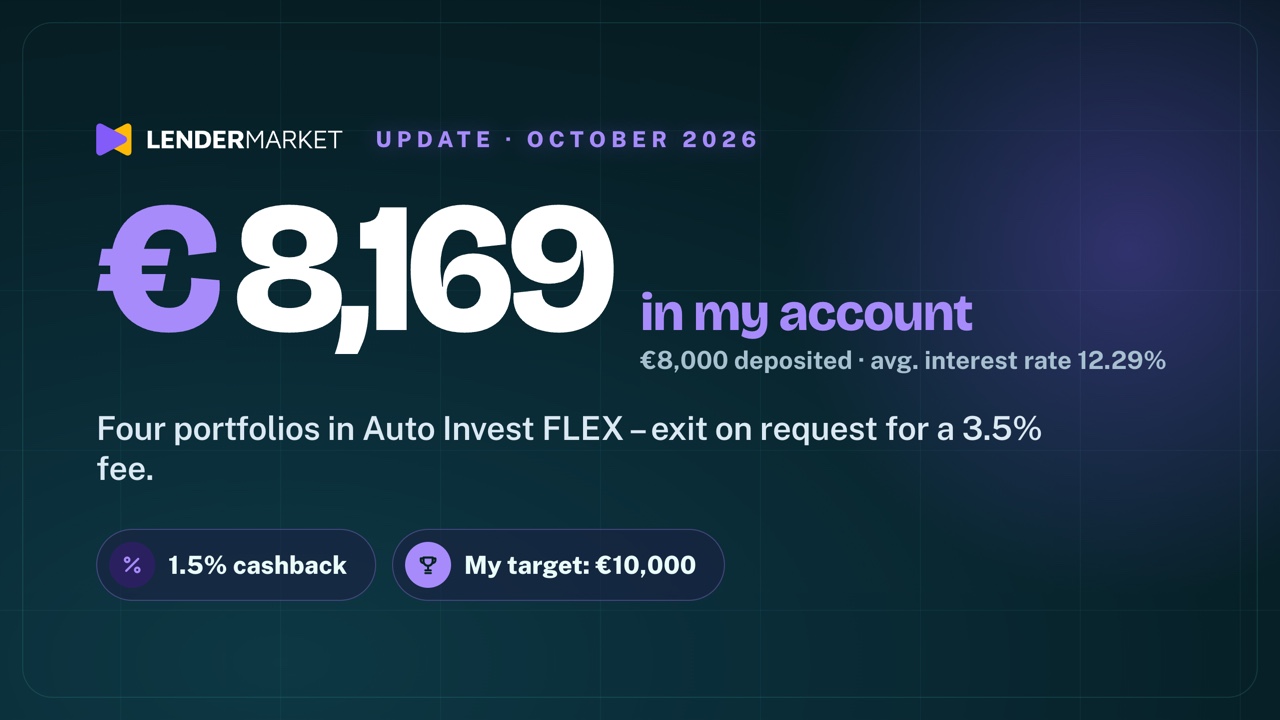
Table of contents
- Lendermarket in numbers: €694.4m invested
- 1.5% cashback through my link
- Video
- My Lendermarket account: €8,168.99
- My investments: what is late
- How you can invest on Lendermarket
- Auto Invest FLEX: exiting for a 3.5% fee
- My four portfolios
- How safe is Lendermarket?
- Is Lendermarket worth it?
- My plan and conclusion
- FAQ
I have been invested on Lendermarket for several months now and am currently topping up the platform really aggressively. I have now passed the €8,000 mark and want to complete the €10,000 – which is also my personal upper limit. In this post we look at why I am topping up here, how exactly I invest on Lendermarket, what the current statistics say – and which cashback you can get as a new customer through my link.
As always, the most important thing first: this is not investment advice and not a buy recommendation, just my personal opinion and my personal investments. I am responsible for my money, you are responsible for yours. P2P loans are high-risk – only invest money whose total loss you could handle, and make your own decisions. The Lendermarket link is a referral link: if you use it, I receive a small commission, and it does not cost you anything extra.
Lendermarket in numbers: €694.4m invested
First of all, we start with the current statistics. Lendermarket shares them very transparently on its website, and they give us an overview of how the platform is developing.
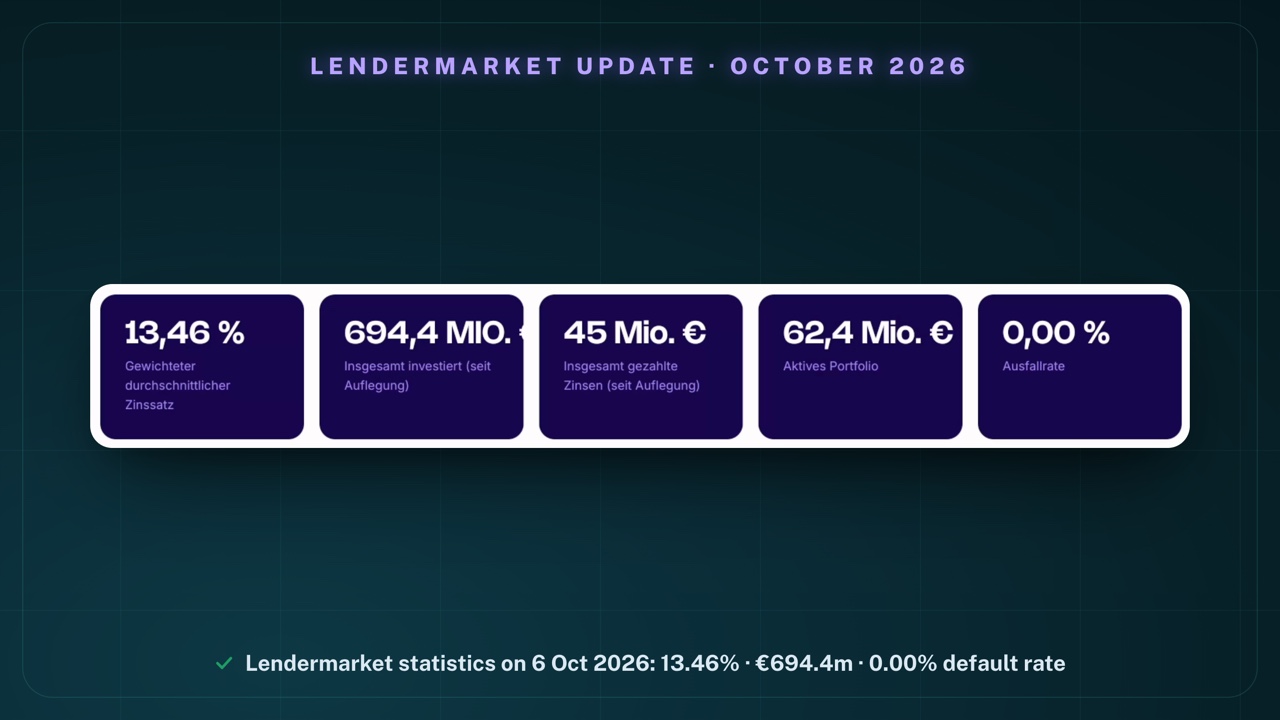
The most interesting figure is right on the left: the weighted average interest rate, which stands at 13.46%. In a moment we will check in my dashboard how realistic that is and where mine stands.
- Invested in total: more than €694m
- Interest paid in total: €45m
- Active portfolio: €62.4m – so really not small
- Default rate: 0.00%
The figure on the far right, the default rate, is also one of the reasons why I am currently topping up substantially on Lendermarket. More on that shortly – first a few more numbers.
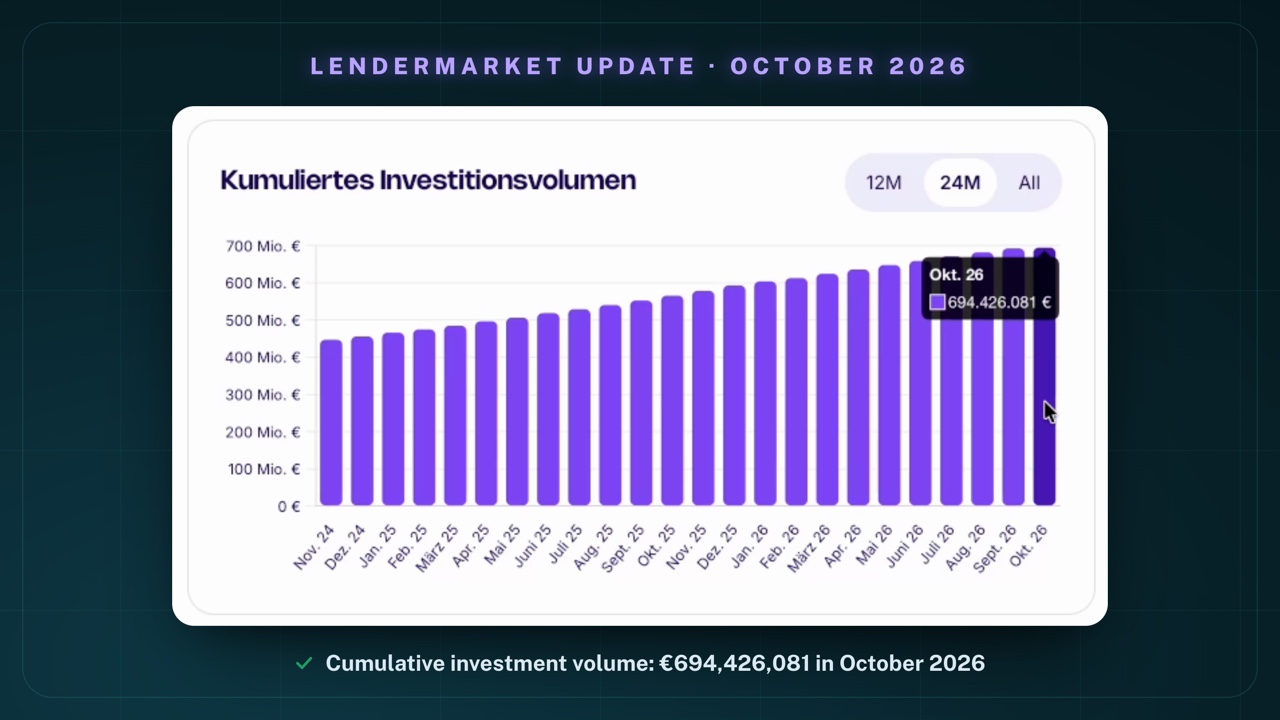
Here we see the cumulative investment volume over time. Over the last 24 months it has grown from €447m in November 2024 to €694m now:
If we look at the active portfolio across the whole series, it has actually been higher before: the peak so far was in December 2025 at €62.8m.
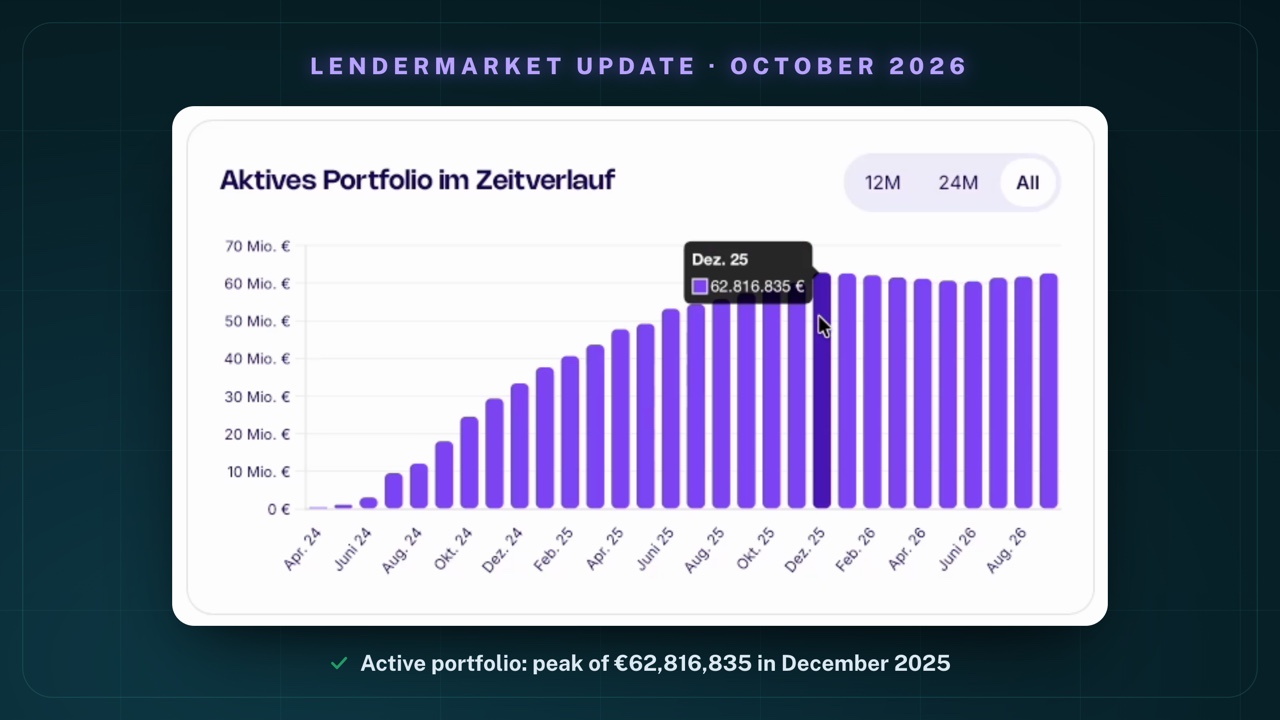
After that it dipped slightly. At the end of September the figure was €62.6m, and the tile above shows €62.4m for the day of the recording – so we are close to the record high again. The platform has been growing again for several months in terms of the active portfolio.
How are the loans performing?
What is also shown very transparently here is the loan data – that is, how much is actually late:
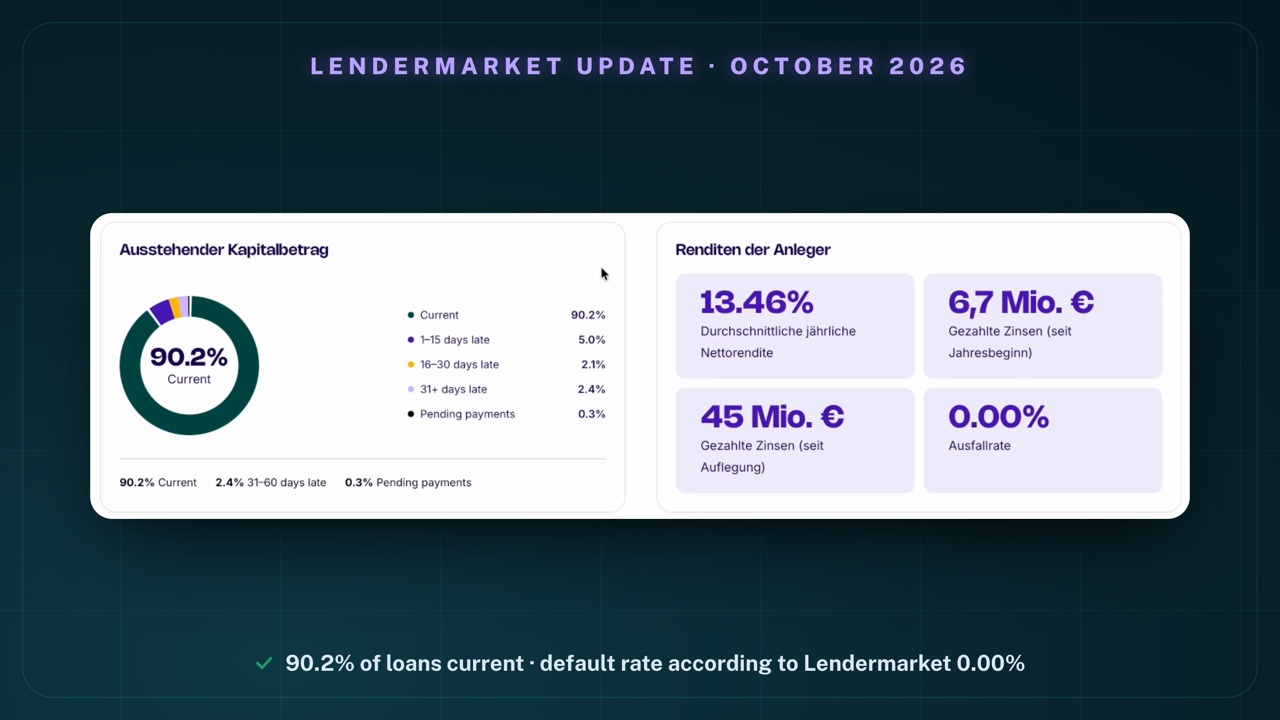
- Current: 90.2%
- 1 to 15 days late: 5.0%
- 16 to 30 days late: 2.1%
- More than 31 days late: 2.4%
- Pending payments: 0.3%
Delays are simply part of investing in loans. What matters is that the money does reach us eventually – that safety mechanisms such as a buyback obligation or active debt recovery kick in. And here Lendermarket states a default rate of 0.00% so far. That is a figure provided by the platform, not a promise for the future.
1.5% cashback through my link
Before we look at my investment, a quick note: if you want to try Lendermarket yourself, you can get 1.5% cashback on all your investments in the first 90 days as a new customer through my Lendermarket link*.
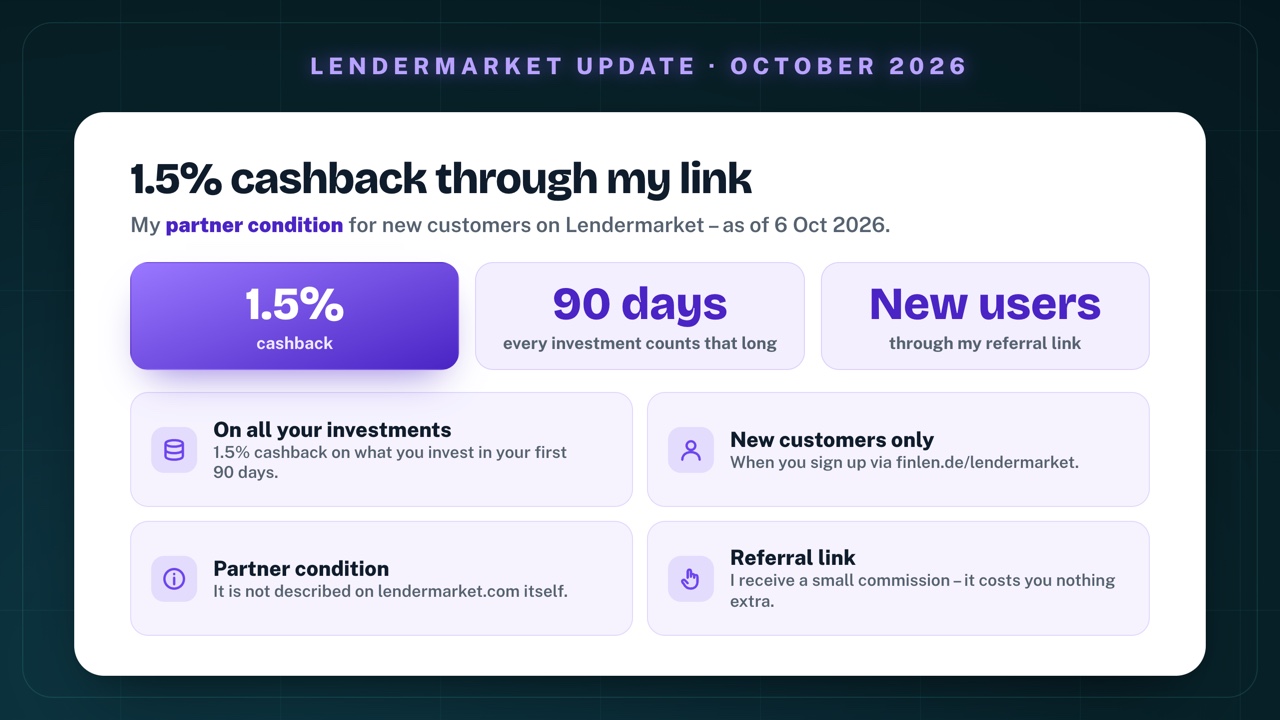
The 1.5% over 90 days is my partner condition (as of 6 October 2026) – it is not listed on the Lendermarket website itself. It is best to check the current terms directly with Lendermarket before you start; conditions can change.
For transparency: this is a referral link. If you sign up through it, I receive a small commission. It does not cost you anything extra – quite the opposite, you get this additional cashback and support me and my work.
Video: Lendermarket Update October 2026: €8,169 in My Account, 1.5% Cashback & How I Invest via Auto Invest FLEX
The full update is also available as a video – I walk live through Lendermarket's statistics page, my dashboard, my investments and my portfolios in Auto Invest FLEX. Feel free to watch, or read on below.
My Lendermarket account: €8,168.99
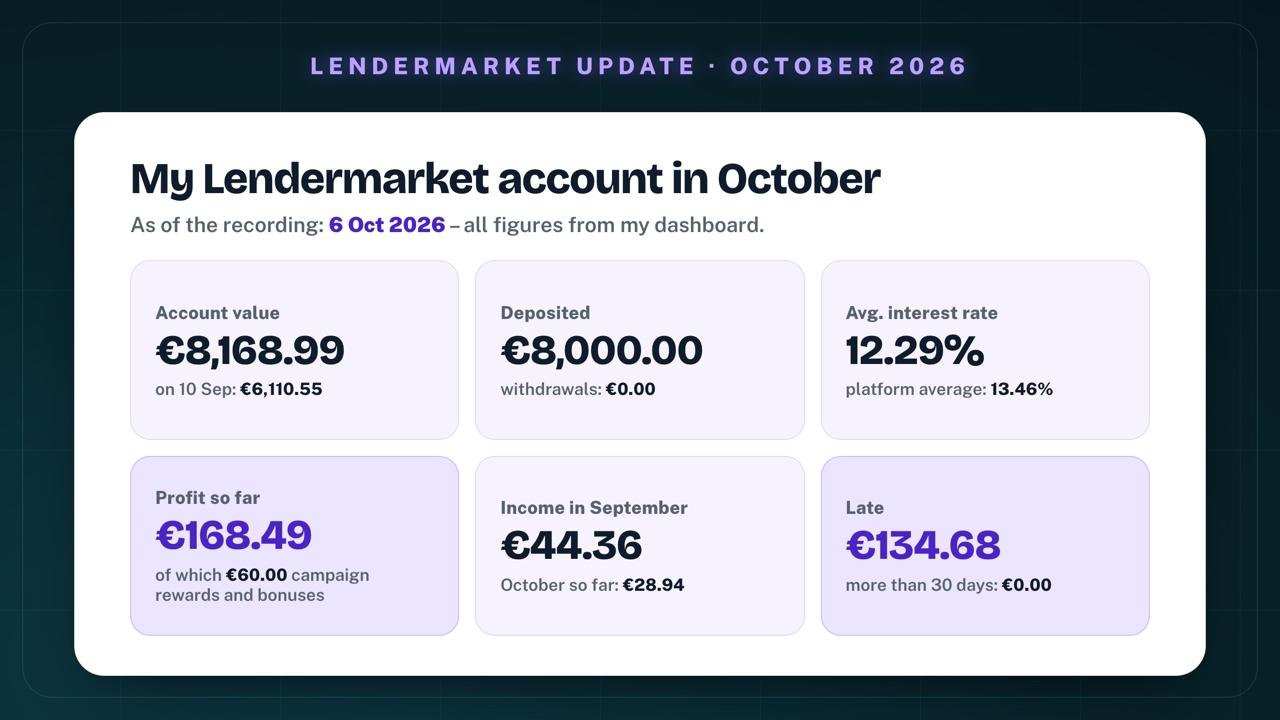
Then let's go into my portfolio (as of the recording: 6 October 2026):
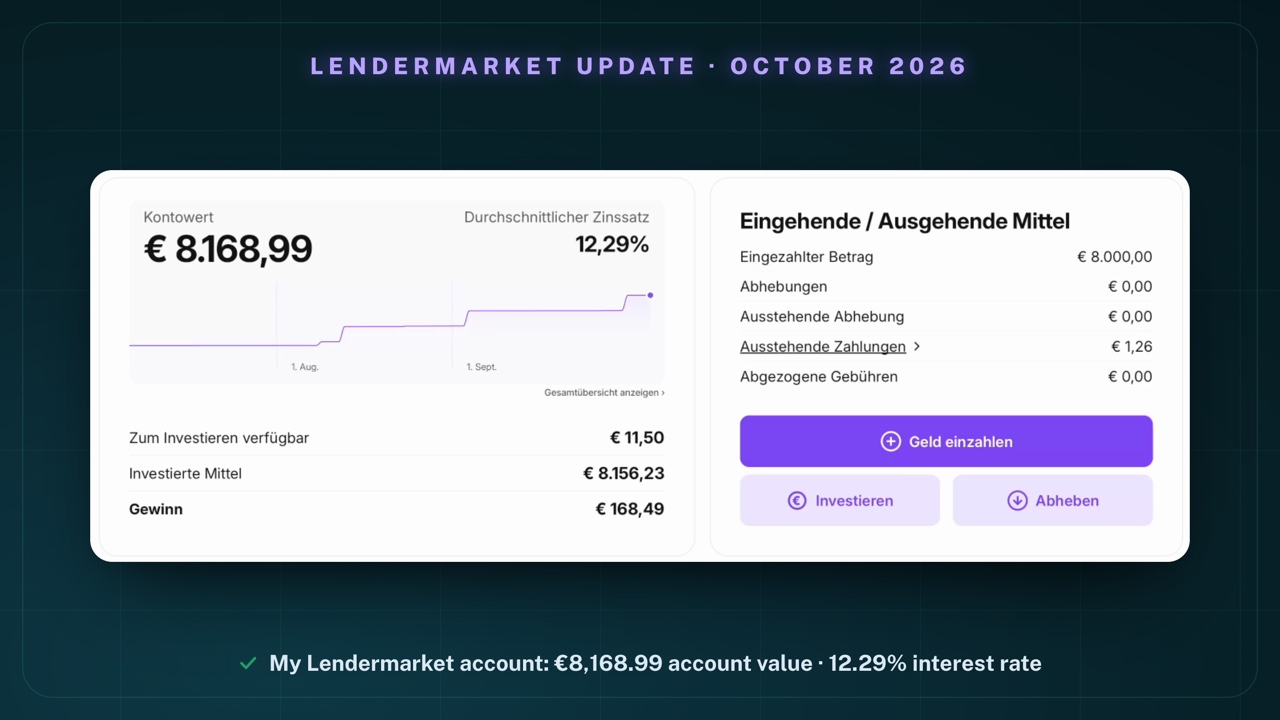
My account value is €8,168.99. I have just invested another €2,000, and you can see on the line that things really are moving up month after month for me: from around €1,500 to €4,000, to €6,000, to €8,000. Next month another €2,000 will follow – then I will have reached the €10,000 I set as my target.
- Deposited: €8,000.00
- Account value: €8,168.99
- Invested: €8,156.23 – €11.50 is idle
- Average interest rate: 12.29%
So my rate is slightly below the platform average of 13.46%. That is of course down to my loan selection – we will look at that in a moment.
€168.49 of income
And this is how much I have received so far:
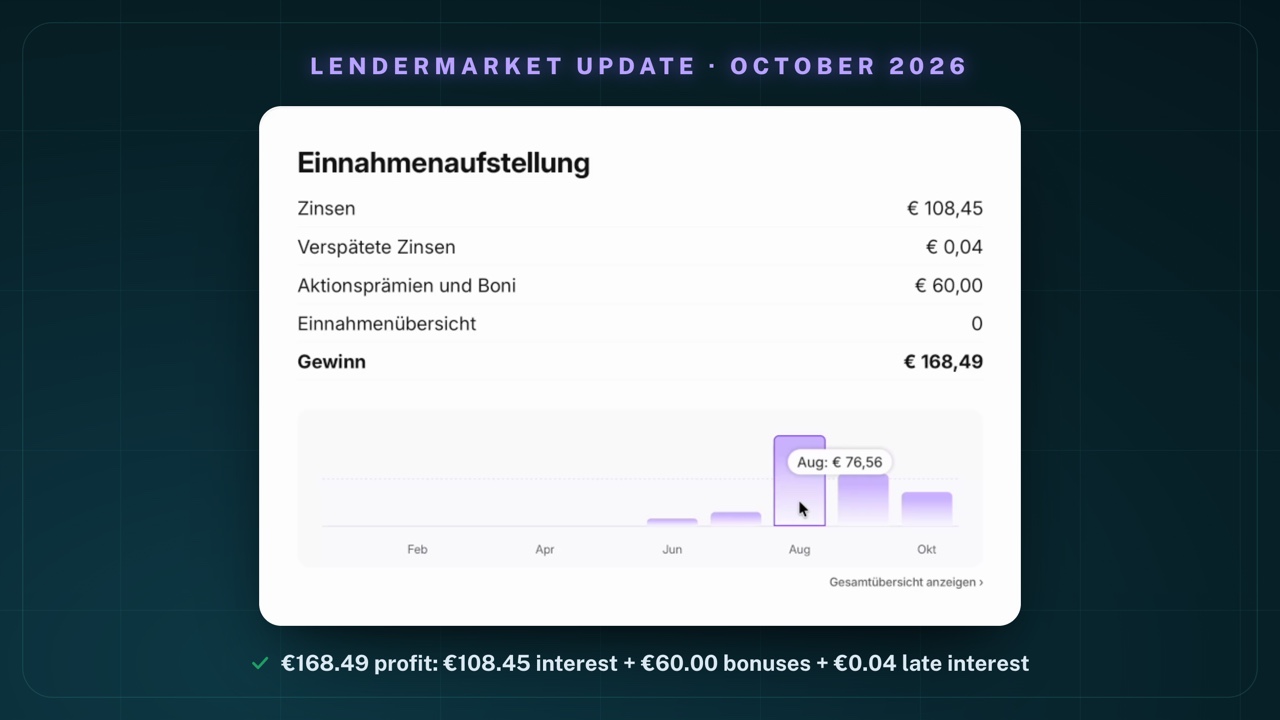
- In total: €168.49
- Interest: €108.45
- Campaign rewards and bonuses: €60.00
- Late interest: €0.04 – if a loan was late, default interest is paid on it
The development by month: in June it was €6.53, in July €12.10, in August a great deal because of the cashback at €76.56, in September €44.36. October already stood at €28.94 on the day of the recording – it should beat September by a wide margin.
Why I am building this position at all is something I described in detail in September: Lendermarket Review 2026.
My investments: what is late
Next we jump into my investments. There you can see how I am invested – and also what part of it is late:
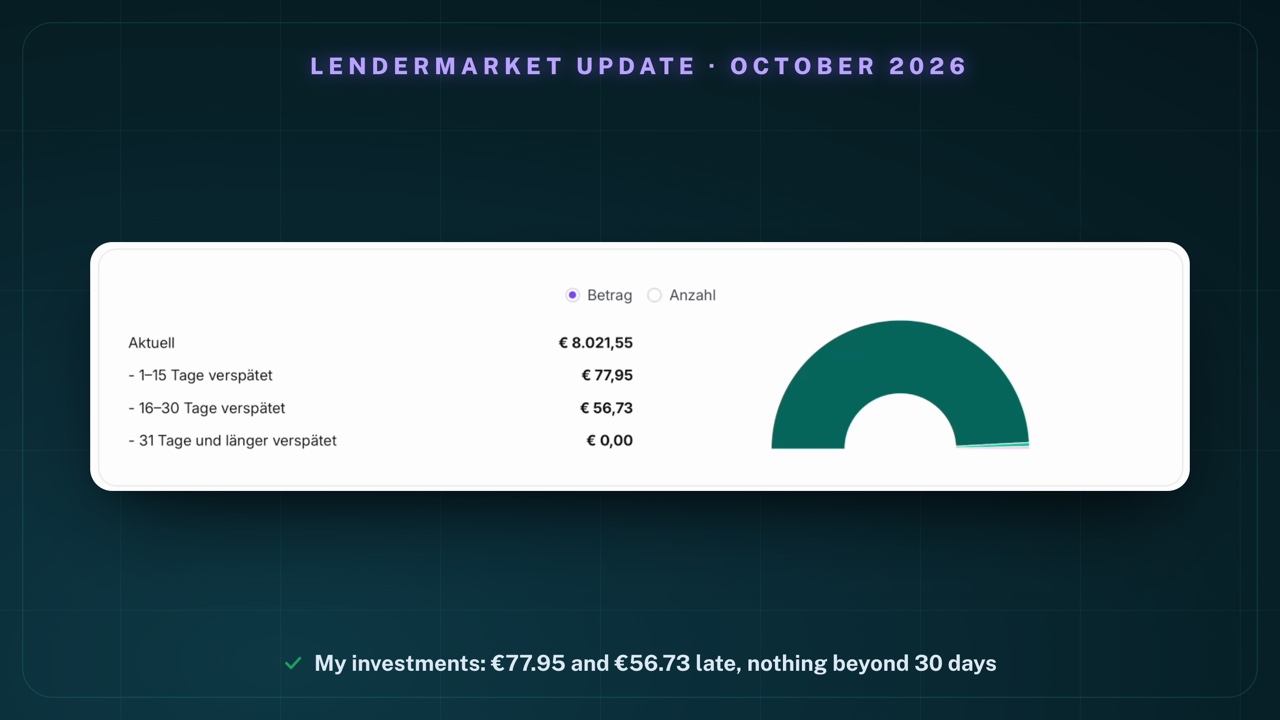
- Current: €8,021.55
- 1 to 15 days late: €77.95
- 16 to 30 days late: €56.73
- 31 days and more late: €0.00
As I said: that is simply part of it. But I am also very broadly diversified. I basically never have more than €100 in one loan, usually even a bit less.
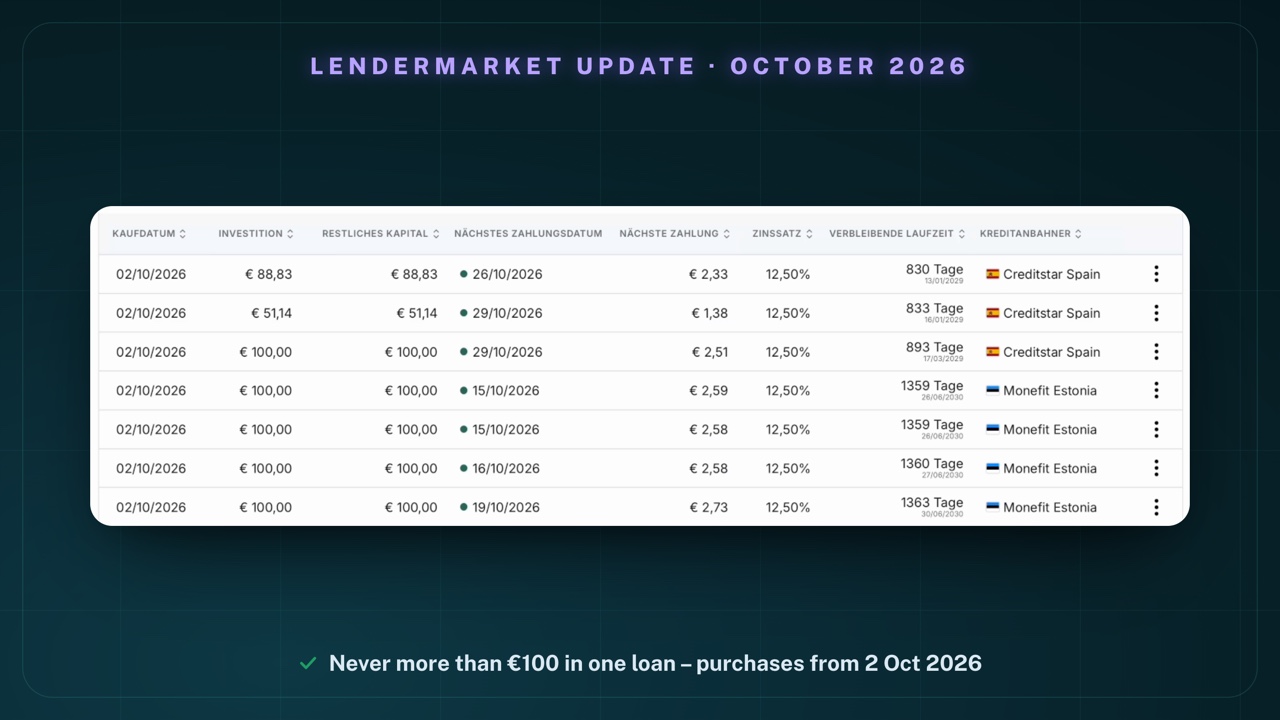
The list is definitely long – it runs over two pages.
How you can invest on Lendermarket
Now I will show you how I invest here. Because there are different options on Lendermarket:
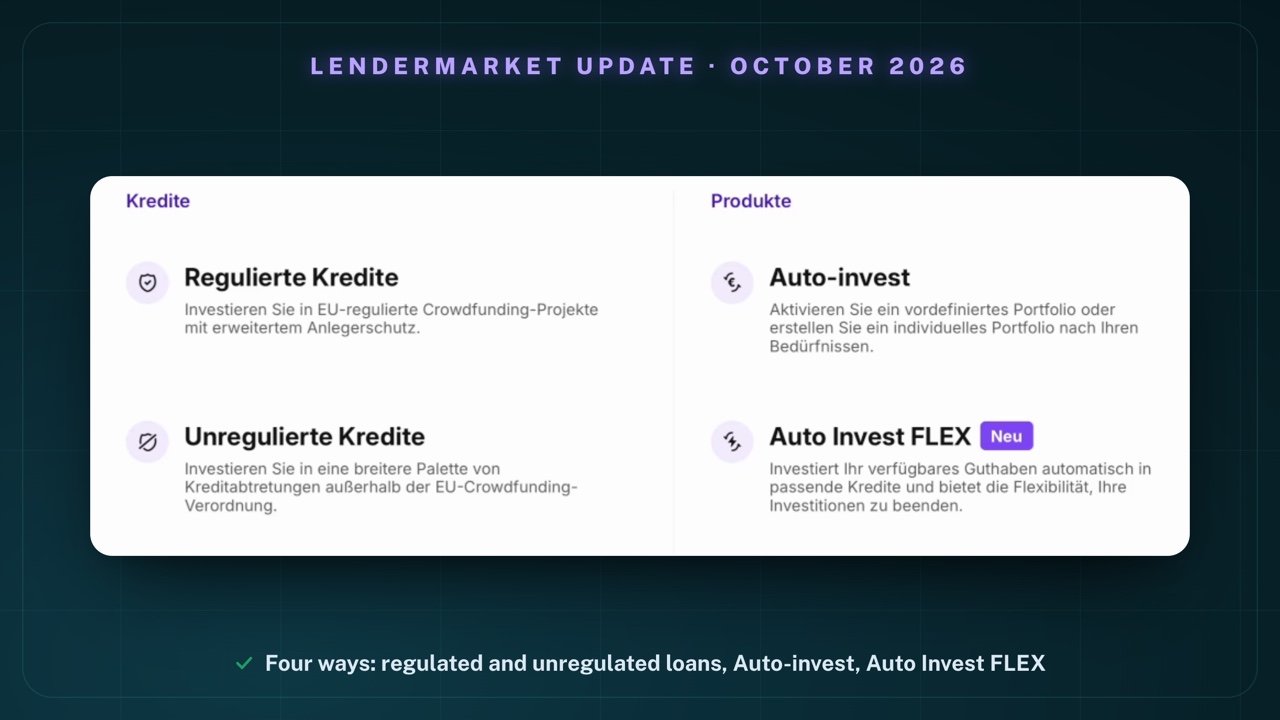
- Regulated loans – simply manually
- Unregulated loans
- Auto-invest
- Auto Invest FLEX
In the menu Lendermarket also advertises a “100% buyback guarantee”. That is why it is not a problem at first if something is late – it should be bought back. Of course there can be delays or problems there too. So far, though, as we saw from the default rate, this has worked very well on Lendermarket. Important for context: it is the loan originator who has to buy back, not Lendermarket – so the commitment is only worth as much as the loan originator itself.
Auto Invest FLEX: exiting for a 3.5% fee
So far I invest on Lendermarket almost exclusively through Auto Invest FLEX. It is a relatively new tool that has been around for a few months and comes with a liquidity feature.
On Lendermarket it used to be like this: once you had invested in a loan, you were tied to its term. We did have very high interest rates on the long-term loans, but you did not really have much liquidity. That is exactly what Auto Invest FLEX is for.
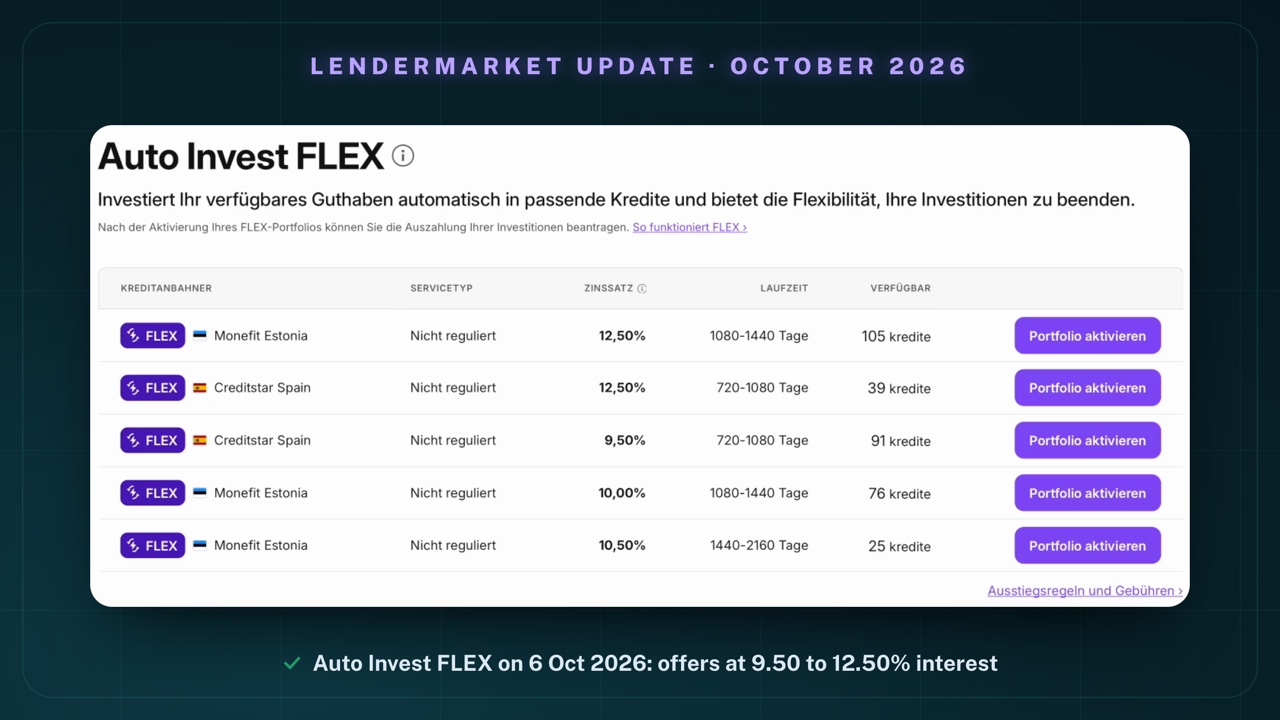
We still have the long terms – with the current offers partly 1,440 days and more, so extremely long. But you do have this flex option. One sentence in particular is decisive here:
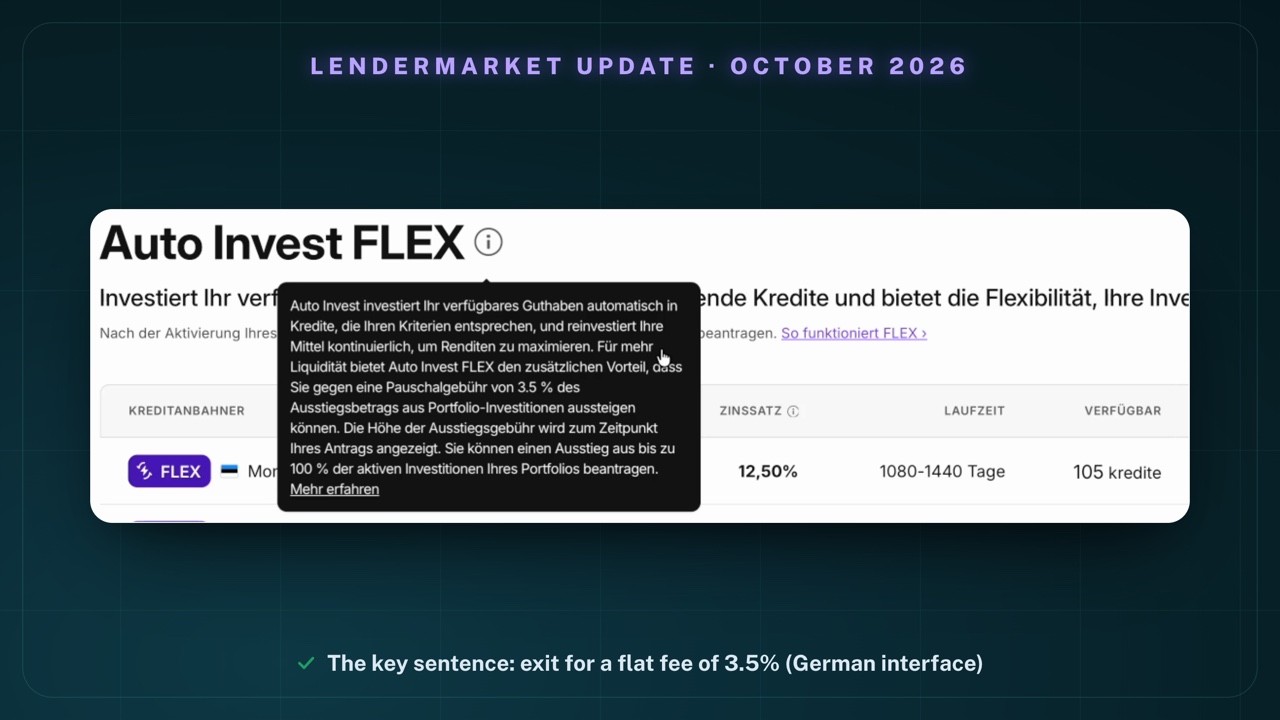
Translated from my German account: for more liquidity, Auto Invest FLEX offers the additional benefit that you can exit portfolio investments for a flat fee of 3.5% of the exit amount.
What the exit looks like
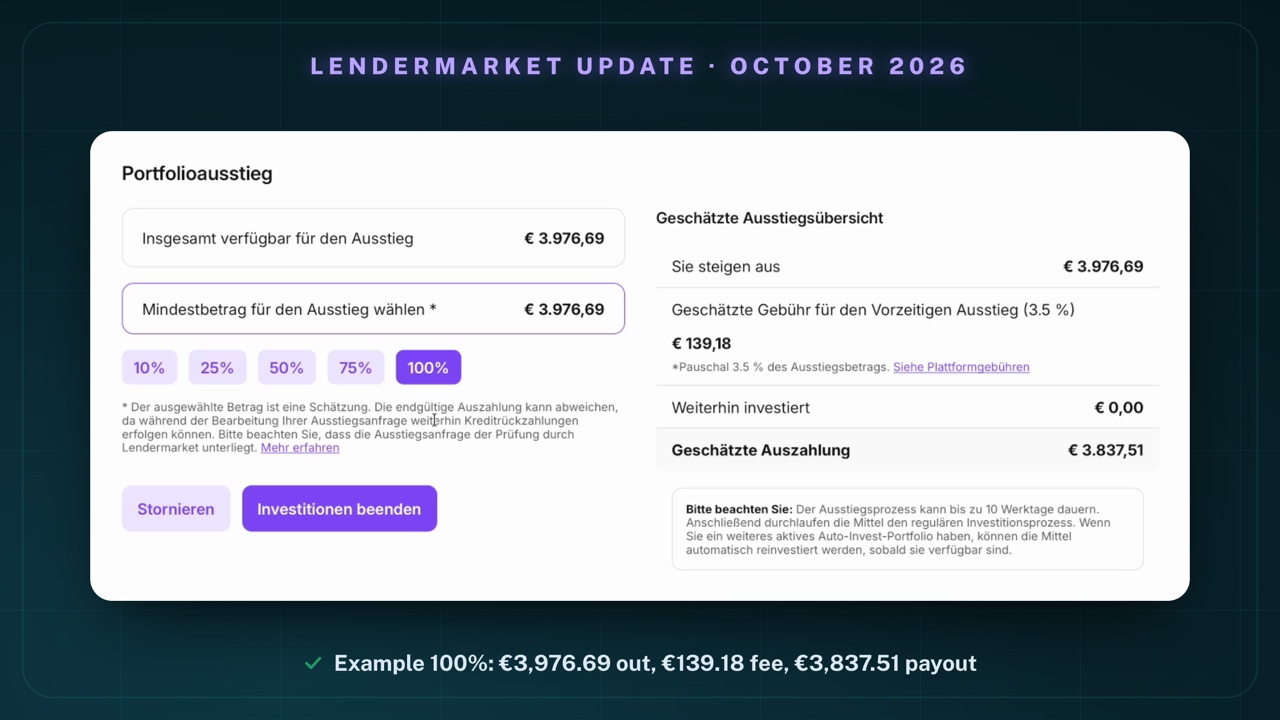
This means: if I want out of one of my portfolios – here, for example, the one with €3,976.69 – I click on “Portfolioausstieg” (portfolio exit) and can then say how much I want paid out: 10%, 25%, 50%, 75% or 100%. You cannot enter your own amount; you always have to choose one of these options. And then I immediately see what the fee for the early exit is.
If I only need a little money, I could pay out 10%, for example – then I only have an exit fee of just under €14:
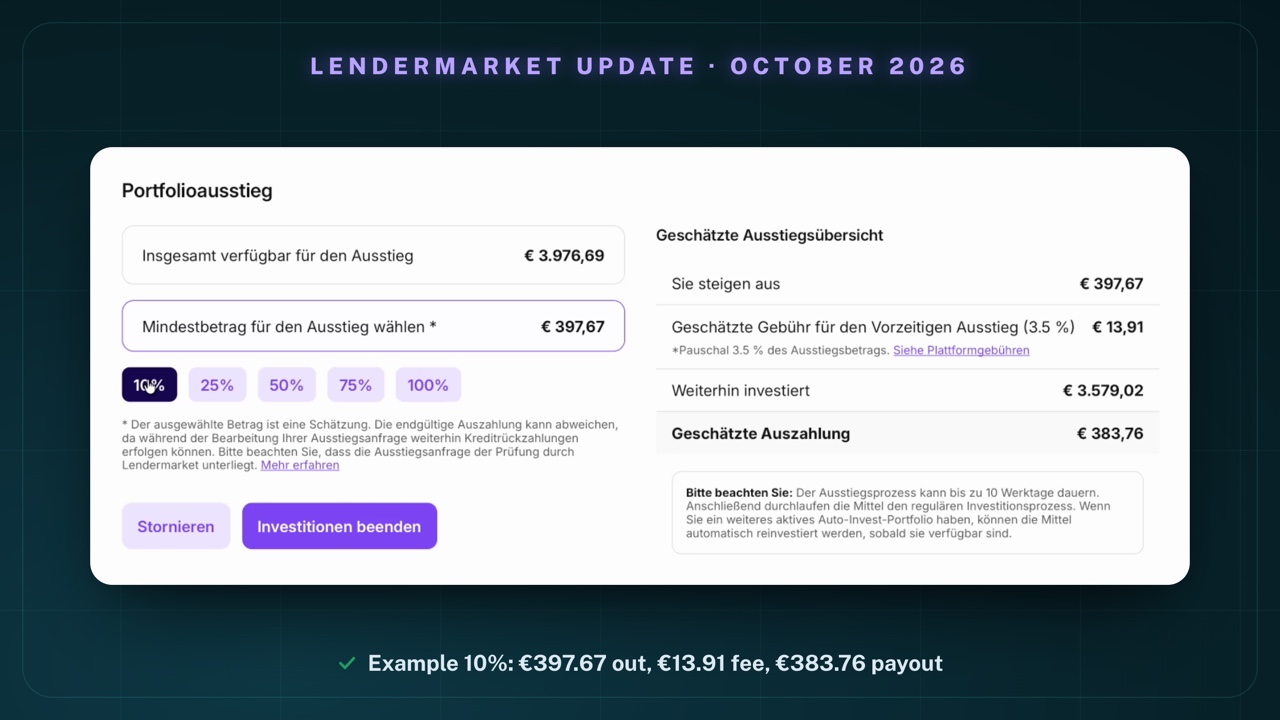
But if I do need everything at once, I can also go to 100%:
| Exit | Amount | Fee (3.5%) | Estimated payout |
|---|---|---|---|
| 10% | €397.67 | €13.91 | €383.76 |
| 100% | €3,976.69 | €139.18 | €3,837.51 |
I did not trigger the exit – these are the figures my account showed me on the day of the recording.
Advantage and disadvantage
So we still have these relatively high interest rates here, for example the 12.5%. But on a yearly basis we only get them in full if we stay in for the term. If we want to exit earlier, we always have to pay this exit fee of 3.5% of the exit amount.
- The advantage: we can still earn high interest, especially if we do not exit – and still have the option of exiting for a fee.
- The disadvantage: exactly this fee. If we enter today and already want to pull our money out next month, we still have to pay the 3.5% and can then actually end up with a loss.
So it makes less sense if you really do not know whether you will need the money next month or not. It makes more sense if you actually want to invest for the long term but would like a liquidity feature – an exit option in case something does come up at some point.
What also has to be said: these are still loan investments, and nothing can ever be fully guaranteed. We can still lose our money. And the exit process can, as it says in the account, take up to 10 business days – you should definitely keep that in mind. In the video I say that you can exit the portfolio at any time. Strictly speaking, you can request the exit at any time: the request is subject to review by Lendermarket, and according to Lendermarket there is no guaranteed right to a payout.
My four portfolios
I have created four different pots in Auto Invest FLEX:
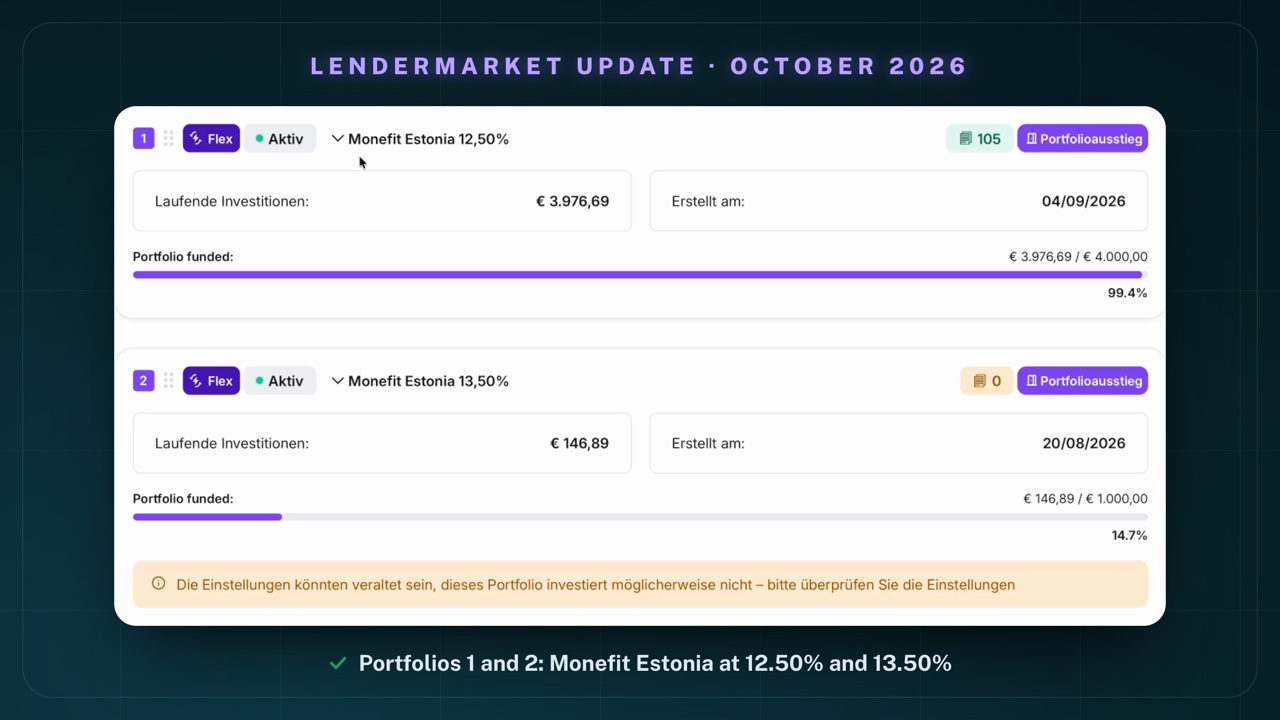
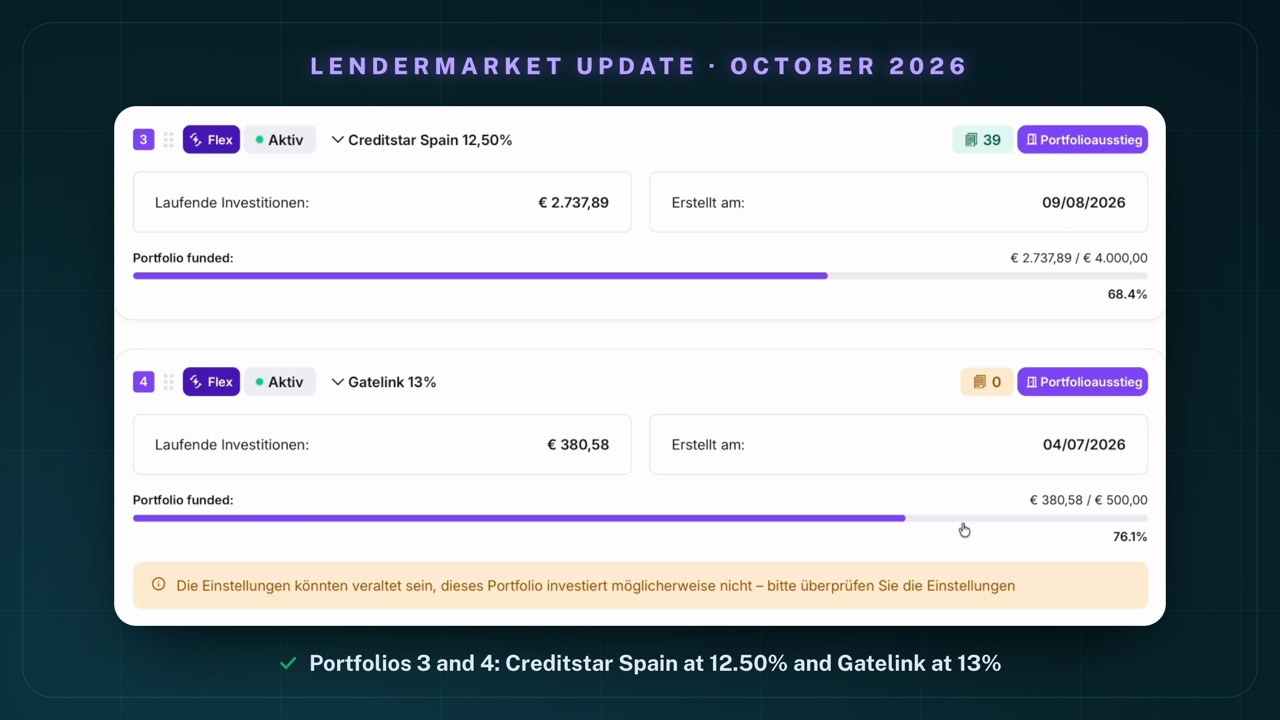
| Portfolio | Interest rate | Invested |
|---|---|---|
| Monefit Estonia | 12.50% | €3,976.69 |
| Monefit Estonia | 13.50% | €146.89 |
| Creditstar Spain | 12.50% | €2,737.89 |
| Gatelink | 13% | €380.58 |
The two small pots at 13.5% and 13% really are only around €150 and €380. Together the four portfolios hold €7,242.05; the rest are older positions. This is what my largest portfolio looks like in detail:
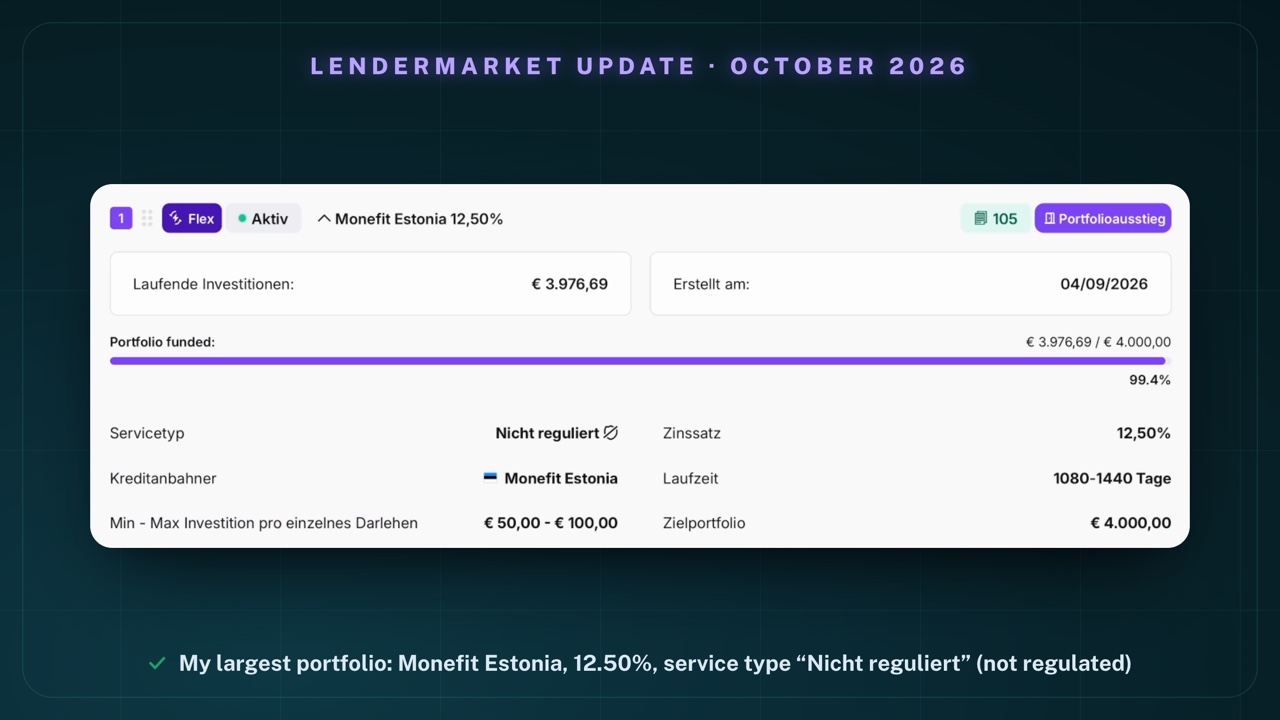
I definitely have a long-term investment horizon here. But you do have the option of exiting early if you need to get at the money.
How safe is Lendermarket?
€10,000 is my upper limit for regulated platforms – and Lendermarket is regulated, which of course brings some advantages over unregulated platforms. Strictly speaking, though, that only applies to part of the offering:
- Authorisation. Lendermarket Limited from Dublin has been authorised by the Central Bank of Ireland as a crowdfunding service provider since December 2024.
- Not everything is regulated. In its footer Lendermarket itself states that it provides both services that fall under the EU Crowdfunding Regulation and services that are not covered by it. The FLEX offers above and my largest portfolio carry the service type “Nicht reguliert” (not regulated).
- Buyback only by the loan originator. According to Lendermarket, the buyback guarantee is a contractual obligation of the loan originator and depends on its financial capacity.
- No deposit guarantee. Lendermarket itself points out that the investment is covered neither by a deposit guarantee scheme nor by an investor compensation scheme.
Nevertheless, you always have to be aware of the risks here too: where there are loan investments, there are default risks. We can see in my account as well that there are a few late loans. That is completely normal. What matters is how it is handled – whether the buyback obligation kicks in, whether debt collection works well and how long we wait for our money. So far everything has gone very smoothly for me.
Who is Lendermarket for?
- want to invest for the long term and are looking for interest rates around 12.5%
- want everything to run automatically through an auto-invest portfolio
- value an exit option for a fee in case something does come up
- want to take the 1.5% cashback in the first 90 days as a new customer
- already know you will need the money again in a few weeks – then the 3.5% exit fee eats up the return
- only want to invest in regulated loans – the offers in Auto Invest FLEX are labelled “not regulated”
- expect a deposit guarantee or a guaranteed exit
- want to invest money you could not afford to lose
My plan and conclusion
So much for my investment on Lendermarket. It is definitely working, and I will keep topping up: I will add €2,000 one more time, but then that is it for me for now – €10,000 is my upper limit.
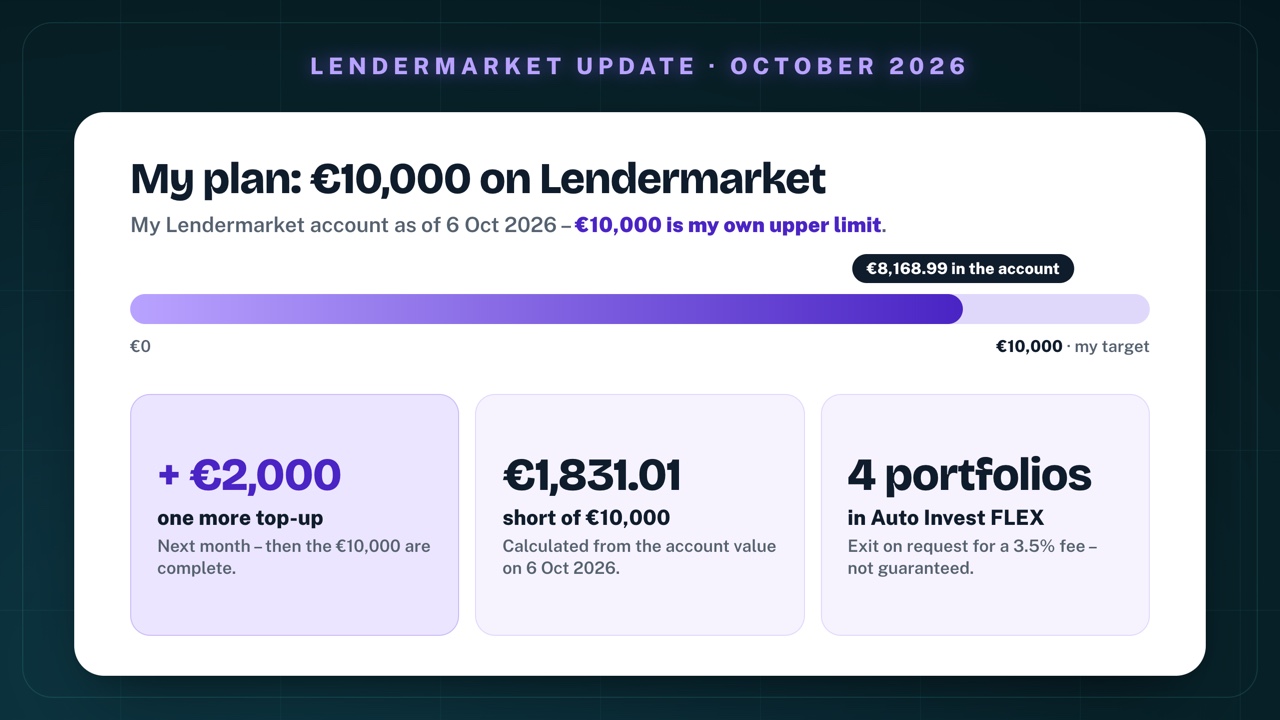
I will keep you posted on how things go with the late loans. You can see how Lendermarket fits into my overall P2P portfolio in the P2P Portfolio Update October 2026.
If you want to try Lendermarket yourself, feel free to use my link for the cashback: go to Lendermarket through my link*.
Now I'm curious: what is your opinion of Lendermarket? Are you invested there, and are you already using the new liquidity feature? Feel free to write it in the comments under the video.
Links marked with * are partner links. If you invest through them, you support my work – at no extra cost to you. Thank you!
LENDERMARKET DISCLAIMER “Lendermarket Limited, trading as Lendermarket, is regulated by the Central Bank of Ireland.”
WARNING: Investment in crowdfunding projects entails risks, including the risk of partial or entire loss of the money invested. Your investment is not covered by a deposit guarantee scheme or by an investor compensation scheme.
WARNING: Past performance is not a reliable guide to future performance.
WARNING: These figures are estimates only. They are not a reliable guide to the future performance of this investment.
WARNING: This product may be affected by changes in currency exchange rates.
“Before investing, please read the Key Investment Information Sheet (KIIS) for this project.”
“This project involves investment risk, including the risk of losing your entire investment. Returns are not guaranteed.”
“The information on this page relates to regulated crowdfunding services provided under Regulation (EU) 2020/1503. Other services offered by Lendermarket are not regulated under this framework.”
“The content on this page relates to services that are not regulated by the Central Bank of Ireland.”
“Warning: Investing involves risk of loss. Not covered by guarantee or compensation schemes.”
“This is a paid promotion. Investing involves risk, including the risk of losing your money.”
Frequently asked questions
How much has Lennard invested on Lendermarket?
As of 6 October 2026 I have deposited €8,000 on Lendermarket. The account value is €8,168.99, of which €8,156.23 is invested and €11.50 is idle. Next month I will add another €2,000 – then I will have reached the €10,000 I set as my target.
How much interest has Lennard earned on Lendermarket so far?
My dashboard shows a profit of €168.49: €108.45 interest, €60.00 campaign rewards and bonuses, and €0.04 late interest. My average interest rate is 12.29%. By month: June €6.53, July €12.10, August €76.56, September €44.36 and, up to 6 October, already €28.94. These are figures from my account, not a guarantee for the future.
What cashback is available on Lendermarket?
Through my referral link (finlen.de/lendermarket), new customers get 1.5% cashback on all investments in the first 90 days. This is my partner condition (as of 6 October 2026) – it is not listed on the Lendermarket website itself.
What is Auto Invest FLEX on Lendermarket?
Auto Invest FLEX automatically invests your available balance in matching loans and additionally lets you request an exit from the portfolio. A flat fee of 3.5% of the exit amount applies. You can choose 10, 25, 50, 75 or 100% of the portfolio. The request is subject to review by Lendermarket, and according to Lendermarket there is no guaranteed right to a payout.
What does an early exit from Auto Invest FLEX cost?
A flat 3.5% of the exit amount. In my account on 6 October 2026: for 10% of my largest portfolio (€397.67) the fee would be €13.91 and the estimated payout €383.76. For 100% (€3,976.69) it would be a €139.18 fee and a €3,837.51 payout. If you exit shortly after entering, you can end up with a loss.
How long does an exit from Auto Invest FLEX take?
My account states that the exit process can take up to 10 business days. The amounts shown are estimates; the final payout may differ.
Does Lennard have late loans on Lendermarket?
Yes. On 6 October 2026, out of €8,156.23 of invested funds, €77.95 was 1–15 days late and €56.73 was 16–30 days late. Nothing was more than 30 days late. I never have more than €100 in a single loan.
Is Lendermarket regulated?
Partly. Lendermarket Limited from Dublin has been authorised by the Central Bank of Ireland as a crowdfunding service provider since December 2024. However, only part of the offering is regulated: Lendermarket also provides services that do not fall under the EU Crowdfunding Regulation. The offers in Auto Invest FLEX that I use are mostly labelled with the service type “Nicht reguliert” (not regulated) in my account. There is no deposit guarantee scheme and no investor compensation scheme.
Disclaimer
⚠️ Not investment advice
All content is for information and entertainment purposes only and does not constitute investment advice, a buy recommendation or an invitation to enter into a financial product. Please do your own research and make decisions based on your personal situation and risk tolerance.
📉 Risk warning & total loss
Investments in securities and other financial instruments generally carry significant risks (e.g. price, market, currency, volatility and credit risks). A total loss of the capital invested cannot be ruled out.
📊 Returns & forecasts
All performance figures, whether historical or as a forecast/estimate, are not a reliable indicator of future results. Capital and returns are not guaranteed.
🔍 Transparency & conflicts of interest
I strictly distinguish between facts and personal estimates. Important: I am often invested in the assets discussed myself, which can create a conflict of interest.
✅ DYOR (Do Your Own Research)
All information has been compiled carefully but is non-binding, without warranty and without any claim to completeness. Please inform yourself thoroughly and consider all opportunities and risks in depth before making an investment decision.
Advertising & affiliate notice
Links marked with * are advertising or affiliate links. If you sign up or buy something through such a link, I may receive a commission – at no extra cost to you. This supports my work.