Loanch Update October 2026: €4,321 in My Account, 14.5% Interest & Why Auto-Invest Is a Must
My Loanch update for October: my account stands at €4,321.86, of which €174.15 is profit and €37.71 rewards. I show you my portfolio of short-term Tambadana loans at 14.5%, my exact auto-invest settings, which bonus still runs after the Early Bird promotion (€20 new-customer bonus and 1% cashback – with all the conditions), how far I am from the Bronze tier and why I stop at €5,000. Plus the honest part: no regulation, no secondary market and the payment disruption in spring.
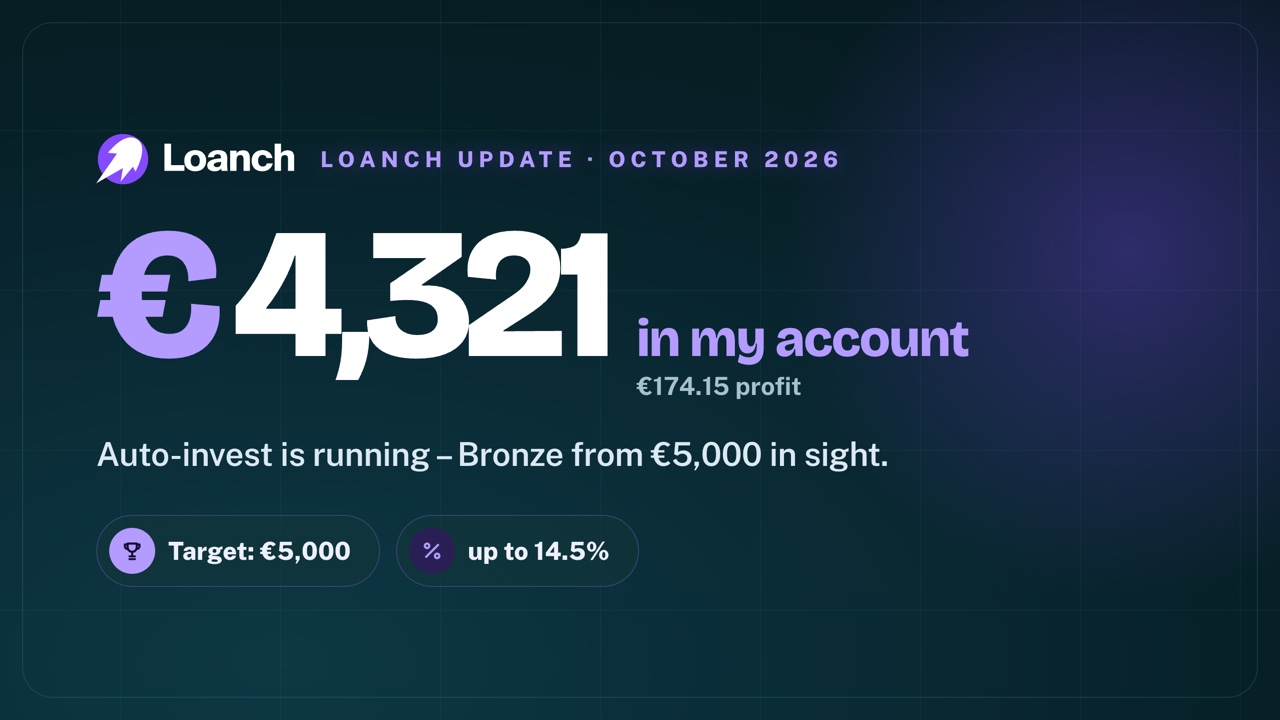
Table of contents
- My Loanch account in numbers
- What is Loanch, actually?
- Video
- New-customer bonus and cashback: what's running right now
- The loyalty programme: Iron threshold reached, Bronze in sight
- My portfolio: short-term Tambadana loans at 14.5%
- Auto-invest is a must – my settings
- The account statement: several repayments every day
- How safe is Loanch?
- Is Loanch worth it?
- My plan and verdict
- FAQ
Time for a short Loanch update. On the Croatian P2P platform I am now invested with more than €4,300 – I have just topped up again. In this post we look at my investment in detail: how it is going so far, what you need to watch out for with Loanch, which bonus still runs now that the Early Bird campaign has ended – and why €5,000 is where I stop for now.
As always, the most important thing first: this is not investment advice and not a recommendation to buy, just my personal opinion and experience. P2P loans are high-risk – only invest money you could afford to lose entirely, and make your own decisions. The Loanch link is a referral link: if you use it, I receive a small commission, at no extra cost to you.
My Loanch account in numbers
My account currently stands at €4,321.86 (as recorded on 4 October 2026). In the September update it was still €3,800.88.
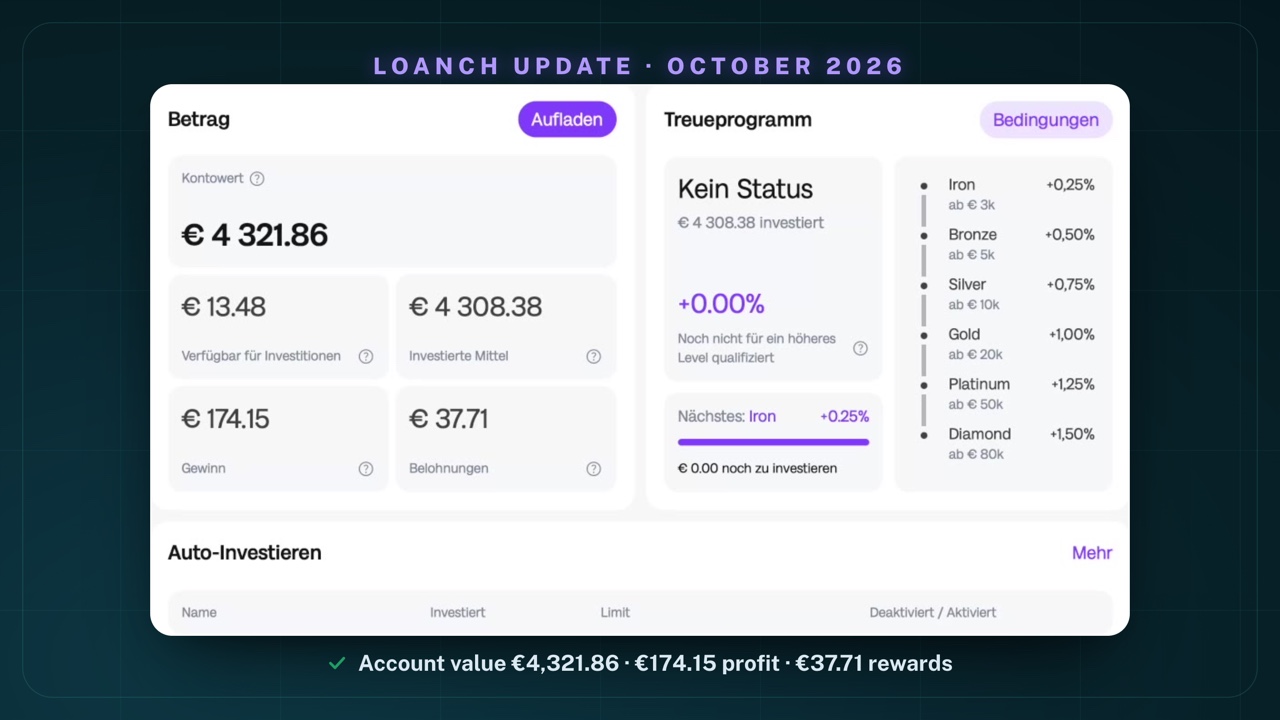
The numbers in detail:
- Account value: €4,321.86
- Invested funds: €4,308.38 – €13.48 was available at the moment of recording and was reinvested shortly afterwards
- Profit: €174.15
- Rewards: €37.71 from cashback and bonus promotions
A small clarification on the video: there I say I have "€4,321.86 invested". Strictly speaking that is the account value – €4,308.38 is in loans, the rest had just flowed back. It doesn't change the point: this is really starting to add up.
What is Loanch, actually?
Loanch is a P2P platform through which you invest in consumer loans – mainly from Malaysia. The operator is PRZEMEK SAVJETOVANJE d.o.o., based in Zagreb, Croatia. The key facts from the homepage (retrieved on 5 October 2026):
- up to 14.5% APR from consumer loans – currently the highest rate on the platform
- €20 bonus for your first investment
- buyback after 30 days overdue
- 0% fees
- a loyalty programme with up to 1.5% extra interest
The platform in numbers, according to Loanch: around €123.4 million invested in total, 16.4 thousand registered investors and €2 million in interest paid out. Three originators stand behind the loans: Tambadana (Wawasan Cojaya Sdn. Bhd., Kuala Lumpur; avg. 13.82% interest), AhaPay (avg. 11.00%) and Ammana (avg. 13.29%) – for Ammana, new loans are temporarily unavailable according to Loanch.
Video: Loanch Update October 2026: €4,321 in My Account, 14.5% Interest & Why Auto-Invest Is a Must
The full update is also available as a video – I walk through my Loanch account, my investments, the auto-invest and the account statement live. Feel free to watch, or read on below.
New-customer bonus and cashback: what's running right now
The Early Bird cashback promotion from the last update ended on 30 September. But there are still two things you can secure as a new customer:
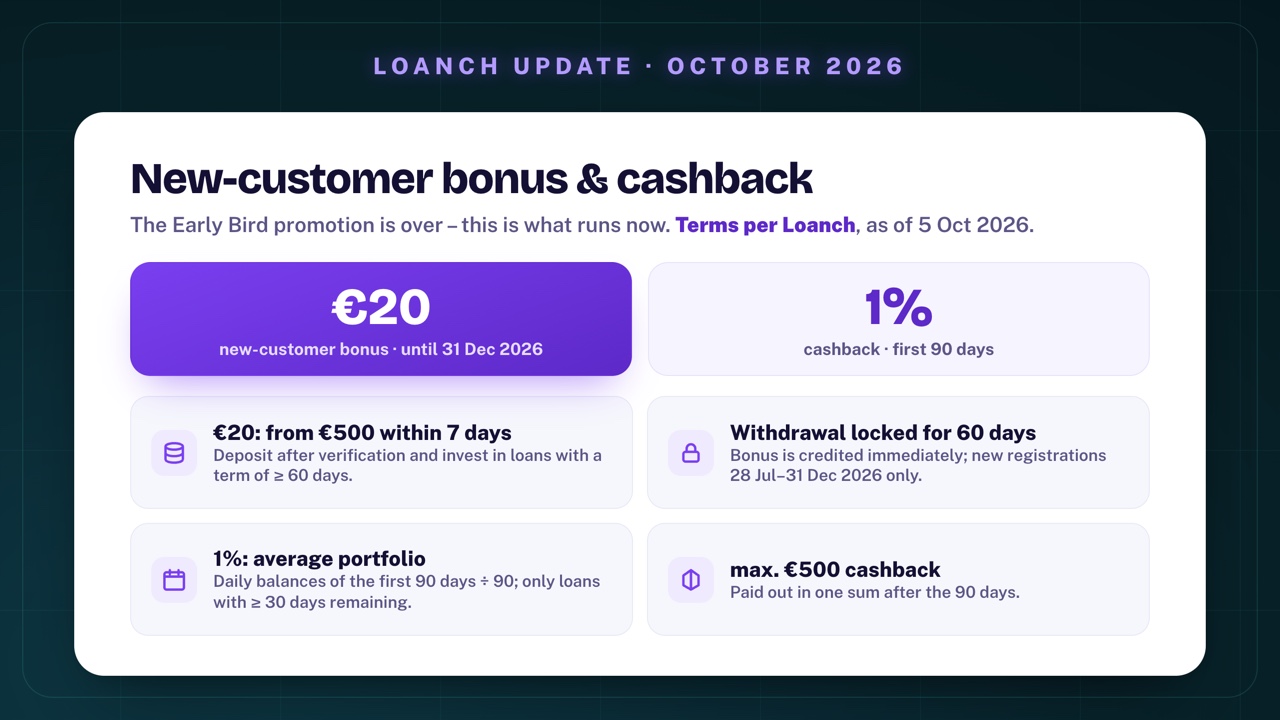
1. €20 new-customer bonus – until the end of the year. In the video I only mention the amount; here are the conditions as published by Loanch:
- registration between 28 July and 31 December 2026
- deposit and invest at least €500 – within 7 days of completing verification
- in loans with a term of at least 60 days
- the bonus is credited immediately; withdrawing it is locked for 60 days
2. 1% cashback in the first 90 days. On top of that, there is 1% cashback via my Loanch link*. In the video I say "on all your investments in the first 90 days" – that is the short version. According to the terms of Loanch's referral programme the calculation is more precise:
- 1% of your average daily portfolio over the first 90 days (the sum of the 90 daily balances divided by 90)
- only investments with at least 30 days remaining count
- capped at €500, paid out in one sum after the 90 days
In practice: whoever invests early and in full gets the most. If you only deposit on day 60, you don't get 1% on that amount, just the pro-rata average. Always check the current terms directly with Loanch before you start.
For transparency: this is a referral link. If you sign up through it, I receive a small commission – at no extra cost to you.
The loyalty programme: Iron threshold reached, Bronze in sight
Loanch's loyalty programme rewards larger portfolios with an interest top-up. You can see the six tiers in the dashboard screenshot above:
- Iron from €3,000 – +0.25%
- Bronze from €5,000 – +0.50%
- Silver from €10,000 – +0.75%
- Gold from €20,000 – +1.00%
- Platinum from €50,000 – +1.25%
- Diamond from €80,000 – +1.50%
In the video I say I have "reached the Iron tier". More precisely: I have passed the threshold of €3,000 – but the dashboard still shows "No status" and +0.00%. The reason: you have to hold the threshold for 90 days; only then does Loanch grant the tier. By my count I have been above it for around two months now, so there is still a bit to go. And importantly: the extra interest then only applies to new investments made after the tier is granted.
Bronze is the tier I am working towards – I will probably reach the €5,000 next month or the month after. I could imagine Silver at some point in the medium term. But it won't be more than that for me on Loanch; I will certainly not reach Diamond here – even though 1.5% extra return is quite something.
My portfolio: short-term Tambadana loans at 14.5%
"My investments" shows what I go for: short-term loans.
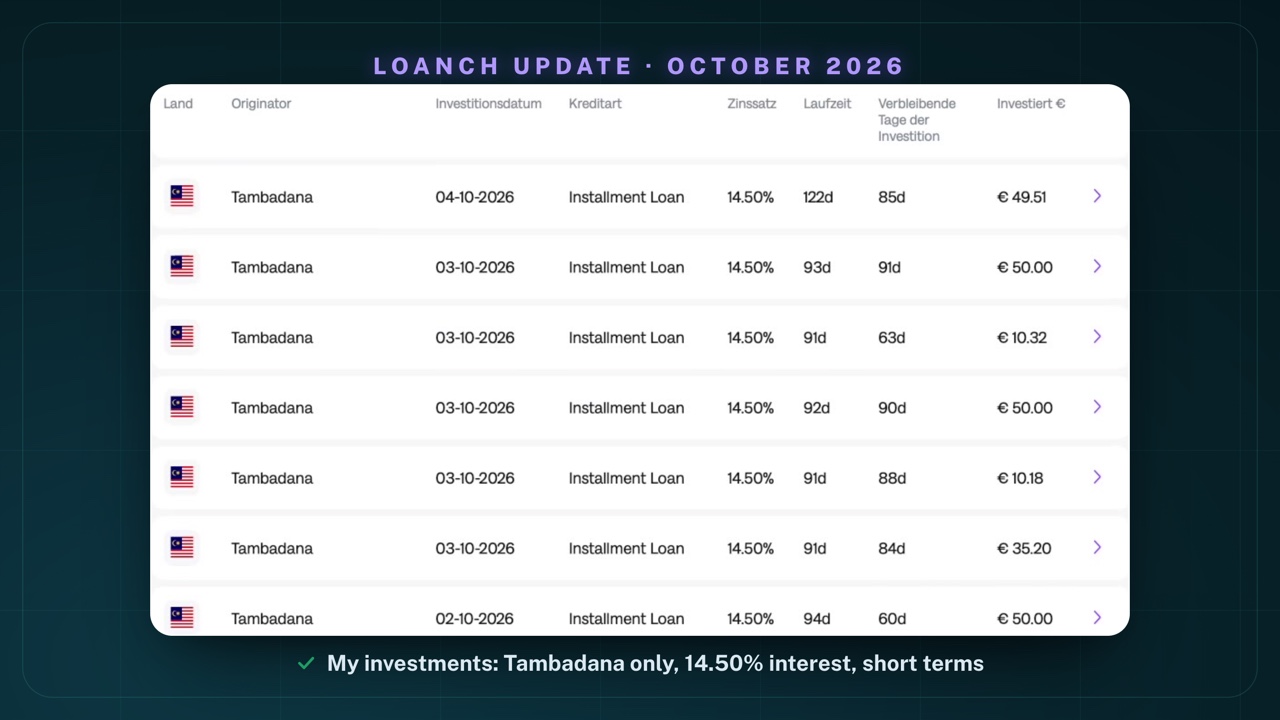
- Originator: exclusively Tambadana – I really only do Tambadana loans
- Interest rate: 14.50% throughout
- Term: the longest term visible in my list is 122 days, so around four months (in the video I estimate "120 days"). The remaining term is shown in the column next to it.
- Ticket size: many small packages between roughly €10 and €50
That spreads me across a very large number of individual loans – every few days something comes back, or the buyback obligation kicks in and the loan is repaid. To be honest about it: I am widely spread across loans, not across originators. If Tambadana fails, spreading across many loan packages won't help me.
Auto-invest is a must – my settings
I really do say this every time: set up an auto-invest on Loanch. You can also invest manually and pick the loan packages yourself – but look at the page count at the bottom:
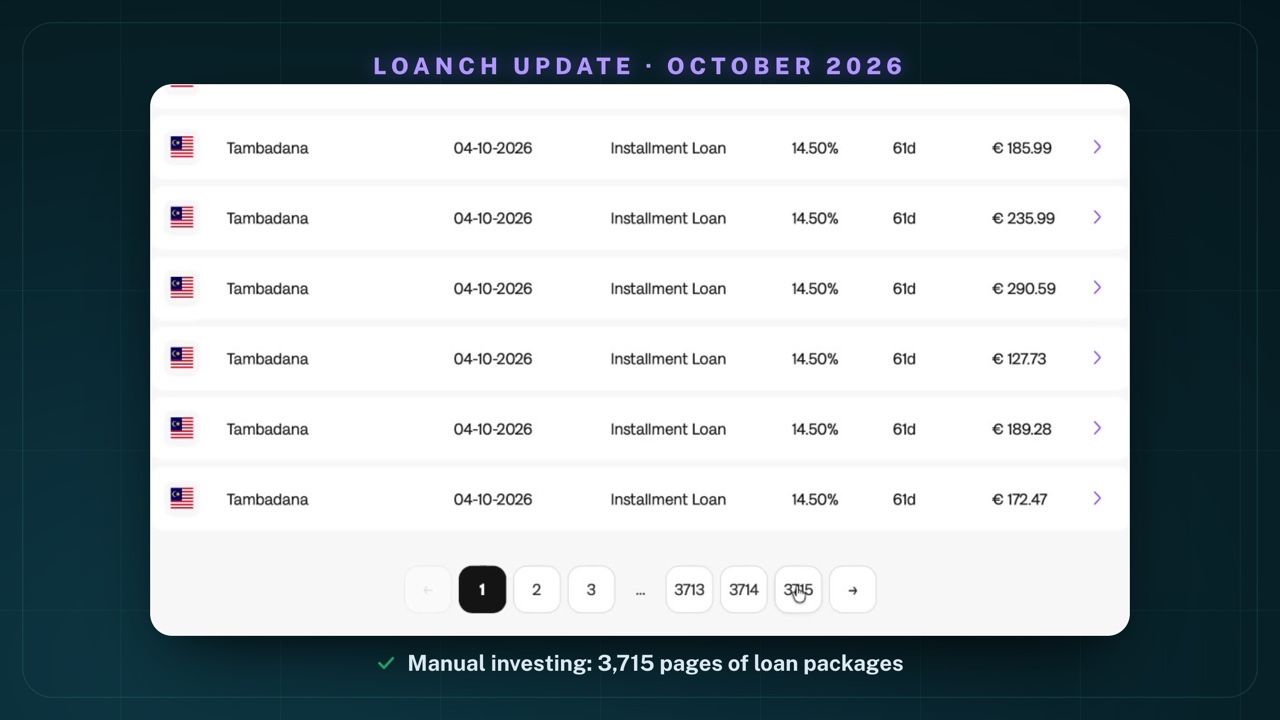
3,715 pages of loan packages. Going through that by hand makes no sense – especially as repayments and buybacks keep coming in and need to be reinvested.
You find the auto-invest on the left under "Automatische Investition" (automatic investment). There are predefined strategies ("Go Long" and "Go short"); I recommend creating your own strategy, though – it keeps you more flexible. Mine looks like this:
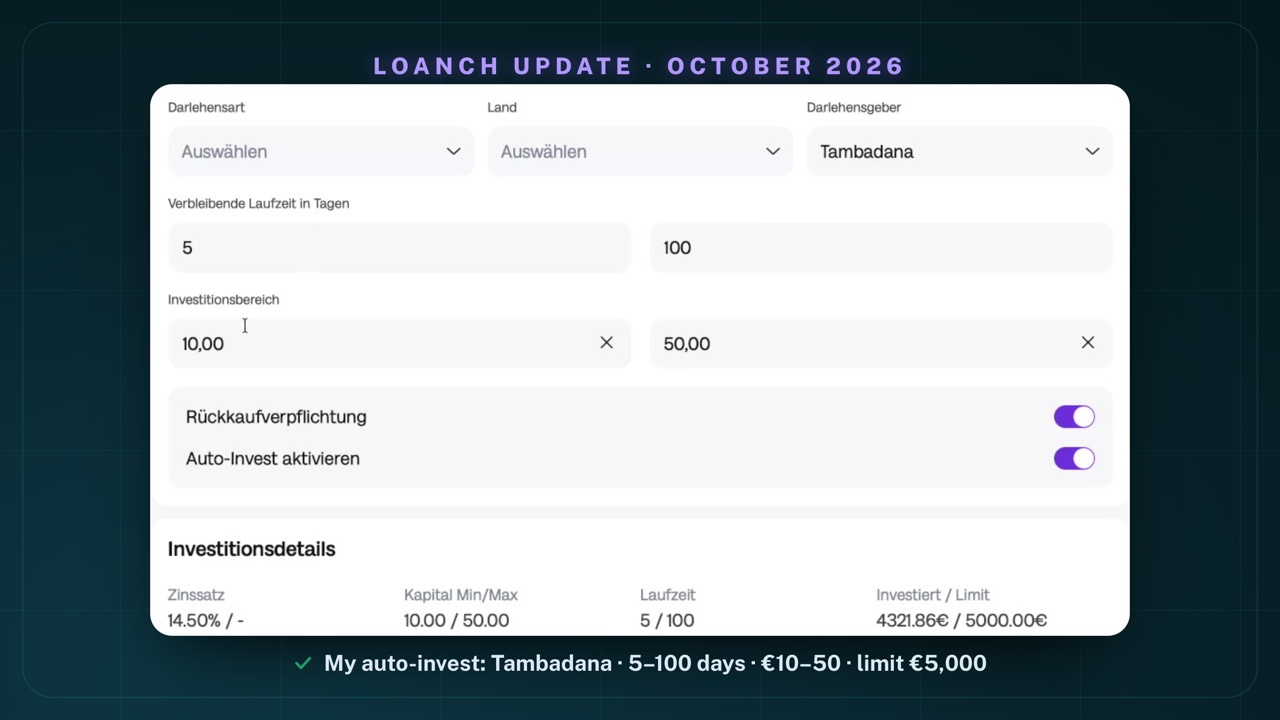
- Strategy limit: €5,000
- Minimum interest: 14.5%
- Originator: Tambadana
- Remaining term: 5 to 100 days – that is how I have had it set for a week or two
- Amount per loan package: €10 to €50
- Buyback obligation: on – only loans with a buyback obligation
With these criteria, 26,032 loans qualified at the time of recording – so the auto-invest runs without any problem. As a test I set the minimum interest to 15%: then not a single loan matches. 14.5% is currently the highest there is on Loanch. It fluctuates occasionally and sometimes there are higher rates – but if you set your minimum too high, your money simply sits idle.
The account statement: several repayments every day
How often does something actually come back? The account statement shows it well:
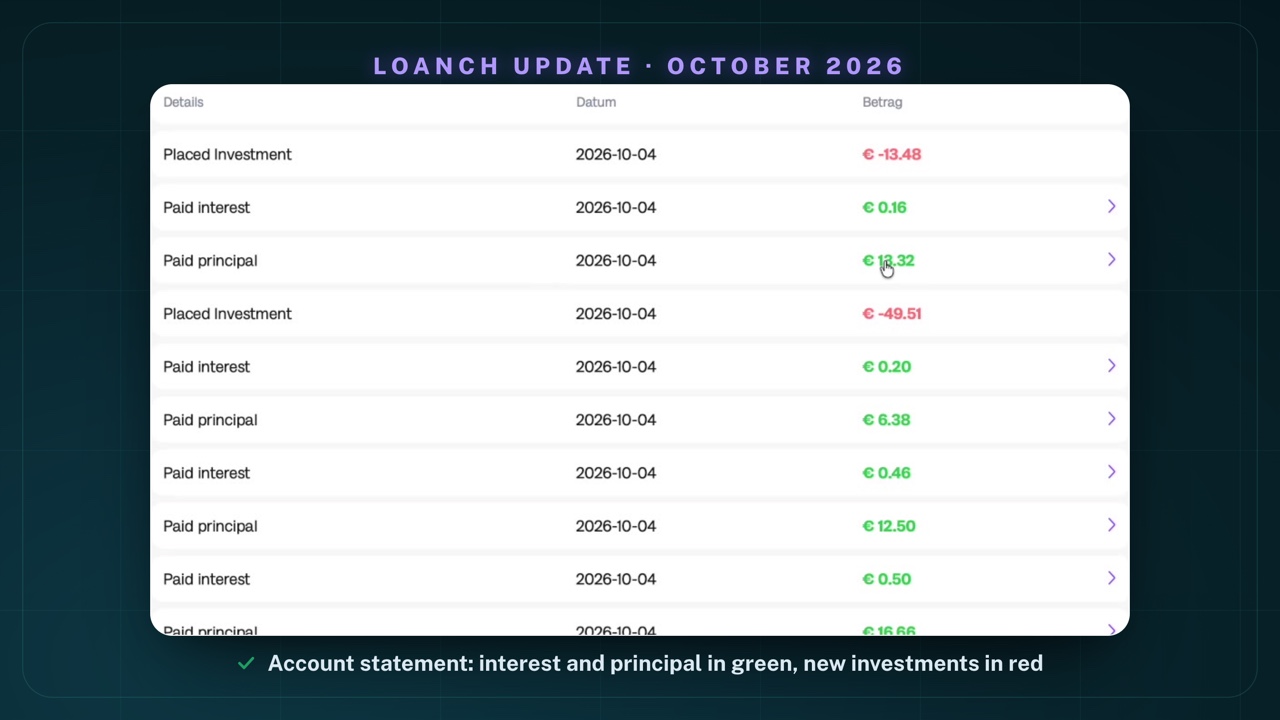
On 4 October alone there are several "Paid interest" and "Paid principal" entries – all in green. The red rows are "Placed Investment": that is the auto-invest putting the returned money straight back into a new package. This really happens several times a day. That is exactly why I consider auto-invest a must – without it you would constantly have money sitting around earning nothing.
How safe is Loanch?
Now for the honest part – because for all that is going well, Loanch has clear weaknesses:
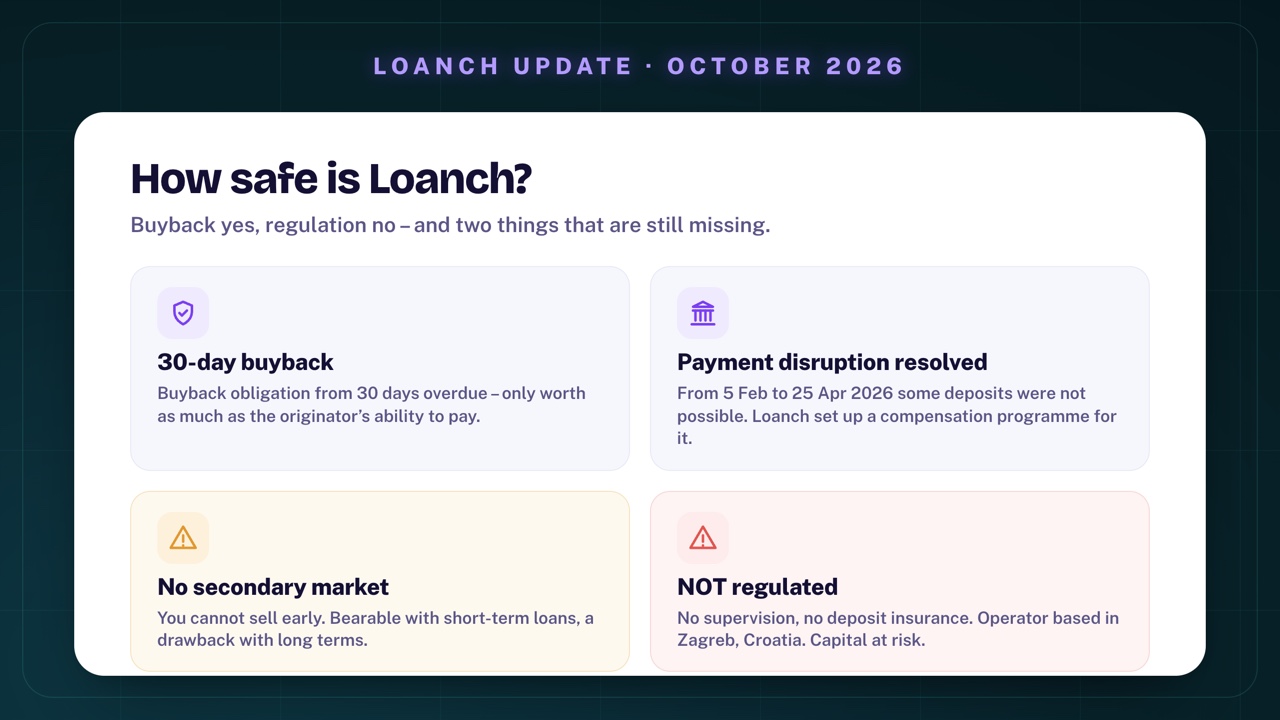
Loanch is not regulated. The platform says so itself in its footer: the services are expressly not offered to residents of jurisdictions where local authorisation or a licence would be required. There is no financial supervision of the platform and no deposit insurance. It would be good to see regulation being pursued and implemented – that would be an additional layer of safety.
There is no secondary market. You cannot sell loans early. With my short-term loans that is not a big issue, but with long terms that option is noticeably missing.
The payment disruption in spring has been resolved. According to Loanch, certain deposit methods were temporarily unavailable between 5 February and 25 April 2026 because of an issue at the payment service provider – at times you couldn't deposit new money. Loanch set up a compensation programme for it and now speaks of licensed payment service providers in the plural; in my view they have learned from it. (In the September update I described the period as "December to February" – Loanch's own information supports today's version.)
The buyback obligation applies after 30 days overdue. But it is only worth as much as the originator's ability to pay – in the end the default risk is yours.
Who is Loanch worth it for?
- want up to 14.5% interest from consumer loans
- prefer short terms and let auto-invest do the work
- value the 30-day buyback obligation and 0% fees
- want to pick up the €20 bonus as a new customer
- need a regulated platform with real deposit insurance
- want to be able to sell loans early on a secondary market
- can't bear the default risk of Malaysian consumer loans
- want to spread across many originators – I am invested in Tambadana only
My plan and verdict
I have been very happy with Loanch so far, which is why I keep topping up – but only to €5,000:
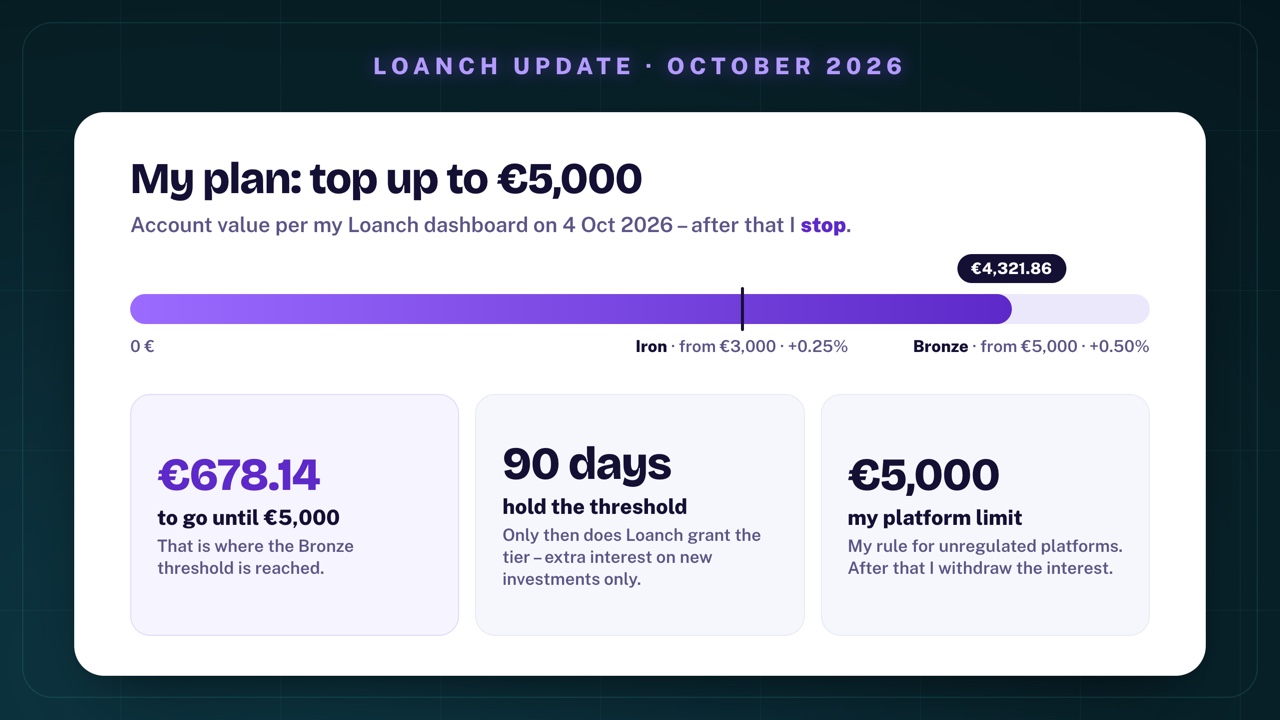
That leaves €678.14 to go. With that I will have reached the threshold for the next loyalty tier and – after the 90 days – get a bit of extra return on new investments.
But that is where it ends: for unregulated platforms I currently set myself a limit of €5,000 per platform. After that I will withdraw the interest and invest it elsewhere – on other platforms or in stocks. I want to shift the focus a bit more towards stocks in future anyway, because my P2P share is currently above 20%, which carries a certain risk. You can see how Loanch fits into my overall P2P portfolio in the P2P portfolio update October 2026.
Bottom line: Loanch is going very well for me right now: 14.5% interest, an auto-invest that reinvests daily, and a loyalty programme that adds a little on top. The risks remain – no regulation, no deposit insurance, no secondary market, capital at risk – and that is exactly why it stays a clearly limited position. If you want to try Loanch, it's best to grab the new-customer bonus right away: go to Loanch via my link*.
What is your take on Loanch? Have you tried the platform, which originators do you use – do you also go for the short-term Tambadana loans? Let me know in the comments under the video.
Links marked with * are partner links. If you invest through them, you support my work – at no extra cost to you. Thank you!
Frequently asked questions
How much has Lennard invested in Loanch?
As of 4 October 2026 my Loanch account stands at €4,321.86. Of that, €4,308.38 is invested in loans and €13.48 is available. So far I have received €174.15 in profit plus €37.71 in rewards from bonus and cashback promotions. My target is €5,000 – I won't invest more than that in Loanch for now.
Is Loanch regulated?
No. Loanch says so itself in its footer: the services provided through the platform are not offered to residents of jurisdictions where such services require local authorisation or licensing. The operator is PRZEMEK SAVJETOVANJE d.o.o., based in Zagreb, Croatia. There is no financial supervision of the platform and no deposit insurance – your capital is at risk.
How high is the interest on Loanch?
Loanch advertises up to 14.5% APR from consumer loans – currently the highest rate on the platform, and every loan in my portfolio runs at 14.5%. Depending on the originator, the average rate according to Loanch is 13.82% (Tambadana), 13.29% (Ammana) and 11.00% (AhaPay). The loyalty programme adds up to 1.5 percentage points depending on portfolio size. Interest is not guaranteed.
Which bonus is currently available on Loanch?
The Early Bird cashback promotion ended on 30 September 2026. Currently new customers get a €20 bonus on their first investment: you need to register between 28 July and 31 December 2026 and, within 7 days of completing verification, deposit at least €500 and invest it in loans with a term of at least 60 days. The bonus is credited immediately; withdrawing it is locked for 60 days. On top of that there is 1% cashback in the first 90 days – calculated on your average daily portfolio, capped at €500. Always check the terms directly with Loanch.
How does the Loanch loyalty programme work?
The loyalty programme has six tiers based on your invested portfolio: Iron from €3,000 (+0.25%), Bronze from €5,000 (+0.50%), Silver from €10,000 (+0.75%), Gold from €20,000 (+1.00%), Platinum from €50,000 (+1.25%) and Diamond from €80,000 (+1.50%). You have to hold the threshold for 90 days, then the tier is granted. The extra interest only applies to new investments made after the tier is granted.
Should you invest manually on Loanch or use auto-invest?
I use auto-invest exclusively. When I recorded the video, the primary market had 3,715 pages of loan packages, and interest and principal come back into my account several times a day – reinvesting that by hand is not practical. My settings: originator Tambadana, at least 14.5% interest, 5 to 100 days remaining term, €10 to €50 per loan, buyback obligation only, limit €5,000.
Does Loanch have a secondary market?
No, not at the moment. You cannot sell loans early; you have to wait for maturity or the buyback. With short terms that is bearable, with long terms it is a real drawback. That is why I stick to loans with at most 100 days remaining.
What about the payment problems at Loanch?
According to Loanch, certain deposit methods were temporarily unavailable between 5 February and 25 April 2026 because of an issue at the payment service provider. This has been fixed; Loanch set up a compensation programme for affected investors and now speaks of several licensed payment service providers.
Disclaimer
⚠️ Not investment advice
All content is for information and entertainment purposes only and does not constitute investment advice, a buy recommendation or an invitation to enter into a financial product. Please do your own research and make decisions based on your personal situation and risk tolerance.
📉 Risk warning & total loss
Investments in securities and other financial instruments generally carry significant risks (e.g. price, market, currency, volatility and credit risks). A total loss of the capital invested cannot be ruled out.
📊 Returns & forecasts
All performance figures, whether historical or as a forecast/estimate, are not a reliable indicator of future results. Capital and returns are not guaranteed.
🔍 Transparency & conflicts of interest
I strictly distinguish between facts and personal estimates. Important: I am often invested in the assets discussed myself, which can create a conflict of interest.
✅ DYOR (Do Your Own Research)
All information has been compiled carefully but is non-binding, without warranty and without any claim to completeness. Please inform yourself thoroughly and consider all opportunities and risks in depth before making an investment decision.
Advertising & affiliate notice
Links marked with * are advertising or affiliate links. If you sign up or buy something through such a link, I may receive a commission – at no extra cost to you. This supports my work.