€501,529 Net Worth: My Portfolio Update for October 2026
A transparent net worth update for October 2026: my portfolio cracks the half-million mark and stands at €501,529 – up 4.58% on the previous month and 62.70% since the start of the year. All seven asset classes, from stocks and P2P to crypto, in detail – including my full stock list and target allocation.
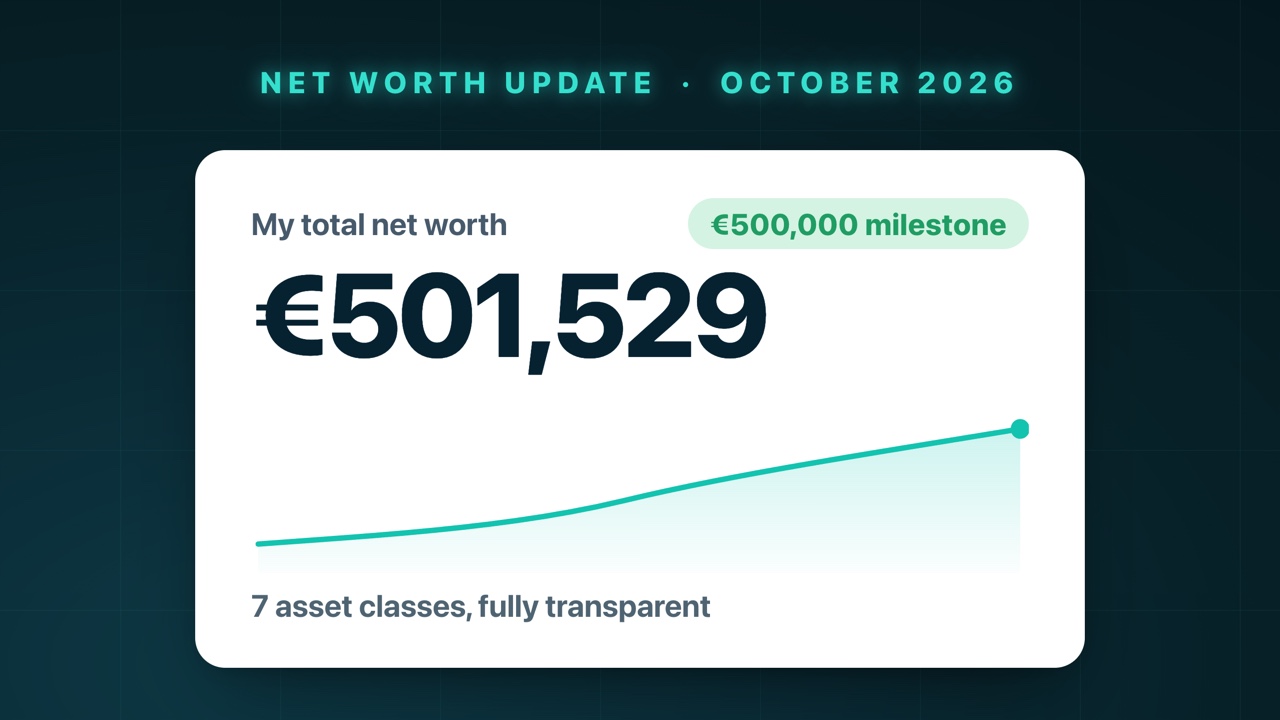
Table of contents
- Overview: My wealth in September 2026
- No. 7: Other assets (real assets & private markets)
- Video
- No. 6: Occupational pension for the self-employed
- No. 5: Cash as a buffer and war chest
- No. 4: Cryptocurrencies – Bitcoin in focus
- No. 3: Real estate as an investment
- No. 2: P2P loans with stable cash flow
- No. 1: My stock portfolio
- My portfolio live on Parqet
- My target allocation
- Summary: My wealth distribution
- From zero to the first million?
- Conclusion
- FAQ
Another month is over – time for my monthly net worth update. As always, I'll show you fully transparently which asset classes I'm invested in, how they're weighted in percent and how my wealth has developed. The cut-off date is 30 September 2026. And one thing up front: this month is a very special one, because for the first time I've cracked the half-million mark.
For anyone new here: I'm Lennard and I share everything about finance on this channel. I test financial products and show fully transparently how I invest myself. And the most important note up front: this is not investment advice and not a buy recommendation. I only ever share my personal opinion and my personal investments. Inform yourself about the risks of the respective asset classes and make your own decision.
Overview: My wealth in September 2026
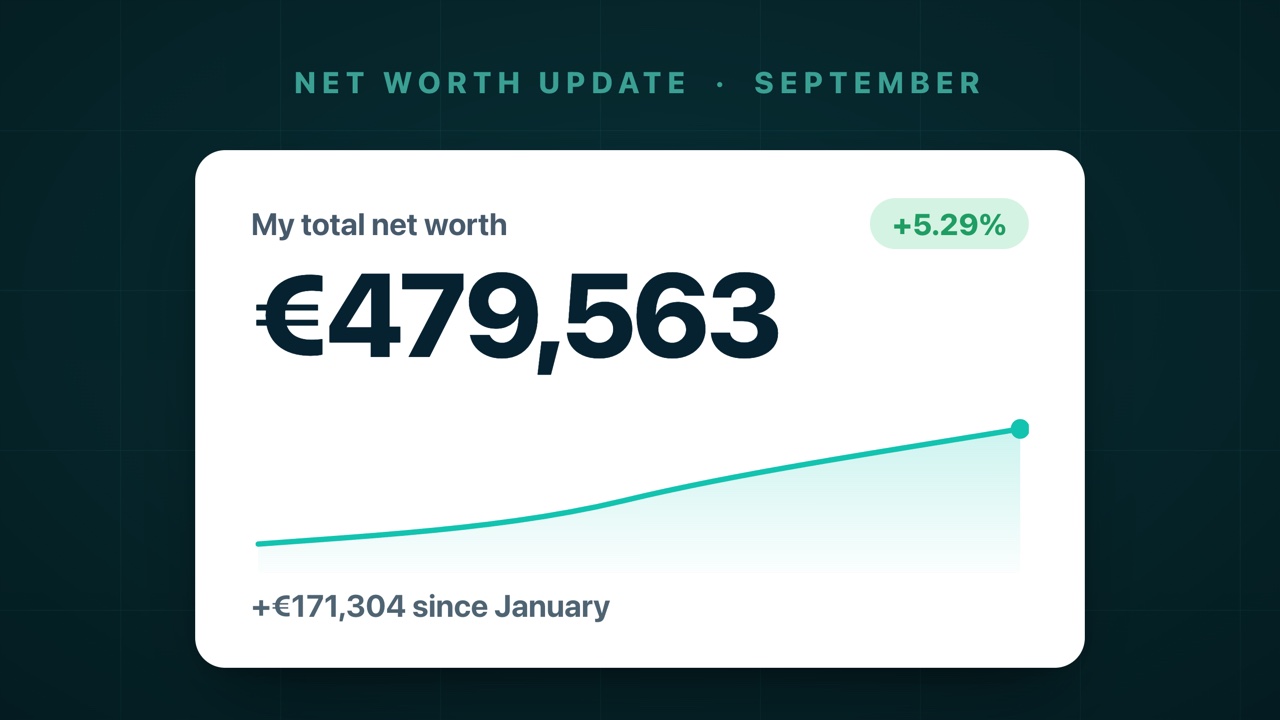
As of 30 September 2026, there is €501,529 in the portfolio. That's growth of €21,966 on the previous month – so +4.58% in a single month. With that, the psychologically important €500,000 mark has fallen for the first time.
Here's how my wealth has developed in comparison:
| Growth since | Value in € | Growth in € | Growth in % |
|---|---|---|---|
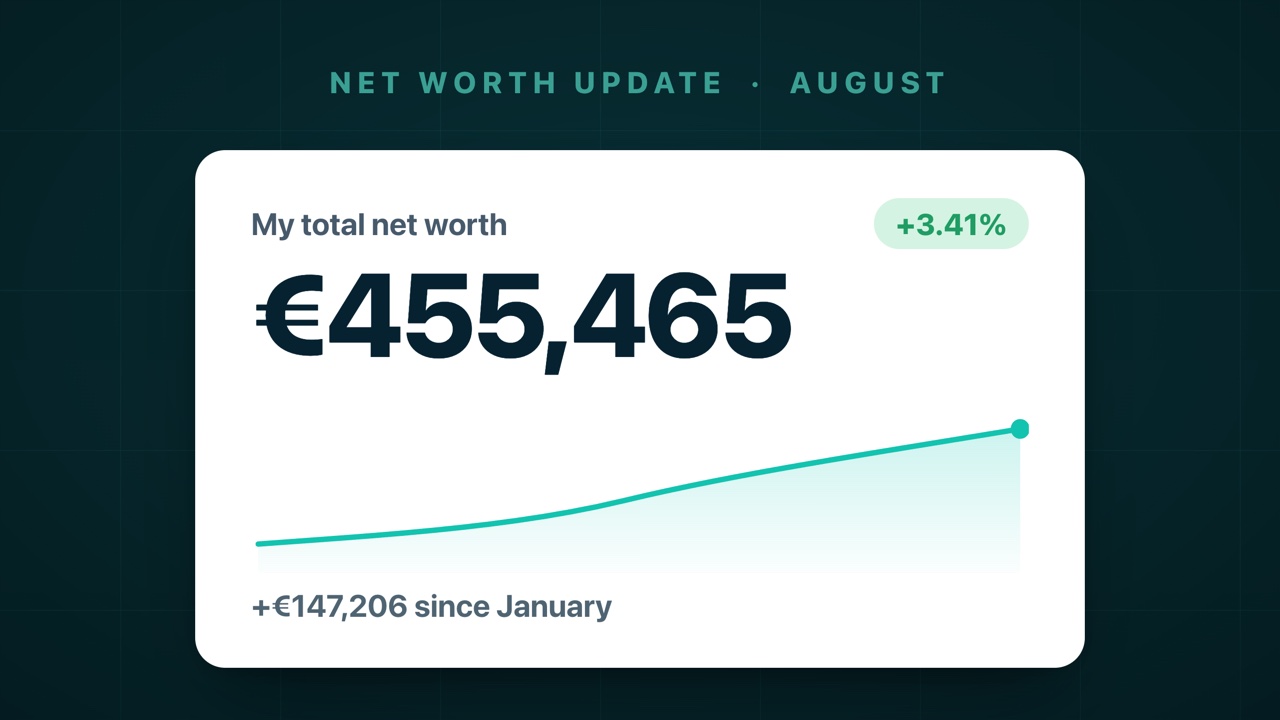
| 31 Dec 2025 | €308,259 | +€193,270 | +62.70% |
| 31 Aug 2026 | €479,563 | +€21,966 | +4.58% |
That means I've grown by 62.70% since the start of the year, which is really enormous. But an honest note matters to me: the bulk of this growth doesn't come from pure returns, but from my income, which I continuously invest in stocks, real estate and the like. I'm self-employed, have several companies and am currently ramping up my income strongly month by month – hence the strong growth.
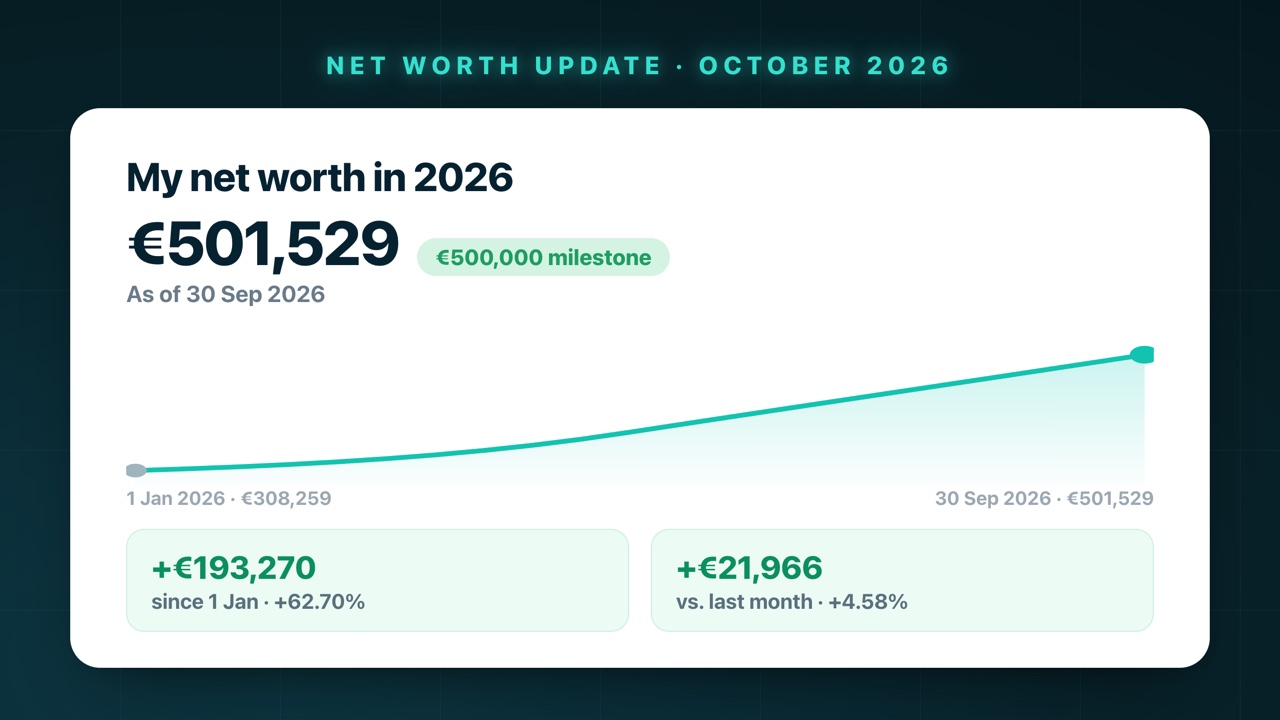
There's one change to the structure this month: my previous eight categories have become seven. I've combined the small positions "real assets" and "private markets" into a single category, "Other assets" – which makes the overview cleaner. As always, we'll work our way from the smallest to the largest position and look at the overall distribution again in detail at the end. Here's how it looks (from large to small):
- Stocks & ETFs – €261,791
- P2P loans – €108,205
- Real estate (my equity share) – €66,500
- Cryptocurrencies – €28,159
- Cash – €19,028
- Occupational pension (bAV) – €11,000
- Other assets – €6,845
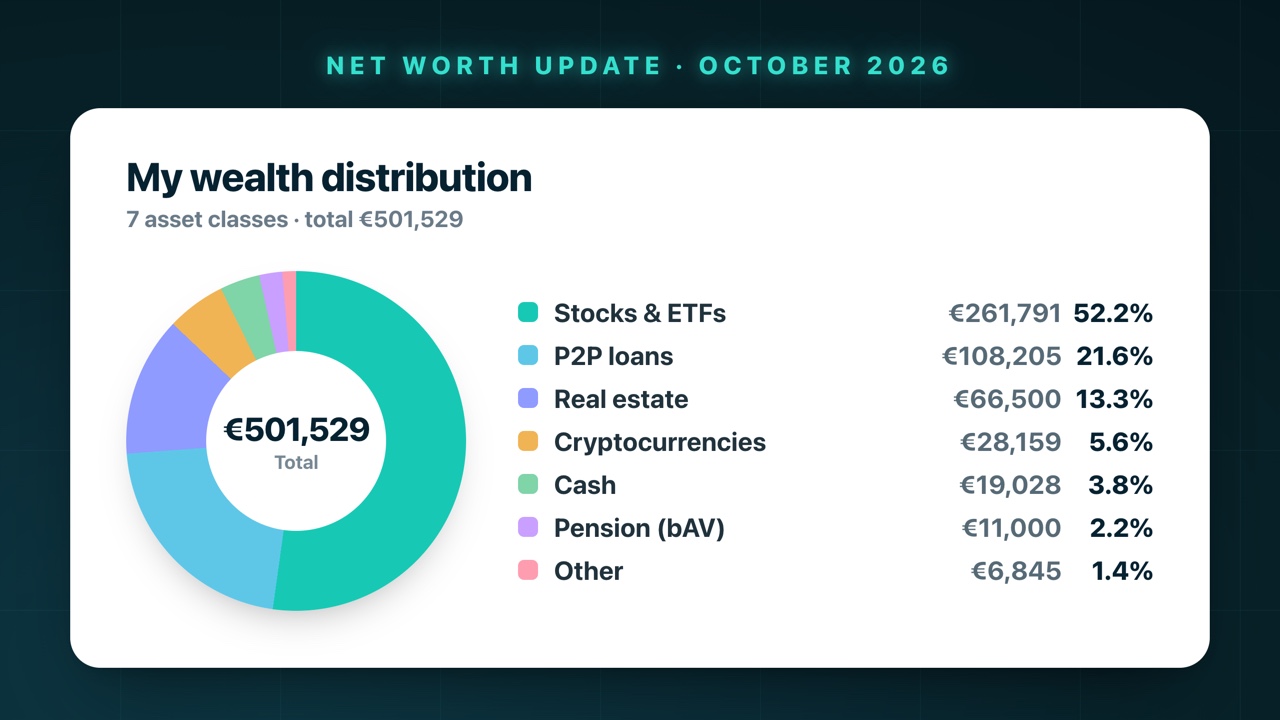
Let's go through the individual positions one by one.
No. 7: Other assets (real assets & private markets)
In last place is the new combined "Other" category at €6,845, around 1.4% of my total net worth. It holds two small diversification building blocks.
First, my real assets via the Timeless app* at €5,149. I don't have sneakers or luxury watches sitting at home for this – I invest entirely digitally in real assets like watches, cars and collectibles. The appeal: Timeless takes care of storage, insurance and the rest, so I do it completely passively. If you want to try it yourself, you currently get €10 in starting credit via my link.
Second, my private-markets investments via NAO at €1,696. NAO is a Berlin-based app that lets you invest in private equity and private markets – asset classes otherwise reserved for large investors. For me it's an interesting diversification block that I want to build up a little more. Deliberately, it's not (yet) a large sum.
Video: €501,529 Net Worth: My Portfolio Update for October 2026
This net worth update is also available as a video – I go through every position live. Feel free to watch, or read all the details below at your own pace.
No. 6: Occupational pension for the self-employed
In 6th place comes my occupational pension (bAV) at €11,000 (around 2.2%). As a self-employed person, I'm not in the statutory pension scheme – I could join voluntarily, but I don't. Instead, I provide for retirement via stocks, ETFs and real estate, but I also want a bAV for diversification.
My company pays into it every month. During the saving phase, the whole thing is completely free of social security contributions and taxes – it's only taxed later on payout at an older age. A solid, predictable building block that simply runs in the background.
No. 5: Cash as a buffer and war chest
In 5th place is my cash at €19,028 (around 3.8%). That's deliberately a bit more than in previous months: part of it is the normal buffer for day-to-day business, the other part is a small "war chest" to act quickly on opportunities – such as a pullback on the stock market or a suitable property. But the bulk of my wealth is and remains invested; cash isn't an end in itself for me, but a means to an end.
No. 4: Cryptocurrencies – Bitcoin in focus
In 4th place are my cryptocurrencies at €28,159, or around 5.6% of the portfolio – and that's almost entirely Bitcoin: €27,998 in Bitcoin and just a leftover Solana position of €161.
I'll offload Solana as soon as it's back in the green. With Bitcoin I stay invested long-term and buy more regularly. Long-term I can imagine an allocation of around 10% here – either through further buying or simply because Bitcoin does well.
I buy my crypto via the Dutch, EU-regulated exchange Bitvavo*. If you want to start there yourself, you currently get €20 in Bitcoin free via my link. But crypto is and remains a highly volatile asset class – only invest money whose swings you can stomach.
No. 3: Real estate as an investment
In 3rd place is my real estate with a portfolio value of €66,500 (around 13.3%). I physically invest myself in a total of three properties in Germany. The rough market value of all three objects together is – depending on the estimate – between around €600,000 and €800,000.
Important to understand: I don't enter the full market value into the portfolio, but the estimated value minus the remaining debt – multiplied by my actual ownership share. Only that way does the figure reflect my real equity.
- Property 1 (apartment, 100% mine): estimated value €135,000, remaining loan €111,146 → my equity share: €23,854
- Property 2 (commercial hall, half mine): equity share pro-rated to my 50%
- Property 3 (apartment, half mine): equity share pro-rated to my 50%
For properties 2 and 3, I deliberately don't quote embellished individual figures but only count my half share of the net value. If you'd like to see more real estate content – for example an example calculation on profitability and financing – let me know in the comments.
No. 2: P2P loans with stable cash flow
In 2nd place are my P2P loans at €108,205, or 21.6% of my total net worth. I cracked the €100,000 mark here a while ago – now the position is only growing moderately.
Strategically, it's important to me: P2P will become significantly smaller in percentage terms. Long-term I'm aiming for more like 5–10% here. Instead, I'm funding stocks, real estate and crypto more strongly. I hold P2P as a diversification block for predictable cash flow, and it fits well into my strategy of dividends, rental income and P2P interest.
I'm invested across more than 20 platforms. The five largest are currently Go & Grow* (formerly Bondora), Debitum*, Mintos*, Lande* and Indemo*. Lendermarket* will be joining shortly. A detailed, separate P2P update with all platforms follows in the next few days. You can view my full P2P portfolio live at any time: Look inside the P2P portfolio.
No. 1: My stock portfolio
The undisputed leader remains my stock and ETF portfolio: €261,791, and thus 52.2% of my total net worth.
The foundation is a broad world ETF: the Vanguard FTSE Global All-Cap UCITS ETF (distributing variant, ISIN IE000CVUM3N6 / WKN A42B1N). It holds around €69,920 – so about 26.8% of my stock portfolio. The ETF invests in over 10,000 companies from developed and emerging markets, effectively covering the entire global market. It's my "worry-free core" around which I deliberately build individual stocks.
With individual stocks I follow a clear dividend strategy – I like passive income without having to sell anything for it. That's also reflected in the holdings. My 15 largest individual positions:
| # | Stock | Value in € |
|---|---|---|
| 1 | McDonald's | €20,535 |
| 2 | Procter & Gamble | €15,396 |
| 3 | Munich Re | €14,970 |
| 4 | Zoetis | €13,677 |
| 5 | Waste Management | €12,671 |
| 6 | Allianz | €12,438 |
| 7 | PepsiCo | €12,352 |
| 8 | Main Street Capital | €12,228 |
| 9 | Coca-Cola | €12,227 |
| 10 | Nestlé | €11,991 |
| 11 | LVMH | €11,501 |
| 12 | Realty Income | €10,613 |
| 13 | Hermès | €10,580 |
| 14 | VICI Properties | €10,200 |
| 15 | Novo Nordisk | €9,243 |
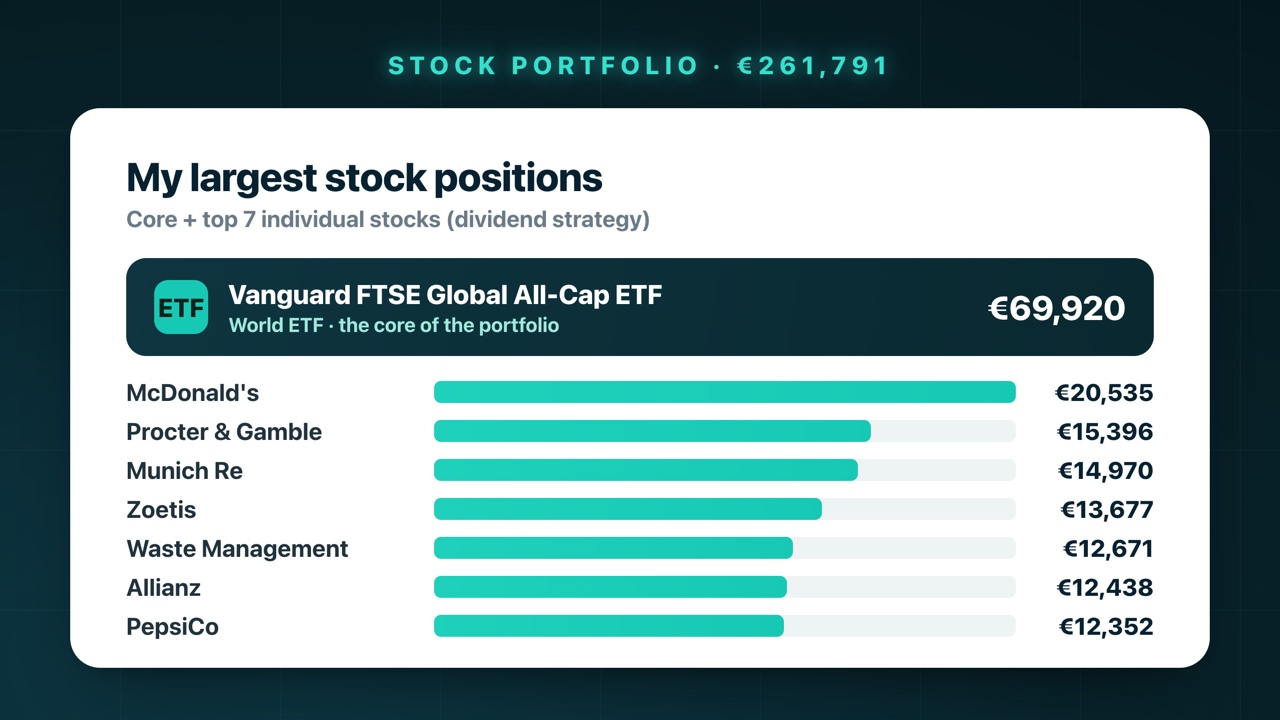
As you can see: a colourful mix of consumer goods (McDonald's, P&G, PepsiCo, Coca-Cola, Nestlé), insurers (Munich Re, Allianz), luxury (LVMH, Hermès), real estate investment trusts (Realty Income, VICI Properties) and healthcare (Zoetis, Novo Nordisk). All titles with – in my view – stable, predictable dividends.
An organisational note: since January I've been investing my stocks via my holding company. Price gains within the holding are effectively taxed at only around 1.5% as long as I don't distribute – a big lever for long-term reinvesting. For most retail investors, though, the normal brokerage route is perfectly sufficient; a holding only pays off from certain sums and with the right setup.
If you're looking for a low-cost brokerage account into which you can also transfer existing positions: I use Smartbroker+*, among others – when you open an account there, you currently get €20 in stocks free. There's also a detailed update on my dividend portfolio coming in the next few days, where I go specifically into the individual positions and my dividends.
My portfolio live on Parqet
If you're interested in my full portfolio: I share it live and in real time via Parqet*. There you'll find all positions, statistics and data – fully transparent. I've summarised how Parqet works as a portfolio tracker and what it costs in my Parqet review.
My target allocation
Finally, a look ahead. My current distribution isn't set in stone – I deliberately steer it in a target direction. Here's my target-vs-actual comparison:
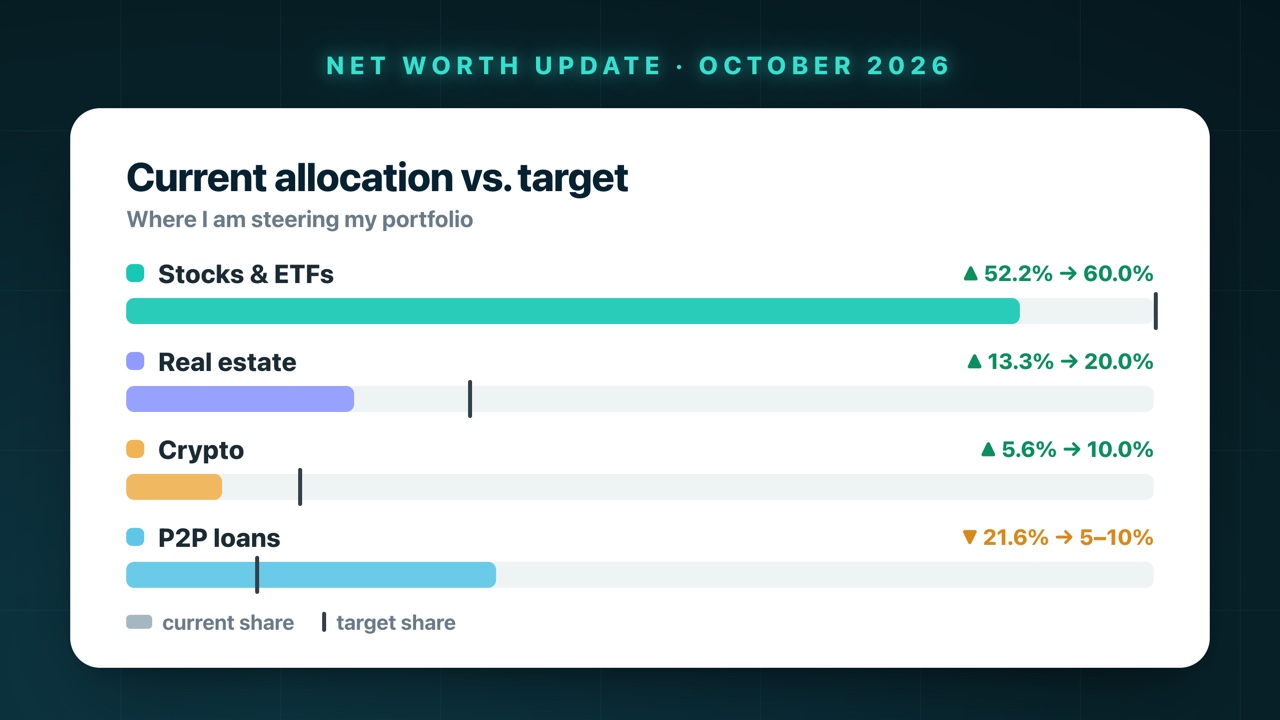
- Stocks & ETFs: from 52.2% → around 60% (may still grow)
- Real estate: from 13.3% → around 20% (can happily become more)
- Crypto: from 5.6% → around 10% (should settle in)
- P2P loans: from 21.6% → 5–10% (should come down significantly)
Important: with P2P, "down" doesn't mean I'm selling – I simply leave the position as it is and build up the other blocks more strongly around it. That way the P2P share falls automatically.
Summary: My wealth distribution
So in total there is €501,529 in the portfolio. Here it is again compactly, from small to large:
| Rank | Asset class | Value in € | Share |
|---|---|---|---|
| 7 | Other assets | €6,845 | 1.4% |
| 6 | Occupational pension | €11,000 | 2.2% |
| 5 | Cash | €19,028 | 3.8% |
| 4 | Cryptocurrencies | €28,159 | 5.6% |
| 3 | Real estate | €66,500 | 13.3% |
| 2 | P2P loans | €108,205 | 21.6% |
| 1 | Stocks & ETFs | €261,791 | 52.2% |
From zero to the first million?
To close, one thought that matters to me – especially for anyone just starting out. It took me around seven years for my first €100,000. That sounds long, but that's exactly the point: the beginning is the slowest part. After that, compound interest works for you, and every further €100,000 mark comes noticeably faster – going from €479,563 to over €500,000 just happened in a single month.
The most important step is therefore simply to start – no matter the amount. Whether €20 or €30 a month: what matters is that you get into action and stick with it. The rest is time and discipline.
Conclusion
September was a historic month: +4.58% on the previous month and, for the first time, above the €500,000 mark. Since the start of the year, I'm up 62.70%. My structure is now leaner (seven instead of eight categories), and my focus stays clear: more stocks, more real estate, more crypto – and gradually scaling back P2P in percentage terms.
Now I'm curious: how do you actually invest? Do you rely on several categories, do you have, say, precious metals in your portfolio, which I'm completely missing so far? And what did you buy most recently? Let me know in the comments – I really enjoy exchanging ideas with you about your strategies.
Frequently asked questions
How large is Lennard's net worth in October 2026?
As of the cut-off date of 30 September 2026, my total net worth stands at €501,529. That means I've crossed the half-million-euro mark for the first time. Compared with the previous month (€479,563), that's growth of €21,966 or 4.58%; since the start of the year (€308,259) it's a gain of €193,270 or 62.70%.
How is the net worth made up?
My wealth is spread across seven asset classes: stocks & ETFs (€261,791, 52.2%), P2P loans (€108,205, 21.6%), real estate (€66,500, 13.3%), cryptocurrencies (€28,159, 5.6%), cash (€19,028, 3.8%), occupational pension (€11,000, 2.2%) and other assets (€6,845, 1.4%). The former eight categories have become seven because I now group real assets and private markets together under 'Other'.
Where does the strong 62.70% growth since the start of the year come from?
The bulk of the growth doesn't come from pure returns, but from my income, which I invest continuously. I'm self-employed, have several companies and am ramping up my income month by month. On top of that come price gains in stocks and Bitcoin, plus the ongoing interest from my P2P loans.
Which ETF is in Lennard's portfolio?
The core of my stock portfolio is the Vanguard FTSE Global All-Cap UCITS ETF (distributing, ISIN IE000CVUM3N6 / WKN A42B1N) at around €69,920 – about 26.8% of my stock portfolio. The ETF invests in over 10,000 companies from developed and emerging markets, effectively covering the entire global market.
What is Lennard's target allocation?
Concrete targets: stocks should grow from 52.2% to around 60%, real estate from 13.3% to around 20%, crypto from 5.6% to around 10%. P2P, on the other hand, should fall significantly from 21.6% to 5–10% – not through sales, but because the other building blocks grow faster.
Where can I follow Lennard's portfolio live?
I share my full portfolio live and in real time via Parqet (finlen.de/dividenden). You can also view my P2P portfolio live at any time (finlen.de/p2p). There you'll find all positions and statistics, fully transparent.
Disclaimer
⚠️ Not investment advice
All content is for information and entertainment purposes only and does not constitute investment advice, a buy recommendation or an invitation to enter into a financial product. Please do your own research and make decisions based on your personal situation and risk tolerance.
📉 Risk warning & total loss
Investments in securities and other financial instruments generally carry significant risks (e.g. price, market, currency, volatility and credit risks). A total loss of the capital invested cannot be ruled out.
📊 Returns & forecasts
All performance figures, whether historical or as a forecast/estimate, are not a reliable indicator of future results. Capital and returns are not guaranteed.
🔍 Transparency & conflicts of interest
I strictly distinguish between facts and personal estimates. Important: I am often invested in the assets discussed myself, which can create a conflict of interest.
✅ DYOR (Do Your Own Research)
All information has been compiled carefully but is non-binding, without warranty and without any claim to completeness. Please inform yourself thoroughly and consider all opportunities and risks in depth before making an investment decision.
Advertising & affiliate notice
Links marked with * are advertising or affiliate links. If you sign up or buy something through such a link, I may receive a commission – at no extra cost to you. This supports my work.