Debitum Flow: 8% Interest, Daily and Flexible? My Honest Take on the New Fixed-Income Product
Debitum has launched a new product called Flow: 8% p.a. on regulated notes, daily interest payments and flexible early withdrawal – with no exit fees. I explain how Flow really works, how flexible it actually is (the €1,000 and €5,000 limits), how safe your money is, how Flow stacks up against Bondora Go & Grow, Monefit and TWINO – and how to get 1% cashback through my link.
Table of contents
- Debitum Flow at a glance
- What is Debitum Flow?
- Video
- 8% interest, paid out daily
- How flexible is Flow really? The withdrawal limits
- How much can I invest? Two notes, €10,000
- How safe is Debitum Flow?
- The loyalty programme: Flow counts toward your level, but earns no rate bonus
- Debitum Flow vs. Go & Grow, Monefit & TWINO
- The bonus: 1% cashback in the first 30 days
- The downsides – what to watch out for
- Is Flow worth it?
- Verdict: the highest rate in the flexible field – with the risks stated
- FAQ
Debitum has launched a new product that immediately caught my attention: Debitum Flow. The pitch almost sounds too good – 8% interest per year, paid out daily, and flexible, because you can exit early with no exit fees. It's essentially Debitum's answer to savings-account-like products such as Bondora Go & Grow or Monefit SmartSaver – only with the highest rate in the field. In this post I look at how Flow really works, how flexible it actually is, how safe your money is, and how it compares to the competition.
As always, first the most important note: this is not investment advice and not a buy recommendation, just my personal opinion. Debitum Flow is not a savings account – your capital is not guaranteed, and you can lose money. The Debitum link is a partner link: if you use it, you support my work at no extra cost to you – on the contrary, you secure the cashback.
Debitum Flow at a glance
- Rate: 8% p.a. fixed on regulated notes
- Interest payments: daily
- Flexibility: early withdrawal possible, no exit fees
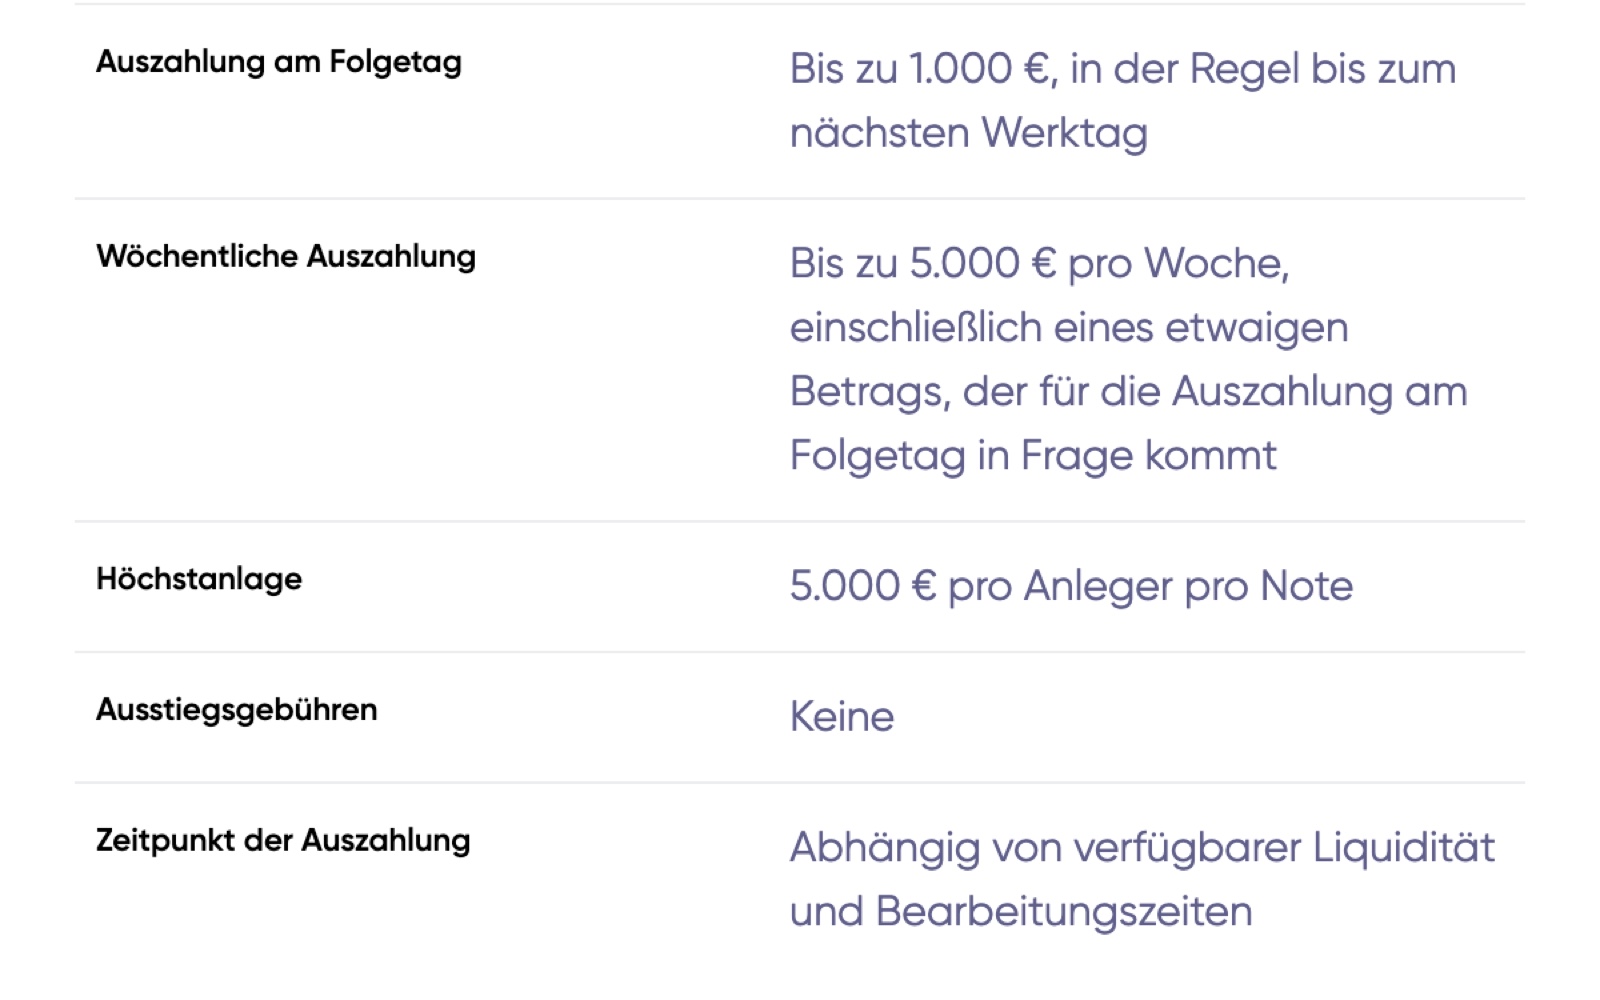
- Withdrawal limits: up to €1,000 next day, up to €5,000 per week (inclusive)
- Minimum: €10 per note · Maximum: €5,000 per note
- Two notes at launch (Baltic Terra, LFDF II) → up to €10,000 total
- Note maturity: 5 years (with the option to request early withdrawal)
- Regulated: MiFID II, notes with an ISIN under a base prospectus approved by the Bank of Latvia
- Bonus: 1% cashback in the first 30 days through my link
What is Debitum Flow?
Debitum Flow is a flexible fixed-income product. Instead of picking individual loans, you invest in regulated notes – debt securities with their own ISIN, issued under an approved base prospectus. In return you earn 8% interest per year. The money from your notes flows to Debitum's funding partners, who use it to issue secured loans.
The big difference from normal P2P loans, and from Debitum's classic offering: flexibility. With the usual Debitum investments, your money is locked until maturity (there's no secondary market). Flow, by contrast, lets you request an early payout – within certain limits, more on that in a second.
Video: Debitum Flow: 8% Interest, Daily and Flexible? My Honest Take on the New Fixed-Income Product
I also walk through Debitum Flow step by step in the video. Feel free to watch, or read on below.
8% interest, paid out daily
The rate is the main reason Flow is getting so much attention: 8% p.a., with interest credited to your account daily. That's more than the well-known flexible competitors (more below). The notes have a 5-year maturity, but you can request an early payout.
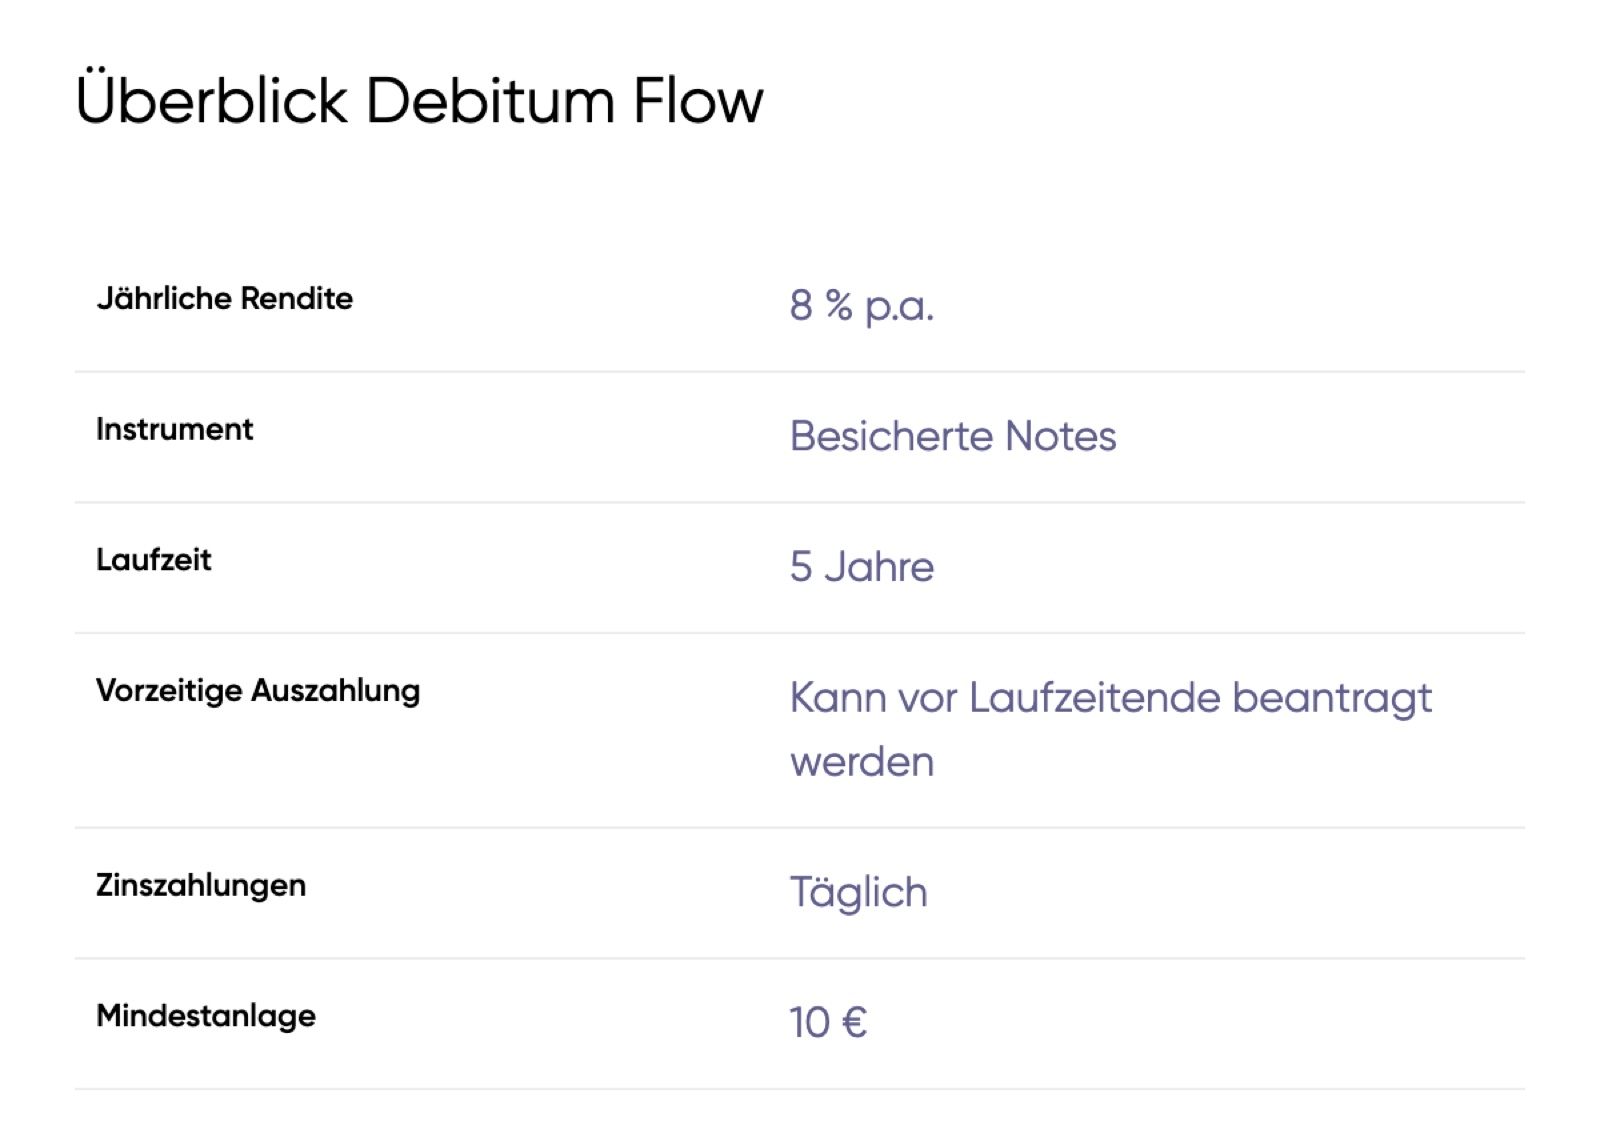
An honest point right up front: the 8% is a fixed coupon, but not a guarantee. Debitum itself clearly states that Flow is not a deposit or savings account and that your capital is not guaranteed. If the funding partners default, you can lose part or all of the amount. The high rate is the premium for that risk – not free money.
How flexible is Flow really? The withdrawal limits
This matters, because it's often described loosely online. The flexibility has clear limits:
- Up to €1,000 can usually be paid out by the next business day.
- Up to €5,000 per week – this weekly amount includes the €1,000 next-day amount, so it's not on top.
- No exit fees for early withdrawal.
So there's no "€1,000 per day" limit, as you sometimes read. The €1,000 is the portion eligible for the fast next-day payout; anything above runs through the weekly cycle up to €5,000. Withdrawal requests go into a transparent queue processed on a first-in-first-out basis – and timing depends on available liquidity. So it's not instant availability like an instant-access account.
How much can I invest? Two notes, €10,000
The minimum is €10 per note, the maximum €5,000 per investor per note. At launch there are two notes – Baltic Terra and the Latvian Forest Development Fund II (LFDF II). Since you can put up to €5,000 into each, your total limit is €10,000. My app shows this as "Remaining investment limit €10,000":

This €10,000 cap is also Flow's biggest limitation: anyone wanting to park substantially more flexibly hits the ceiling fast. It works for a liquid buffer of a few thousand euros; as a large return building block for a bigger portfolio, not (yet).
How safe is Debitum Flow?
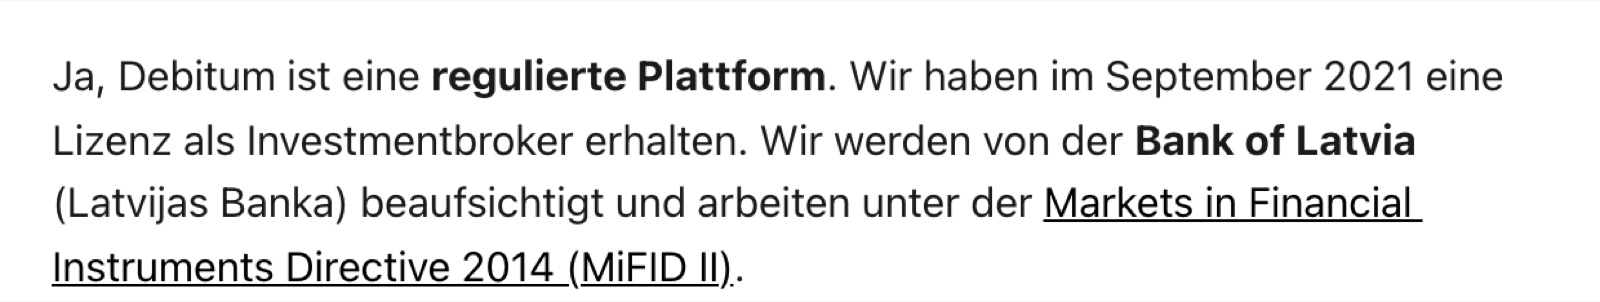
Debitum isn't an unknown newcomer but has been on the market for years: the company has been licensed as an investment brokerage firm since September 2021 and is supervised by the Bank of Latvia. The Flow notes are securities with an ISIN under a base prospectus approved by the Bank of Latvia and regulated under MiFID II. That's a different, formal regulatory framework from many pure P2P loans.
On scale: as of 14 Sept 2026, Debitum has facilitated around €223.76M, of which €152.48M has already been repaid, and counts over 34,700 investors. That's a solid track record.
And yet the flip side belongs here too:
- No deposit insurance. Flow is not a savings account, your capital is not guaranteed.
- Exit not guaranteed. Per the base prospectuses (LFDF II and Baltic Terra), the issuer may accept or reject early-repayment requests at its own discretion. So don't count on always getting out fully before maturity.
- Default risk of the funding partners. If something goes wrong there, your money is at risk.
The loyalty programme: Flow counts toward your level, but earns no rate bonus
Debitum has a loyalty programme with four tiers that raise your rate on other investments:
| Tier | Invested | Loyalty bonus |
|---|---|---|
| New Investor | < €6,000 | – |
| Investor | €6,000–24,999 | +0.50% p.a. |
| Investor Pro | €25,000–49,999 | +1.00% p.a. |
| Investor Elite | > €50,000 | +2.00% p.a. |
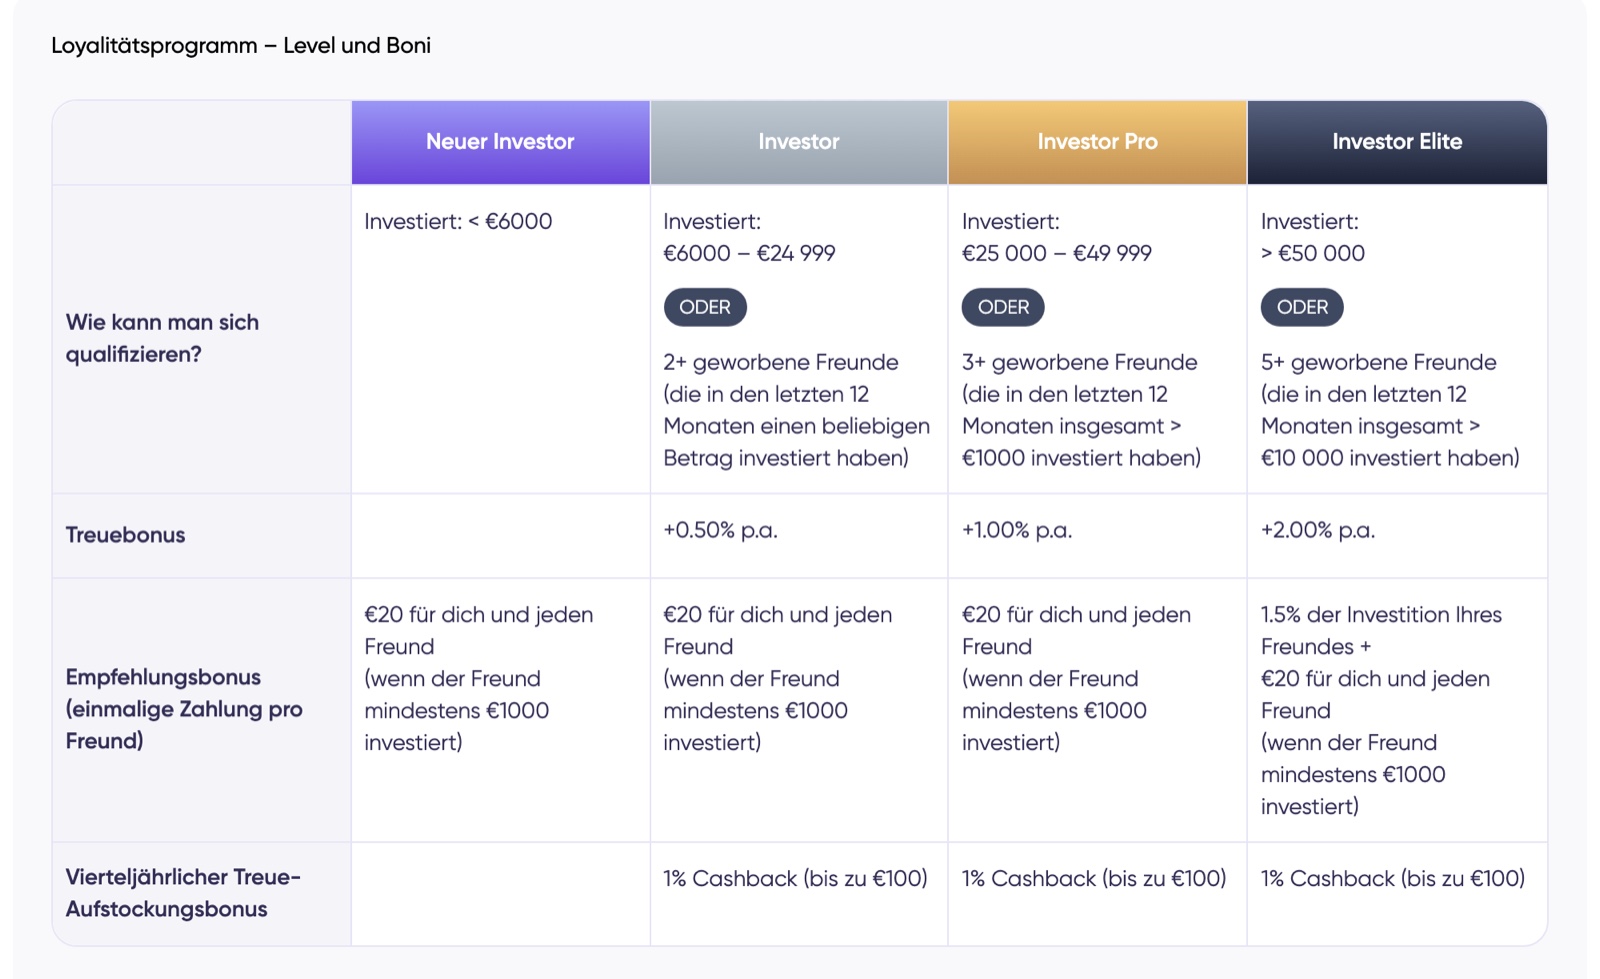
The important catch many people miss: the loyalty bonus does not apply to Flow itself – the rate bonus only counts for primary-market investments via the normal "Invest" page. But: your Flow balance counts toward your tier, so it helps you reach a higher loyalty level (and thus more bonus on your other Debitum investments). A clever detail if you invest more broadly with Debitum anyway.
Debitum Flow vs. Go & Grow, Monefit & TWINO
Flow takes on the established flexible products. Here's how the rate sits:
| Product | Rate p.a. | Notable |
|---|---|---|
| Debitum Flow | 8% (fixed) | MiFID II notes, max €10,000, very new |
| Bondora Go & Grow | up to 6% | broad consumer-loan portfolio, no deposit limit, proven for years |
| Monefit SmartSaver | expected 7.5% | flexible main account, vaults with higher rates |
| TWINO FLEXI | 6% (fixed) | max €10,000 per investor |
Debitum Flow has the highest rate in the field – that's the clear plus. In return it's brand new and capped at €10,000. Go & Grow scores with a long track record and no deposit limit, but a lower rate. For me, Flow is the most exciting newcomer, but no reason to throw everything else overboard – the mix is what counts.
The bonus: 1% cashback in the first 30 days
Through my Debitum link* you get 1% cashback on your investments in the first 30 days after registration. The bonus runs automatically via the link, no voucher code needed. As always: check the current promotion terms directly at Debitum before you finish.
The downsides – what to watch out for
- Not a savings account. No guaranteed rate, no deposit insurance, capital not guaranteed.
- Flexibility has limits. €1,000 next day, €5,000 per week (inclusive), subject to available liquidity – no instant access like an instant-access account.
- Early exit not guaranteed. Per the base prospectus, early repayment is at the issuer's discretion.
- Capped at €10,000 (2 notes at €5,000 each).
- No loyalty bonus on Flow itself (though Flow counts toward your tier).
- Very new product – little experience over a full cycle.
Who is Debitum Flow right for?
- want a high, fixed rate (8%) with daily payouts
- want flexibility and don't want to be locked in until maturity
- are looking for a MiFID-II-regulated alternative to Go & Grow & co.
- want to grab the 1% cashback in the first 30 days
- need guaranteed, instant availability like an instant-access savings account
- want to park more than €10,000 flexibly (Flow is currently capped)
- prefer a long-proven product over a brand-new solution
- would invest money whose loss you couldn't handle
Verdict: the highest rate in the flexible field – with the risks stated
Debitum Flow is a genuinely interesting product: 8% fixed, paid out daily, a decent dose of flexibility, and a MiFID-II-regulated framework on a platform established since 2021. For a flexible liquidity buffer of a few thousand euros meant to earn more than Go & Grow & co., I find Flow appealing – especially with the highest rate in the field.
What stays important is the honest framing: it's not a savings account, the exit is within limits and not guaranteed, and the €10,000 cap limits how much you can put to work. If you accept that and only use money whose loss you could handle, you get one of the most interesting flexible P2P options of the year. If you want to try it, best to grab the cashback right away: try Debitum Flow through my link and take the 1% cashback*.
Links marked with * are partner links. If you invest through them, you support my work – at no extra cost to you; you secure the cashback. Thank you!
Frequently asked questions
What is Debitum Flow?
Debitum Flow is a new, flexible fixed-income product from the P2P platform Debitum. You invest in regulated notes (debt securities with an ISIN) and earn 8% interest per year, paid out daily. Unlike classic P2P loans, Flow lets you exit early – with no exit fees, but within certain limits.
How high is the interest on Debitum Flow?
Flow offers 8% p.a. as a fixed rate on the notes, with interest paid out daily. Important: it's a fixed coupon, not a guarantee – Debitum Flow is not a deposit or savings account, and your capital is not guaranteed. Debitum's loyalty programme can raise your overall rate on other Debitum investments, but the loyalty bonus does not apply to Flow itself.
How quickly can I get my money out of Debitum Flow?
Flow is much more flexible than normal P2P loans: up to €1,000 can usually be paid out by the next business day, up to €5,000 per week (this weekly amount includes the €1,000 next-day amount). Withdrawal requests go through a transparent first-in-first-out queue. Even so, an instant payout is not guaranteed – it depends on available liquidity.
How much can I invest in Debitum Flow?
The minimum is €10 per note. The maximum is €5,000 per investor per note. At launch there are two notes (Baltic Terra and the Latvian Forest Development Fund II), so you can invest up to €10,000 in Flow in total. My app shows this as 'Remaining investment limit €10,000'.
Is Debitum Flow safe and regulated?
Debitum has been licensed as an investment brokerage firm since September 2021 and is supervised by the Bank of Latvia. The Flow notes are securities with an ISIN under a base prospectus approved by the Bank of Latvia and regulated under MiFID II. Still: it's not a savings account, there's no deposit insurance, and your capital is not guaranteed. If the funding partners default, you can lose part or all of your investment.
Debitum Flow or Bondora Go & Grow – which is better?
Both are flexible, savings-account-like P2P products. Debitum Flow offers 8% p.a. on secured, MiFID-II-regulated notes; Bondora Go & Grow up to 6% p.a. on a broadly diversified consumer-loan portfolio with no deposit limit. Monefit SmartSaver sits at an expected 7.5%, TWINO FLEXI at 6% (max €10,000). Flow has the highest rate, but is new and capped at €10,000 – Go & Grow is proven over years and uncapped.
How does the Debitum cashback bonus work?
Through my partner link you get 1% cashback on your investments in the first 30 days after registration. The bonus runs automatically via the link, no code needed. Still, check the current promotion terms directly at Debitum before you finish.
Disclaimer
⚠️ Not investment advice
All content is for information and entertainment purposes only and does not constitute investment advice, a buy recommendation or an invitation to enter into a financial product. Please do your own research and make decisions based on your personal situation and risk tolerance.
📉 Risk warning & total loss
Investments in securities and other financial instruments generally carry significant risks (e.g. price, market, currency, volatility and credit risks). A total loss of the capital invested cannot be ruled out.
📊 Returns & forecasts
All performance figures, whether historical or as a forecast/estimate, are not a reliable indicator of future results. Capital and returns are not guaranteed.
🔍 Transparency & conflicts of interest
I strictly distinguish between facts and personal estimates. Important: I am often invested in the assets discussed myself, which can create a conflict of interest.
✅ DYOR (Do Your Own Research)
All information has been compiled carefully but is non-binding, without warranty and without any claim to completeness. Please inform yourself thoroughly and consider all opportunities and risks in depth before making an investment decision.
Advertising & affiliate notice
Links marked with * are advertising or affiliate links. If you sign up or buy something through such a link, I may receive a commission – at no extra cost to you. This supports my work.