Digilo Review 2026: My Honest Take on the New P2P Platform (9–12%, property-backed, ECSP-regulated)
My in-depth Digilo review: the new Latvian P2P platform funds property-backed loans at 9–12% interest, has been licensed by the Bank of Latvia as an ECSP since September 2025, and starts at €150. I'll show you the platform numbers, my own €1,000 investment including cashback, how safe your money is, the risks of this still very young platform – and how you get 3% cashback through my link.
Table of contents
- Digilo at a glance
- What is Digilo?
- Video
- The key facts: from €150, 9–12%, 12–36 months
- Regulated by the Bank of Latvia
- How safe is my money?
- The platform numbers – honestly framed
- One project in detail
- Auto-Invest
- My own account: what my Digilo investment looks like
- The bonus: 3% cashback in the first 60 days
- Fees
- The downsides and risks
- Is Digilo worth it?
- Verdict: a solid start, but deliberately early
- FAQ
Digilo is a new P2P platform that recently joined my portfolio – and because it's still pretty fresh on the market, I've taken an especially close look for you. Digilo is based in Latvia, funds property-backed loans at 9–12% interest and – unlike many newcomers – is already licensed by the Bank of Latvia as an ECSP. In this review I walk through the key facts, the regulation, the real platform numbers, my own investment including cashback, and above all the risks you need to understand with such a young platform.
As always, first the most important note: this is not investment advice and not a buy recommendation, just my personal opinion and experience. P2P loans are a high-risk investment – only invest money whose total loss you could handle. The Digilo link in this post is a partner link: if you use it, you support my work at no extra cost to you – on the contrary, you secure the cashback.
Digilo at a glance
- Platform: Digilo, operated by CSP Growth Solutions SIA from Riga, Latvia
- Model: crowdfunding for real-estate- and land-backed loans
- Interest: 9–12% p.a. expected (avg. 11.44% across projects so far)
- Minimum: €150 per project · Terms: 12–36 months
- Collateral: mortgage, LTV at most 60%
- Regulated: ECSP licence from the Bank of Latvia since 16 Sept 2025
- Payments: Lemonway (segregated accounts)
- Bonus: 3% cashback in the first 60 days through my link
- Important: no buyback guarantee, no deposit insurance, very young platform
What is Digilo?
Digilo is a licensed European crowdfunding platform focused on property-backed lending in Latvia and the EU. The principle is the classic P2P model: companies need capital – for refinancing or growth, say – and pledge a property or a plot of land as security. As an investor, you fund a share of these loans and earn interest.
Behind the platform is a team with a long real-estate and lending background: the founder has been active in real estate since 2008 per Digilo, issuing property-backed business loans since 2009, licensed consumer mortgage lending since 2016, licensed credit intermediary since 2023. That's a solid track record for the people – even if the platform Digilo itself is still very new.
Video: Digilo Review 2026: My Honest Take on the New P2P Platform (9–12%, property-backed, ECSP-regulated)
I've also taken a detailed look at Digilo in the video – including a walkthrough of my own account. Feel free to watch, or read on below.
The key facts: from €150, 9–12%, 12–36 months
You can start from €150 per project. Digilo quotes an expected return of 9–12% per year, shown separately for each project. Terms run from 12 to 36 months. Important for safety: every loan is mortgage-backed, and the loan-to-value (LTV) is at most 60% per Digilo – so the loan is only part of the pledged property value.
Regulated by the Bank of Latvia
For a young platform, this is the single biggest plus for me: Digilo already holds an ECSP licence. The Bank of Latvia (Latvijas Banka) granted the authorisation on 16 September 2025 (licence no. 27-10/2025/222) under the EU Crowdfunding Regulation 2020/1503. In the ESMA register, Digilo is listed as a "European Crowdfunding Service Provider" with status Active. The licence also covers ancillary services such as individual portfolio management (Auto-Invest) and its own credit scoring.
What this licence does not mean: the regulator does not guarantee repayment and does not vet each individual loan. It provides the framework – segregated client funds, standardised investor information, reporting duties. The credit risk still sits with you.
How safe is my money?
Two things matter to me here – and Digilo handles both cleanly:
- Segregated accounts: per the terms (15.1), investor funds are held in separate accounts and kept apart from Digilo's own assets. If the platform runs into trouble, your balance is not part of the insolvency estate.
- Lemonway as payment provider: all payments run through Lemonway, a payment institution licensed by the French regulator ACPR. Your wallet is held there.
Still – and this belongs in an honest review: there is no deposit insurance under the EU deposit-guarantee directive and no investor compensation scheme. P2P loans are not savings products. And there is no buyback guarantee: if a borrower defaults, the collateral has to be realised first – whether everything comes back is not guaranteed.
The platform numbers – honestly framed
Digilo has a public, hourly-updated statistics page. As of 15 Sept 2026 it looks like this:
| Metric | Value |
|---|---|
| Total funded | €82,945.77 |
| Funded projects | 4 |
| Registered investors | 207 |
| Average annual return | 11.44% |
| Earned by investors | €714.23 |
| Default rate | 0.00% |
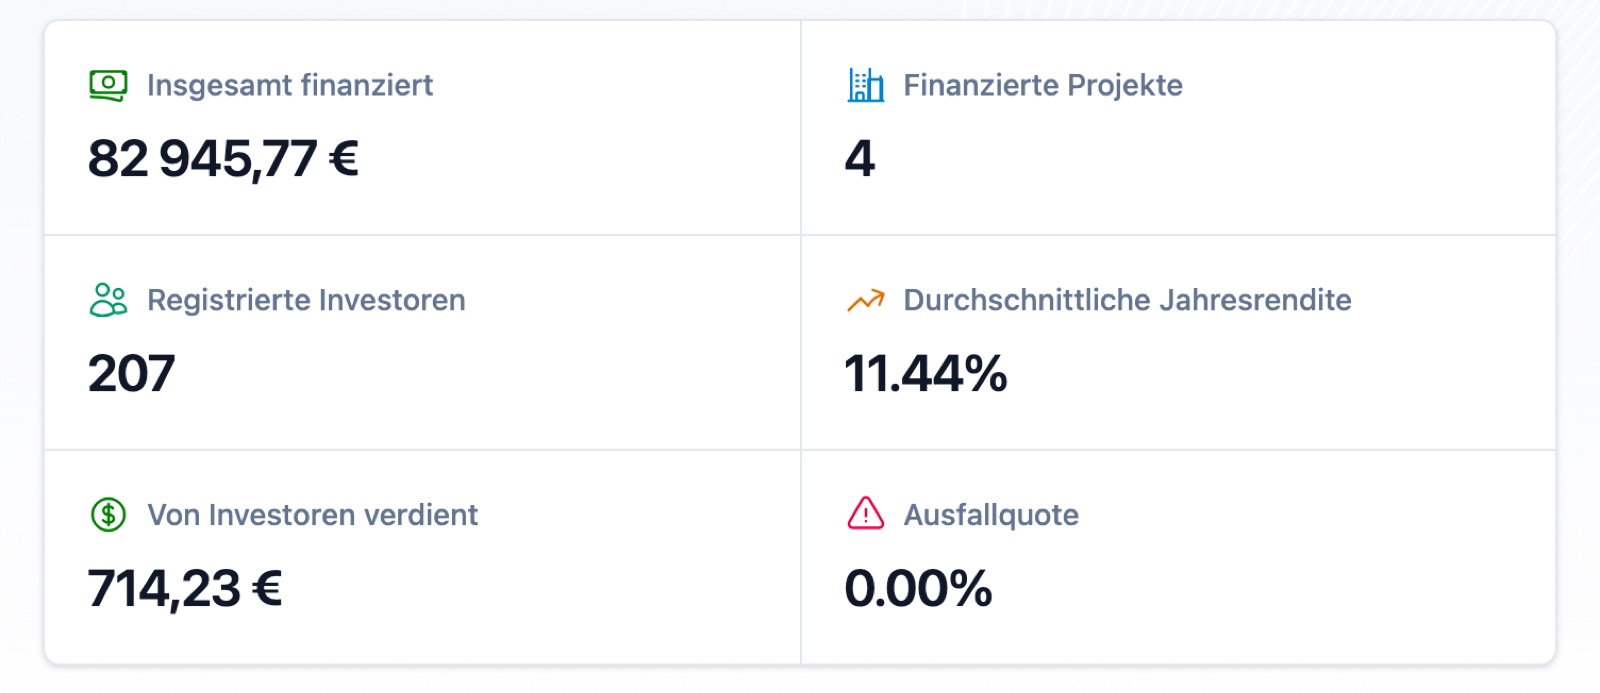
Sounds great at first – and in principle it is. But I have to frame these numbers, otherwise it wouldn't be honest: 4 funded projects and around €83,000 in total volume is very little. The 0.00% default rate is therefore barely meaningful yet – with so few, so young loans, none has had time to default. A reliable default history only builds over several years and many lending cycles. So take the numbers for what they are: a promising but very short start.
One project in detail
To give you a feel for what a Digilo project looks like, here's the currently open one from my view: €26,000 target, 36 months term, country Latvia, 9% interest, LTV 19%, risk category Low, collateral €138,675. Every project comes with a key investment information sheet (KIIS) under EU rules – though the full project description sits behind the login.
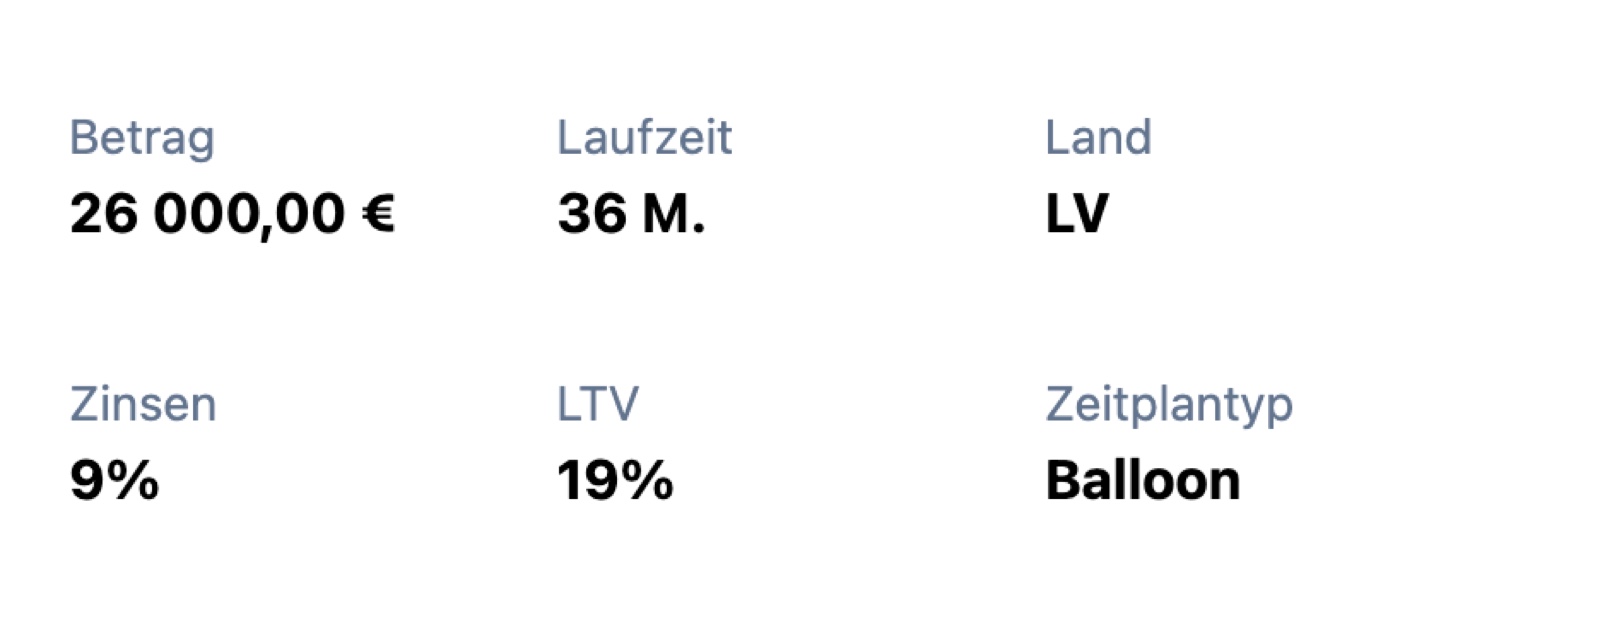
One detail for the thorough: Digilo assigns the risk category (Low/…) itself, and the exact criteria behind it are not published. The repayment type also varies by project (the current one, for instance, is a bullet/"Balloon" loan). So always read the specific project documents rather than relying on the label alone.
Auto-Invest
If you don't want to hand-pick every project, you can use Auto-Invest. There are two variants: Set & Forget (a fixed amount per new project, from €150) and Select & Maximize (by criteria such as LTV, interest rate, term, location and type of collateral, from €300). Handy for getting in early when a new project goes live – especially since, with so few projects, funding rounds can fill up quickly.
My own account: what my Digilo investment looks like
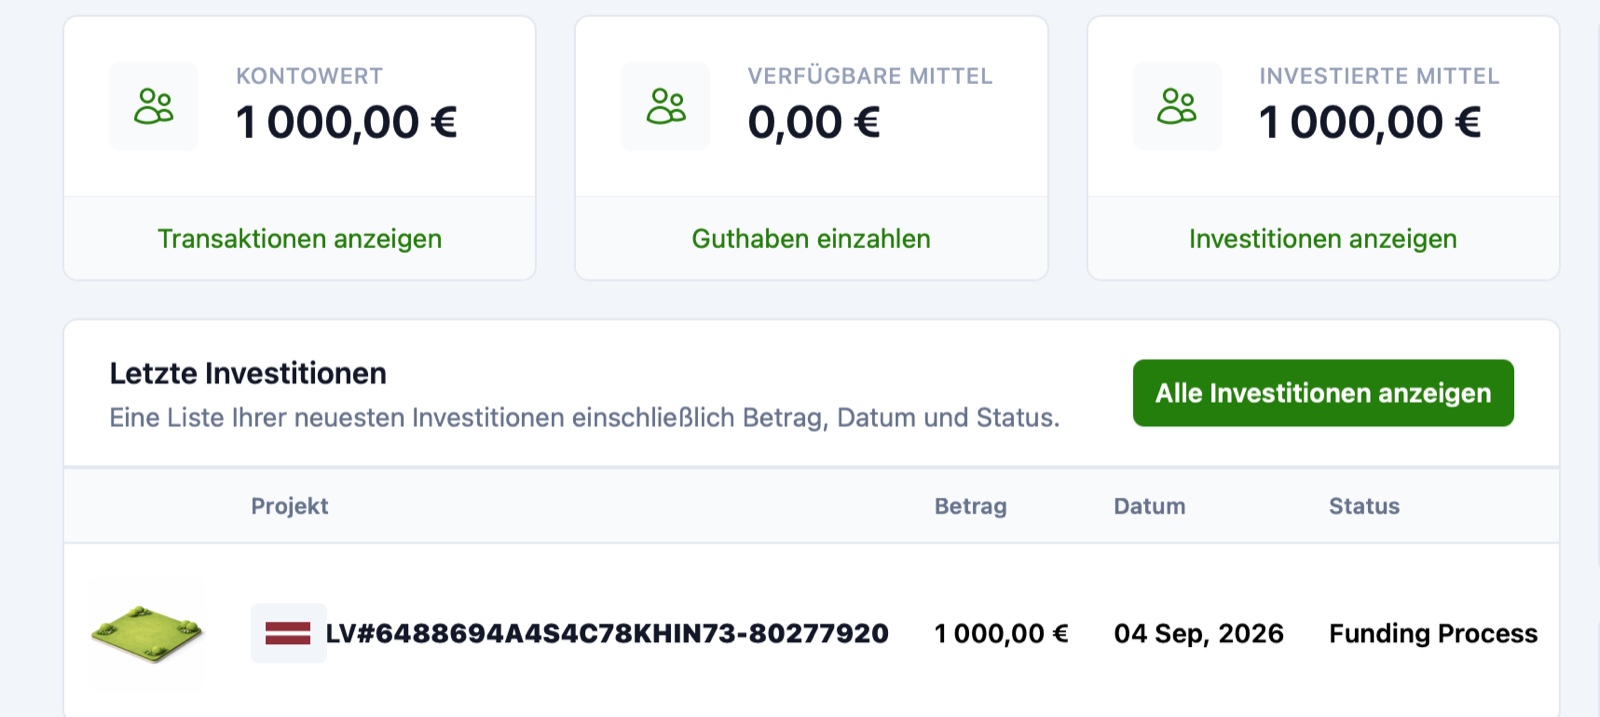
I don't just talk about the platform, I'm invested myself. I deposited €1,000 and invested it in one project – here's my dashboard:
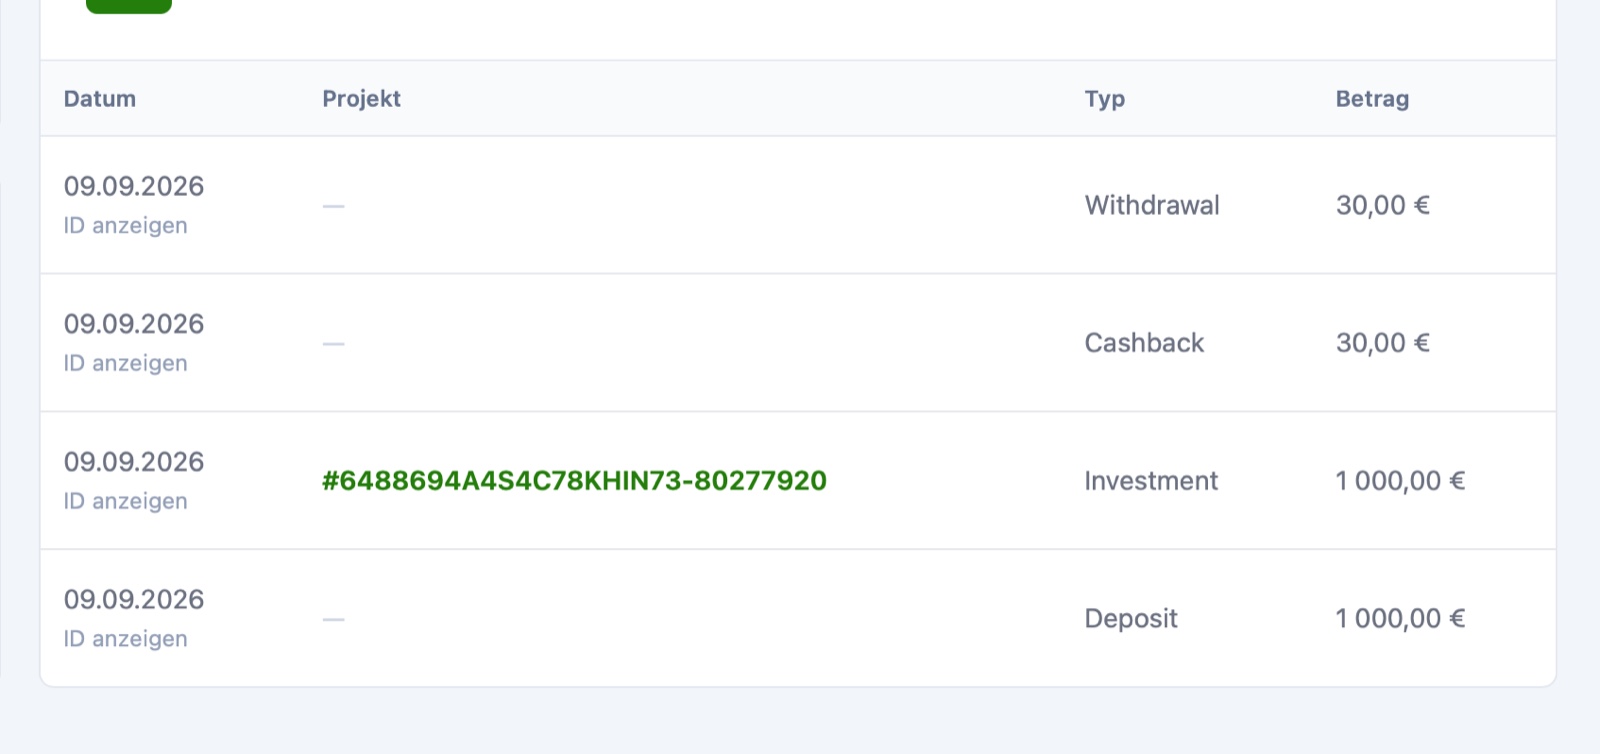
And here's the part I especially like to show, because it proves the bonus: in my transaction history you can see €30 cashback on the €1,000 investment – exactly the promised 3%. No fine print, no waiting on obscure conditions: deposited, invested, cashback credited.
The bonus: 3% cashback in the first 60 days
Which brings us to the offer: through my Digilo link* you get 3% cashback on all primary-market investments you make in the first 60 days after registration. The cashback lands in your Digilo account. For context: Digilo's public standard programme is 1% – the 3% run through the partner link. My own statement above shows it works.
My tip: only register once your starting capital is actually ready, because the 60 days run from sign-up. And check the promotion terms directly at Digilo before you start – conditions can change.
Fees
For you as an investor, investing is free. The one point to know: per the terms (10.6), Digilo may deduct a processing fee of €1 per withdrawal. Digilo lists no other ongoing fees for investors.
The downsides and risks
With a new platform, an honest look at the weak spots matters most to me:
- Very young platform. Only 4 funded projects so far – no reliable track record, and the 0.00% default rate is worth little yet.
- Latvia concentration risk. In the first year of operation, all projects are in Latvia per Digilo. If you want to spread across countries, you can't (yet).
- Little choice. With so few projects, rounds fill quickly and diversifying within Digilo is barely possible right now.
- No real secondary market. The licence does allow a "bulletin board", but there's no guarantee you can sell your share early. Plan for the full 12–36 month term.
- No buyback guarantee, no deposit insurance. In a default, only realising the collateral counts.
- The risk category is Digilo's own assessment, and the criteria are not public.
Who is Digilo right for?
- are looking for property-backed P2P loans at 9–12% interest
- want to deliberately try an ECSP-regulated platform early
- want to diversify from €150 per project and use Auto-Invest
- want to grab the 3% cashback in the first 60 days
- need a long track record and many projects to choose from
- value a buyback guarantee or a liquid secondary market
- don't want concentration risk on a single country (Latvia)
- would invest money whose loss you couldn't handle
Verdict: a solid start, but deliberately early
Digilo makes a clean, serious impression on me: ECSP-licensed, segregated client funds via Lemonway, property-backed loans with LTV up to 60%, transparent statistics and an experienced team. The 9–12% interest and the 3% cashback in the first 60 days are attractive, and my own statement shows the bonus arrives.
At the same time, Digilo is very much at the beginning. Four projects, one country, no long track record – this is an early-stage investment where you should take part with small, well-diversified money, not with your emergency fund. For me that's exactly the right role: an exciting new platform I follow with a modest amount and keep watching. If you see it the same way, you can secure the start plus cashback here: try Digilo through my link and grab 3% cashback*.
Links marked with * are partner links. If you invest through them, you support my work – at no extra cost to you; you secure the cashback. Thank you!
Frequently asked questions
Is Digilo legit and regulated?
Digilo (operated by CSP Growth Solutions SIA from Riga) has been licensed by the Bank of Latvia as a European Crowdfunding Service Provider (ECSP) under EU Regulation 2020/1503 since 16 September 2025 – licence no. 27-10/2025/222, listed as active in the ESMA register. Investor funds are held separately from company assets and processed via the French payment institution Lemonway. Important: the regulator does not vet each individual loan, there's no deposit insurance and no buyback guarantee – the credit risk stays with you.
How high is the interest on Digilo?
Digilo quotes an expected return of 9–12% per year, shown separately for each project. Across the projects funded so far, the average annual return on the statistics page is 11.44% (as of 15 September 2026). The currently open project runs at 9% interest. These rates are typical, not a hard cap.
What's the minimum investment on Digilo?
The minimum is €150 per project. Loan terms run from 12 to 36 months. For Auto-Invest, the minimum is €150 (Set & Forget) or €300 (Select & Maximize), depending on the strategy.
How safe are the loans on Digilo?
Every loan is backed by real estate or land (mortgage), with a loan-to-value (LTV) of at most 60% per Digilo. Digilo also assigns each project its own risk category. Still: there's no buyback guarantee – if a borrower defaults, the collateral has to be realised first, and a residual loss is possible. No deposit insurance applies.
How long has Digilo been around?
The Bank of Latvia licence dates from 16 September 2025, with the first blog posts in November 2025. Several P2P blogs date the start of public investing to April 2026; Digilo's own statistics count from June 2026 (the month of the first fully funded project). So the platform is still very young.
How does the Digilo cashback bonus work?
Through my partner link you get 3% cashback on all primary-market investments you make in the first 60 days after registration. The cashback is credited to your Digilo account. You can actually see it live in my own account: my €1,000 investment earned €30 cashback. (Digilo's public standard programme is 1% – the 3% run through the partner link.)
What fees does Digilo charge?
Investing itself is free for investors. Per the terms (section 10.6), a processing fee of €1 per withdrawal may be deducted. Digilo lists no other ongoing fees for investors.
What are the biggest risks with Digilo?
The platform is very new (only 4 funded projects so far) – so the 0.00% default rate carries little weight yet. There's also concentration risk: in the first year of operation, all projects are in Latvia. There's no real secondary market, no buyback guarantee and no deposit insurance. Only invest money whose total loss you could handle.
Disclaimer
⚠️ Not investment advice
All content is for information and entertainment purposes only and does not constitute investment advice, a buy recommendation or an invitation to enter into a financial product. Please do your own research and make decisions based on your personal situation and risk tolerance.
📉 Risk warning & total loss
Investments in securities and other financial instruments generally carry significant risks (e.g. price, market, currency, volatility and credit risks). A total loss of the capital invested cannot be ruled out.
📊 Returns & forecasts
All performance figures, whether historical or as a forecast/estimate, are not a reliable indicator of future results. Capital and returns are not guaranteed.
🔍 Transparency & conflicts of interest
I strictly distinguish between facts and personal estimates. Important: I am often invested in the assets discussed myself, which can create a conflict of interest.
✅ DYOR (Do Your Own Research)
All information has been compiled carefully but is non-binding, without warranty and without any claim to completeness. Please inform yourself thoroughly and consider all opportunities and risks in depth before making an investment decision.
Advertising & affiliate notice
Links marked with * are advertising or affiliate links. If you sign up or buy something through such a link, I may receive a commission – at no extra cost to you. This supports my work.