Loanch Update September 2026: Iron Reached, 14.5% Interest & Up to 3% Cashback – My Honest Review
My Loanch update: why my portfolio now sits at €3,800.88, how the loyalty programme works (Iron reached, Bronze and +0.5% from €5,000 in sight), what the up to 14.5% interest and the originators Tambadana, AhaPay and Ammana bring, how the Early Bird cashback promotion runs, that originator Wawasan Cojaya has filed an audited annual report with sharply rising numbers – and where things stand on regulation, buyback and the earlier payout delays. With all the numbers from my own account.
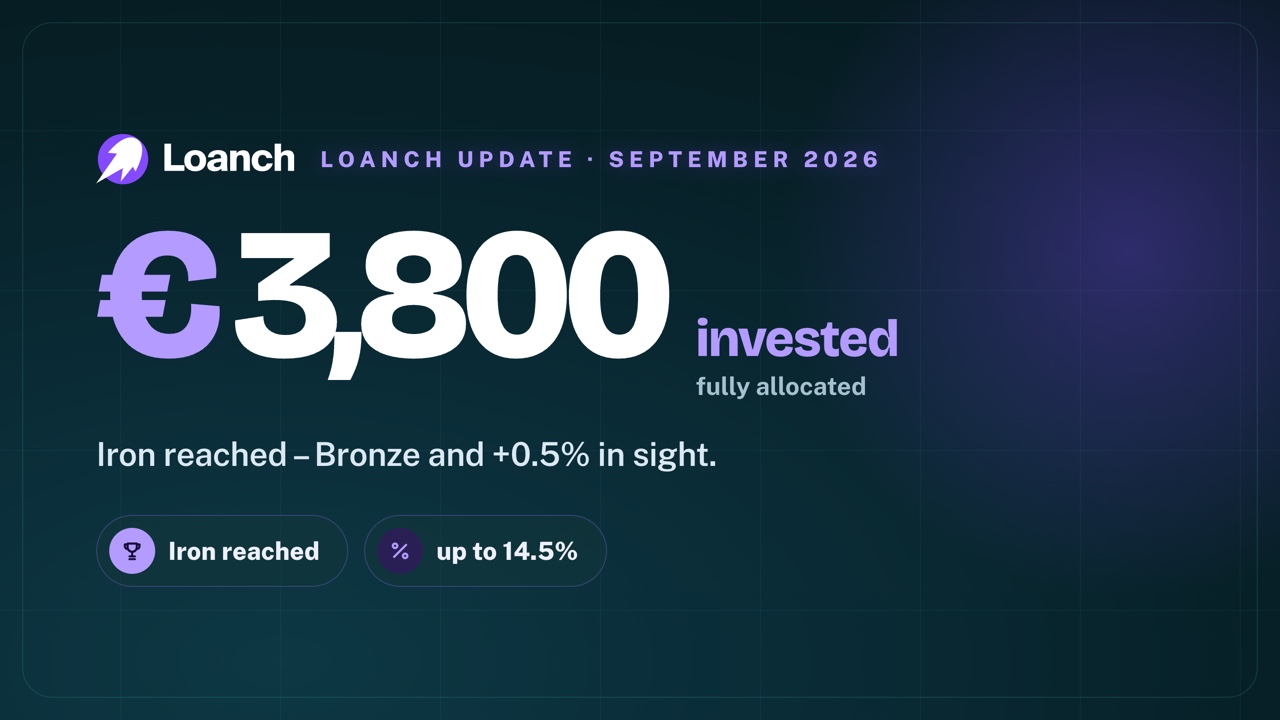
Table of contents
Time for a Loanch update. A lot has happened at the platform: my portfolio has climbed past €3,800, I've reached the first tier of the loyalty programme, there's an Early Bird cashback promotion running, the main originator has filed an audited annual report with sharply rising numbers – and in the background Loanch has moved to Croatia. In this post I take you transparently through all the news, through my own account, and through the question of how safe Loanch actually is.
As always, first the most important note: this is not investment advice and not a buy recommendation, just my personal opinion and experience. P2P investments are high-risk – only invest money whose total loss you could handle. The Loanch link is a partner link: if you use it, you support my work at no extra cost to you.
My Loanch portfolio in numbers
I'm building up my Loanch position step by step via a savings plan. It currently sits at €3,800.88 – fully invested, with €0 sitting idle:
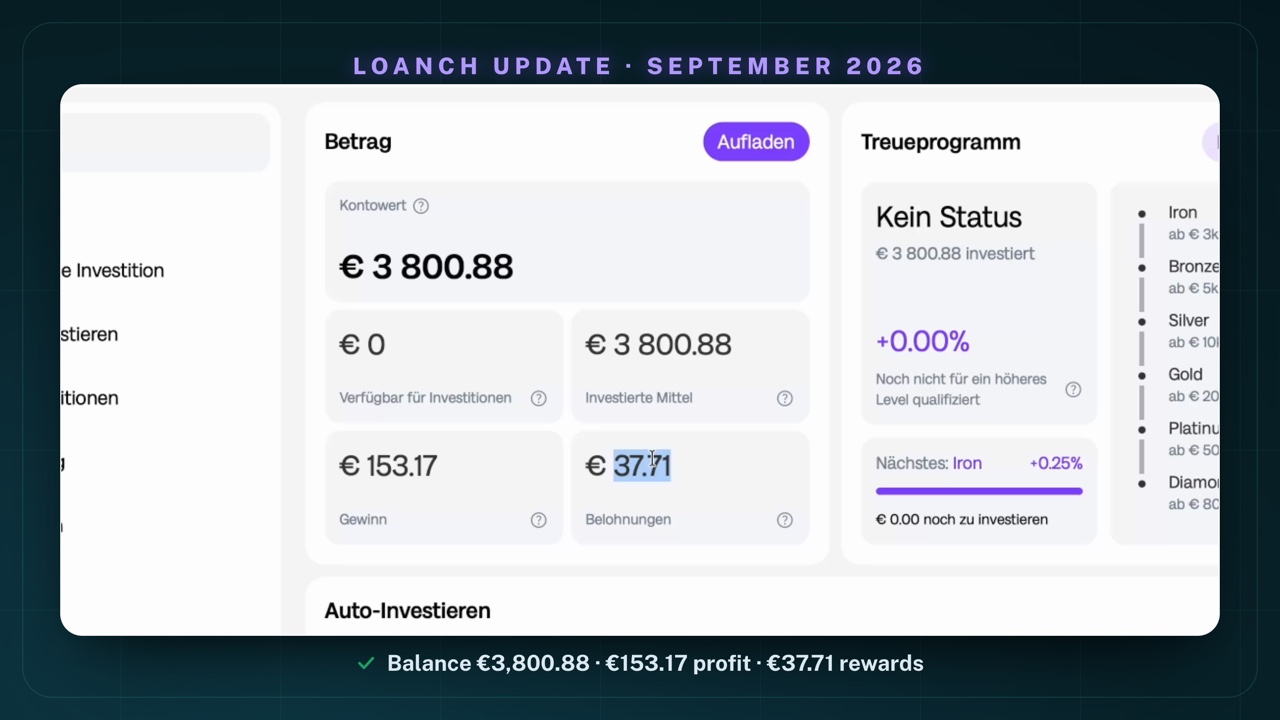
The numbers in detail: I've collected €153.17 in profit so far, plus €37.71 in rewards (from bonus and promotions). Everything that comes in is immediately reinvested via auto-invest – that's why "available for investment" shows a flat €0 and I have virtually no cash drag.
What is Loanch, actually?
Loanch is a P2P platform through which you invest in consumer loans – mainly from Malaysia. The key facts from the homepage:
- up to 14.5% APR from consumer loans – currently the highest rate on the platform
- €20 bonus for your first investment
- a 30-day buyback guarantee once a loan is 30 days overdue (Loanch cites 60 days as the market average)
- 0% fees, no hidden costs
- a loyalty programme with up to 1.5% extra interest
The platform in numbers: over €112m in loans funded, more than 16,000 investors and around €1.8m in interest paid out (as of the last monthly update; the homepage now even shows around €119m). Loanch recently launched its own statistics page with historical charts and insight into overdue investments – a plus for transparency.
The loyalty programme: Iron reached, Bronze in sight
This is the most exciting change for me. Loanch's loyalty programme rewards bigger portfolios with an interest bump – across six tiers:
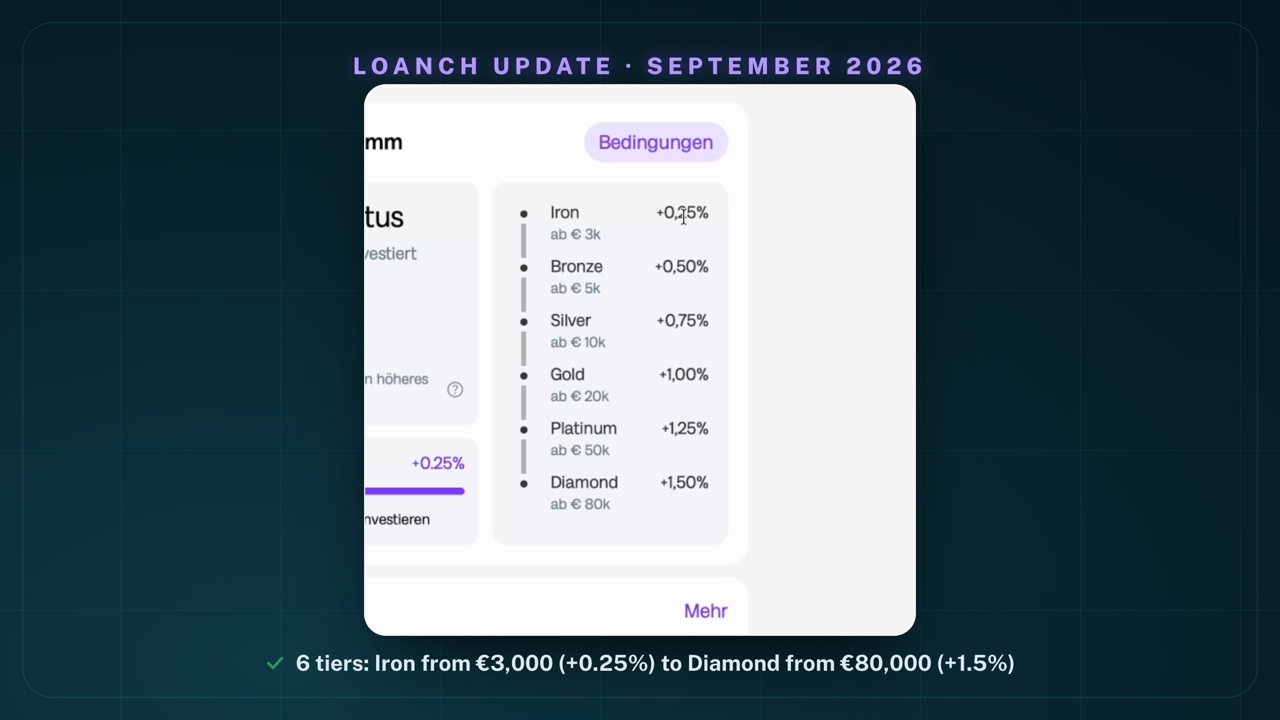
With my €3,800.88 I've already crossed the Iron threshold (from €3,000). Yet the dashboard still shows "No status" and +0.00% – and this is important to understand: you have to hold the threshold for 90 continuous days, then the tier is granted. So the threshold is reached, the tier is just still running through that 90-day period.
My real target, though, is the next tier: Bronze starts at exactly €5,000 – and brings +0.5%. Iron only brings +0.25%, so from Bronze my bonus doubles. A few details worth knowing: only the highest tier reached ever counts, the extra interest applies only to new investments from the moment the tier is granted, and if your portfolio drops below the threshold there's a 7-day grace period before you're downgraded.
Up to 14.5% interest – and the originators
On the primary market I currently see Tambadana loans at around 14.5% interest with short terms:
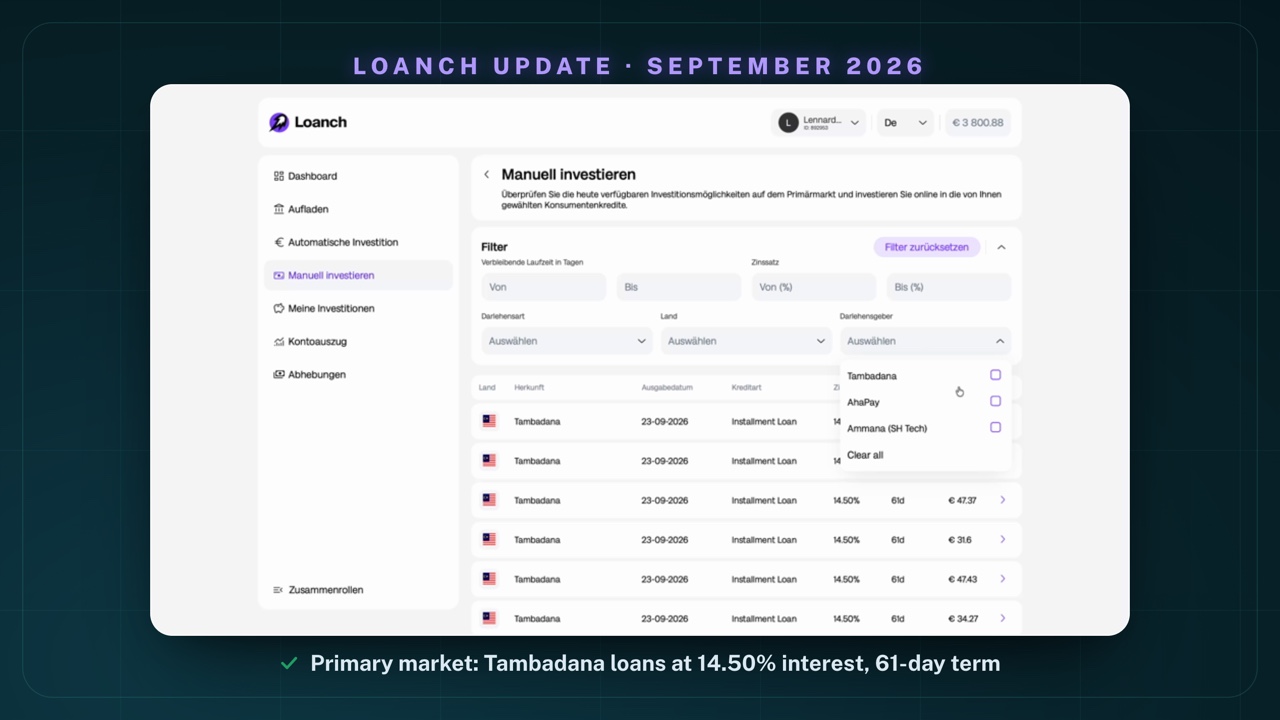
Behind the loans are three originators, and it's worth telling them apart:
- Tambadana (Wawasan Cojaya Sdn. Bhd., Kuala Lumpur) – the big originator, avg 13.82% interest, over 866,000 loans issued.
- AhaPay (Aharetail Solutions, Kuala Lumpur) – a BNPL provider (buy now, pay later), avg 11.00% interest.
- Ammana (SH Tech) – avg 13.29% interest, but according to Loanch currently not issuing any new loans.
All three offer a buyback guarantee from 30 days overdue. If you read "only 11%" somewhere: that's AhaPay's average rate – the top of the platform is 14.5%.
The Early Bird cashback promotion
Loanch is running a cashback promotion – tiered by when you invest in September:
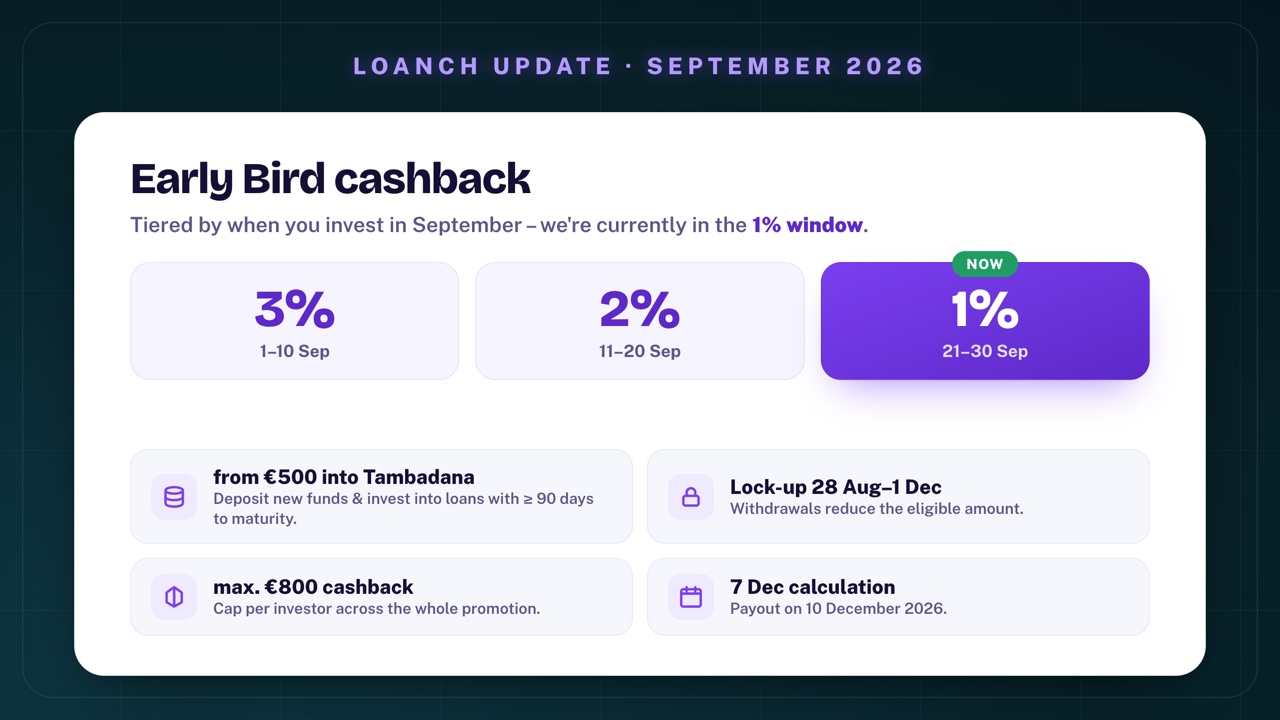
- Tiers: 3% (1–10 Sep), 2% (11–20 Sep), 1% (21–30 Sep) – so we're currently in the 1% window.
- Condition: deposit at least €500 in new funds and, within the same window, invest into Tambadana loans with ≥ 90 days to maturity.
- Lock-up: withdrawals between 28 August and 1 December 2026 reduce the eligible amount – if you want the full cashback, leave the money in place until 1 December.
- Cap: a maximum of €800 cashback per investor, calculated on 7 December, paid out on 10 December.
Two things I want to state clearly: the promotion only applies to Tambadana on the primary market, and the lock-up is a real condition, not a formality. Always check the current terms directly with Loanch before you start.
Wawasan Cojaya: an audited annual report
One point that pleasantly surprised me: the main originator Wawasan Cojaya has filed an audited annual report for 2025 – with an unqualified audit opinion. And the numbers have grown strongly:
- Revenue: from around €5.5m (2024) to €36.6m (2025) – 6.7 times as much.
- Net profit: from around €0.5m to €1.9m – more than four times.
- Net loan receivables: from around €4.6m to €22.1m.
An audited report with a clean opinion is not a given in the P2P space – that's a real plus. But it doesn't replace regulation of the platform itself (more on that in a second).
How safe is Loanch?
Now to the honest part. Loanch has some good safety features – but also clear weaknesses you need to know about:
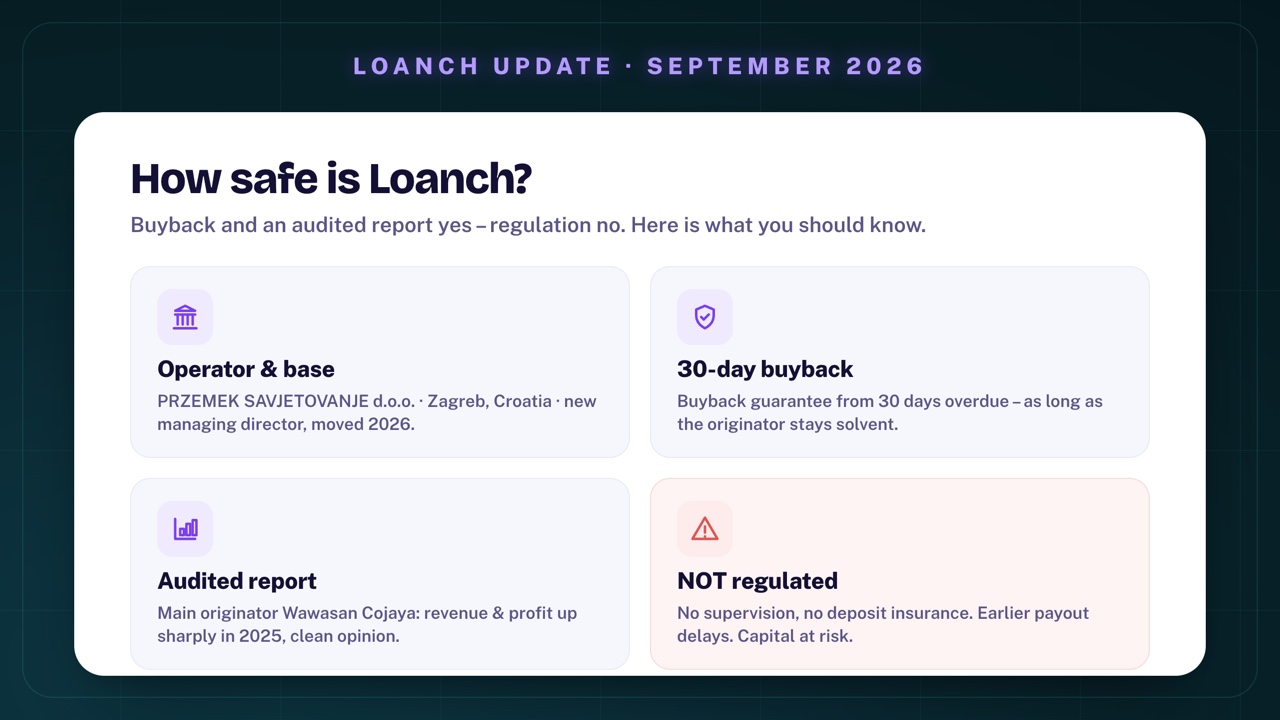
The most important point first: Loanch is not regulated. The platform even states this itself in the footer – the services are explicitly not offered to residents of jurisdictions where a local authorisation or licence would be required. There's no financial supervision of the platform and no deposit insurance. The operator is PRZEMEK SAVJETOVANJE d.o.o. in Zagreb, Croatia.
New since the last video: the move to Croatia, a new managing director (Przemysław Paweł Januszaniec, 25+ years in consumer finance), and founder Nik Sinickis is now Head of Product. On the positive side are the 30-day buyback guarantee across all originators and Wawasan Cojaya's audited report. But: the buyback only works as long as the originator stays solvent, and the credit risk remains with you.
Being fully open about it: there were payout delays between December and February that some investors felt. That's exactly why I deliberately keep my Loanch position small – more on that in the verdict.
Who is Loanch right for?
- want up to 14.5% interest from consumer loans
- want to raise your rate step by step via the loyalty programme
- value the 30-day buyback guarantee and 0% fees
- want to grab cashback and the €20 bonus as a new customer
- need a regulated platform with real deposit insurance
- must be able to withdraw your money instantly at any time
- can't bear the default risk of Malaysian consumer loans
- are put off by the earlier payout delays
My plan and verdict
My plan is clear: I'll keep building up via the savings plan to €5,000. That gets me to the Bronze tier and doubles my loyalty bonus to +0.5%. At the same time, those €5,000 are only about 1% of my total portfolio – a deliberately small, clearly capped position on a platform that isn't regulated and that I watch closely after the earlier delays.
Bottom line, Loanch is on a good run right now: up to 14.5% interest, an attractive loyalty programme, an ongoing cashback promotion, an audited report from the main originator and more transparency through the new statistics page. The risks remain (no regulation, no deposit insurance, capital at risk, earlier payout delays), but as a small, high-yield add-on Loanch fits into my portfolio. If you want to try Loanch, best to grab the €20 bonus and the cashback promotion right away: go to Loanch through my link*.
Links marked with * are partner links. If you invest through them, you support my work – at no extra cost to you. Thank you!
Frequently asked questions
Is Loanch regulated?
No. Loanch states it itself in the footer: the services provided via the platform are not offered to residents of jurisdictions where such services require a local authorisation or licence. The operator is PRZEMEK SAVJETOVANJE d.o.o., based in Zagreb, Croatia. There's no financial supervision of the platform and no deposit insurance – your capital is at risk.
How high is the interest on Loanch?
Loanch advertises up to 14.5% APR from consumer loans – currently the highest rate on the platform. Depending on the originator, the average rate is around 11% (AhaPay), 13.29% (Ammana) and 13.82% (Tambadana). Via the loyalty programme you can add up to 1.5 percentage points on top, depending on portfolio size. All rates are fixed but not guaranteed.
How does the Loanch loyalty programme work?
The loyalty programme has six tiers based on your invested portfolio: Iron from €3,000 (+0.25%), Bronze from €5,000 (+0.50%), Silver from €10,000 (+0.75%), Gold from €20,000 (+1.00%), Platinum from €50,000 (+1.25%) and Diamond from €80,000 (+1.50%). You have to hold the threshold for 90 continuous days, then the tier is granted. The extra interest applies to new investments from the moment the tier is granted. Only the highest tier reached ever counts.
How does the Early Bird cashback promotion work?
The cashback is tiered: 3% from 1–10 September, 2% from 11–20 September and 1% from 21–30 September. Conditions: at least €500 in new funds, invested within the same window into eligible Tambadana loans with at least 90 days to maturity. Withdrawals between 28 August and 1 December 2026 reduce the eligible amount. Maximum €800 cashback per investor, calculated on 7 December, paid out on 10 December. Always check the terms directly with Loanch – deadlines and details can change.
Is there a buyback guarantee on Loanch?
Yes, all three originators offer a buyback guarantee once a loan is 30 days overdue – Loanch cites 60 days as the market average. Important: the buyback only kicks in as long as the respective originator is solvent. You ultimately carry the credit risk, and the platform itself is not regulated. A buyback guarantee is no substitute for deposit insurance.
Who is behind Loanch?
The operator is PRZEMEK SAVJETOVANJE d.o.o. in Zagreb, Croatia (reg. no. 49535909257). Loanch recently moved to Croatia, the new managing director is Przemysław Paweł Januszaniec (25+ years in consumer finance), and founder Nik Sinickis is now Head of Product. The platform reports over €112m in loans funded, more than 16,000 investors and around €1.8m in interest paid out.
Disclaimer
⚠️ Not investment advice
All content is for information and entertainment purposes only and does not constitute investment advice, a buy recommendation or an invitation to enter into a financial product. Please do your own research and make decisions based on your personal situation and risk tolerance.
📉 Risk warning & total loss
Investments in securities and other financial instruments generally carry significant risks (e.g. price, market, currency, volatility and credit risks). A total loss of the capital invested cannot be ruled out.
📊 Returns & forecasts
All performance figures, whether historical or as a forecast/estimate, are not a reliable indicator of future results. Capital and returns are not guaranteed.
🔍 Transparency & conflicts of interest
I strictly distinguish between facts and personal estimates. Important: I am often invested in the assets discussed myself, which can create a conflict of interest.
✅ DYOR (Do Your Own Research)
All information has been compiled carefully but is non-binding, without warranty and without any claim to completeness. Please inform yourself thoroughly and consider all opportunities and risks in depth before making an investment decision.
Advertising & affiliate notice
Links marked with * are advertising or affiliate links. If you sign up or buy something through such a link, I may receive a commission – at no extra cost to you. This supports my work.