€10,000 at Debitum: My Update – and Why I'm Now Moving Into Debitum Flow
Debitum is one of my biggest P2P platforms: €10,000 invested, 10.65% XIRR and solid interest every month. In this update I show you my account in detail, my interest month by month, how Debitum Flow works with 8% and daily payouts – and why I'm gradually shifting out of the long-term notes into liquid Flow. Plus: 1% cashback via my link.
Table of contents
- My Debitum account in detail
- My interest month by month
- The classic notes: high interest, but locked up
- Debitum Flow: the liquidity feature
- My plan: shifting over step by step
- The loyalty program: Flow counts toward your tier, but earns no interest bonus
- Regulated and supervised – the difference from the competition
- 1% cashback via my link
- Conclusion
- FAQ
Time for a quick update on one of my biggest P2P investments: Debitum. I have just under €10,000 sitting there, and with Debitum Flow there's now a new, liquid product that I'm testing myself. In this post I'll show you my account in detail, how much interest I earn month by month, how the classic notes compare to Flow – and why I'm gradually shifting out of the long-term notes into Flow.
First, as always, the most important note: this is not investment advice and not a buy recommendation, just my personal opinion and my own investment. P2P loans are a risky asset class – defaults, platform risk and a total loss of your capital are all possible. You're responsible for your money, I'm responsible for mine – always make your own decision. The Debitum link is a partner link: if you use it, you support my work and nothing gets more expensive for you – on the contrary, you lock in the cashback.
My Debitum account in detail
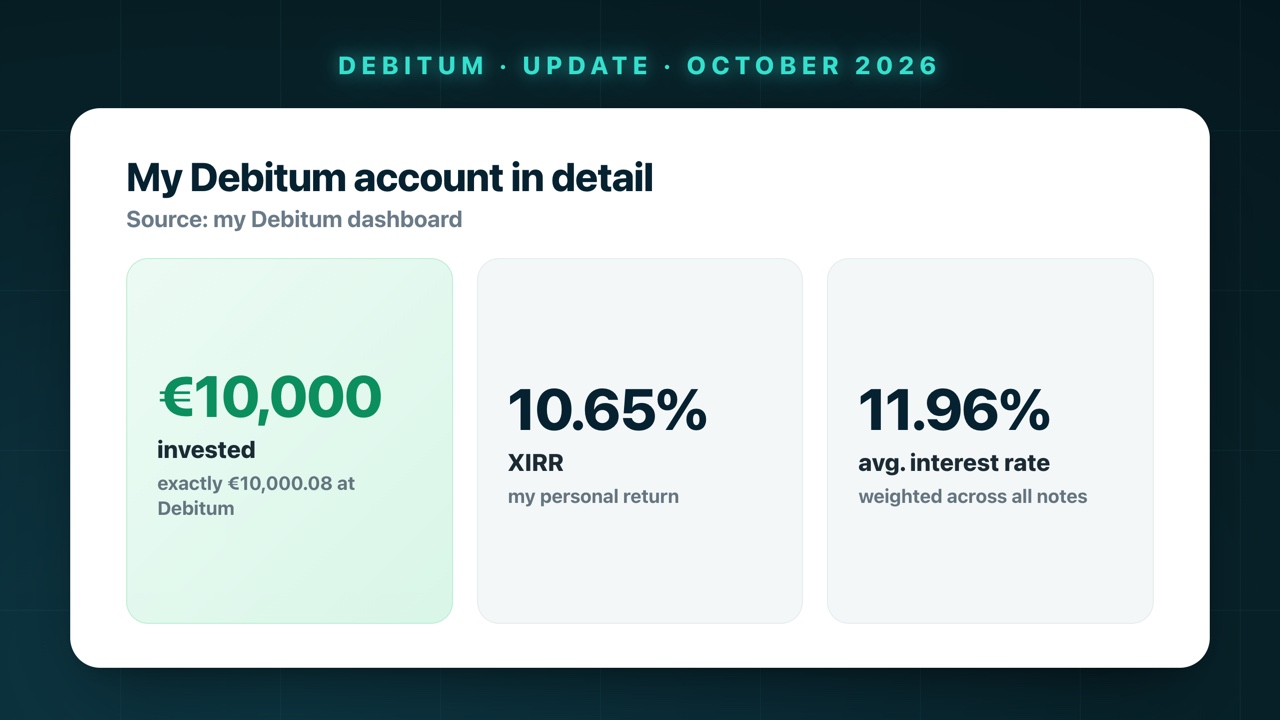
Let's start with the account. I'm currently invested with exactly €10,000.08 at Debitum. My personal return (XIRR) is 10.65%, and the weighted average interest rate across all notes is around 11.96%.
Most of that has so far been in the classic projects – individual loans with a fixed term. More on that in a moment, because this is exactly where my reshuffle comes in.
My interest month by month
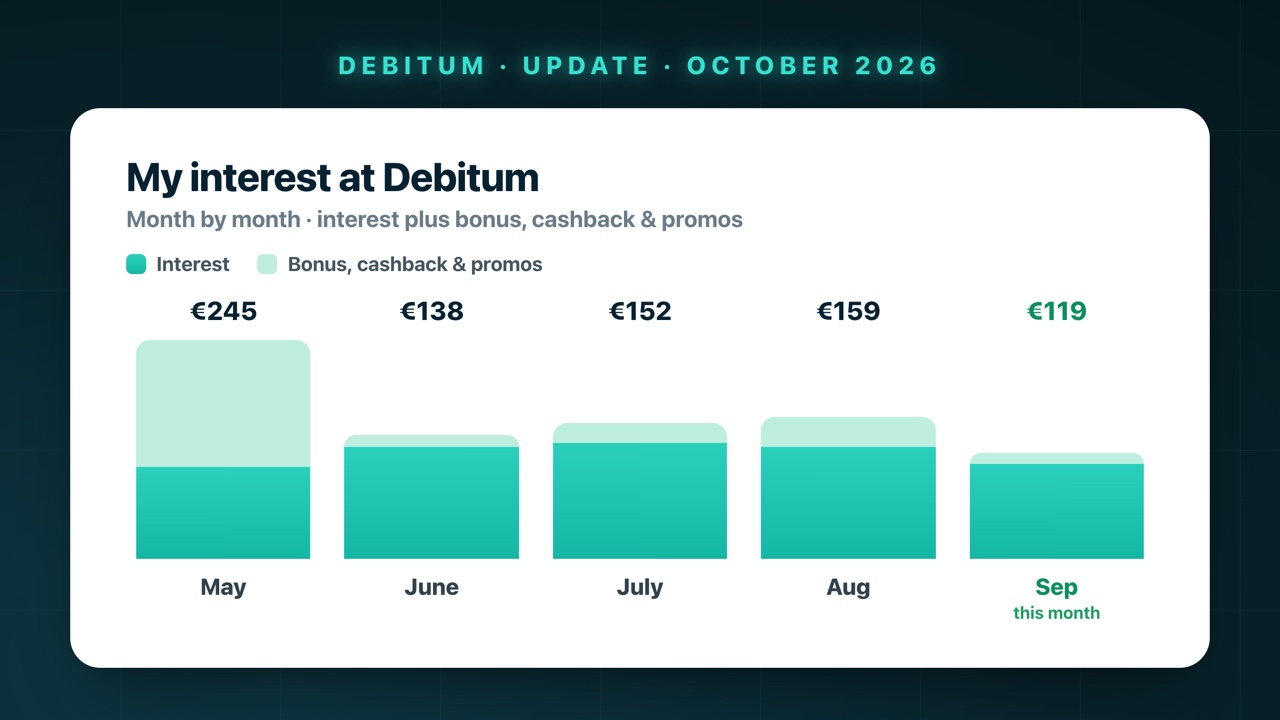
Now to the most exciting part – the passive income. Debitum pays me a solid amount every month now. Here's an overview of the recent months, split into pure interest and additional bonus, cashback and promo payments:
Two things matter to me here:
- The pure interest is surprisingly stable at around €105 to €130 a month. That's the solid foundation.
- The spikes almost always come from one-off promotions. May looks huge at over €244, for example – but only €102.86 of that was actual interest, the rest a one-time promo bonus. In September it came to €118.81: €106.05 interest plus €12.76 in loyalty and referral bonuses.
For me that means: I can rely on a dependable interest base, and the bonuses are the nice extra boost on top – but not something I count on long term.
The classic notes: high interest, but locked up
So far I've been invested at Debitum almost exclusively in the classic notes – individual loan projects with a fixed term. The upside is obvious: here I earn up to 15% interest plus 2% from my loyalty level, so up to 17%. My next repayments are lined up like this, for example: €200 in 4 days, €100 in 10 days, around €30 in 37 days and even over €1,000 in 68 days.
The catch: I'm tied to the terms, and especially with the long-running notes that carry the high interest, my money is quickly locked for three years or more. And Debitum currently has no secondary market – so I can't just sell my notes early, I have to wait until they mature. Higher return in exchange for less flexibility – that simply comes with these projects.
Debitum Flow: the liquidity feature
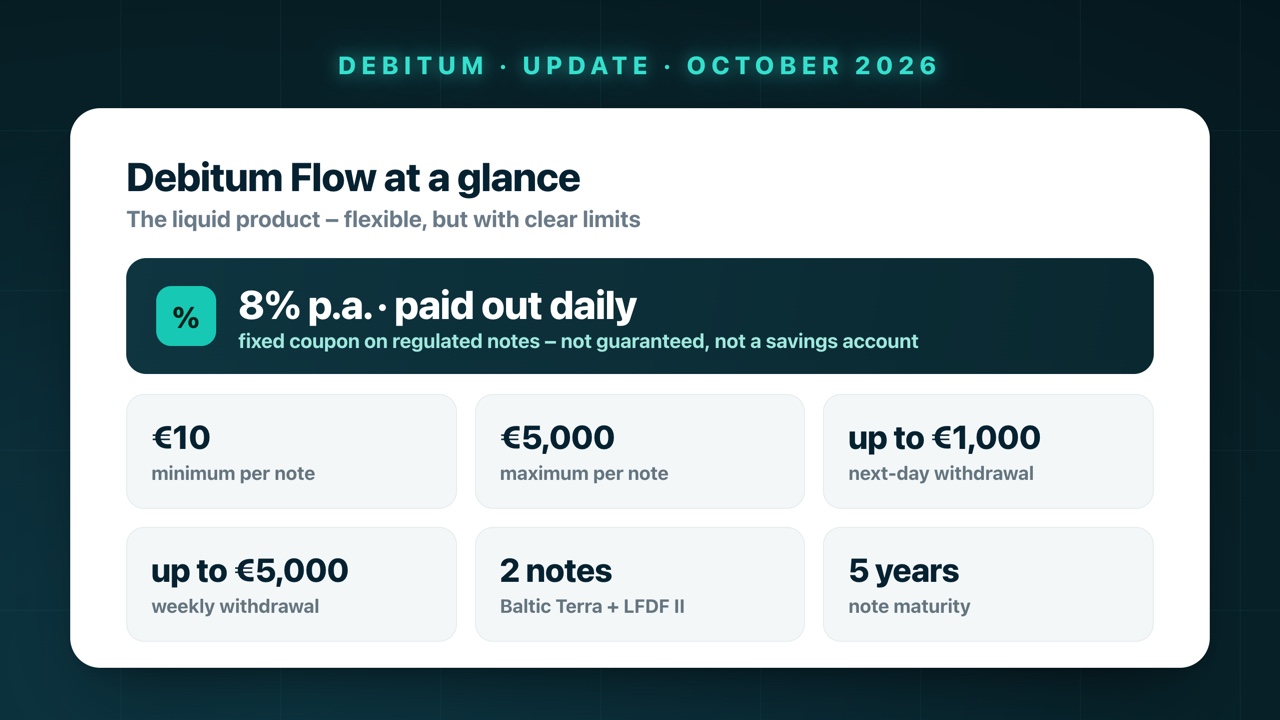
Debitum Flow solves exactly this flexibility problem. Flow is a very liquid product: instead of individual loans you invest in regulated notes and earn 8% p.a. as a fixed coupon, paid out daily. In return you can pull your money back out almost anytime – at least part of it.
Here's how it works in practice:
- Two notes to choose from: currently Baltic Terra and the Latvian Forest Development Fund II (LFDF II). You can use both or just one – it's up to you.
- Minimum €10 per note, maximum €5,000 per note – so up to €10,000 in total across two notes.
- Withdrawals: up to €1,000 next day, up to €5,000 per week (this weekly amount includes the €1,000, so it's not additional).
- Interest comes daily: I put in just under €200 as a test and I see the small credits trickle in every day – a few cents per day from each note.
An honest point that belongs here: the fast withdrawal is not guaranteed. It works as long as the liquidity is there – as long as not everyone wants out at once. If needed, a partial withdrawal is made, and the remainder keeps its place in the queue and continues to earn interest. But that's not a Debitum-specific problem – it's the same with flexible products like Bondora Go & Grow: liquidity yes, guarantee no. I wrote up how Flow works in detail and how it compares to the competition in my full Debitum Flow post.
My plan: shifting over step by step
And that brings me to the question on my mind the most right now: Am I moving everything over? Not everything – but a decent chunk.
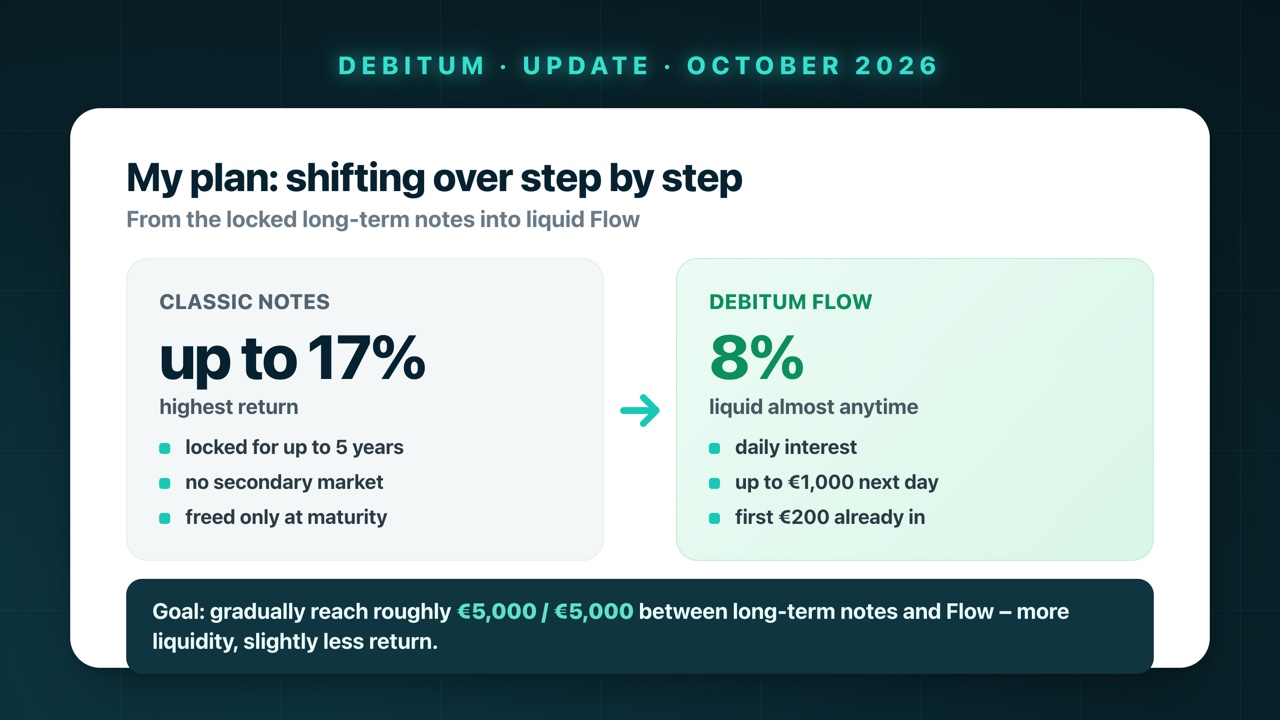
My approach is simple: whenever capital flows back from my classic notes – the €200 in four days, the €100 in ten days and so on – I put a growing share of it not back into long-term notes, but into Flow. That way I shift a few thousand euros over time from the locked product into the liquid one, without having to sell anything early (which wouldn't be possible without a secondary market anyway).
My goal is an allocation of roughly €5,000 / €5,000 between long-term notes and Flow. Sure, at 8% Flow pays less return than the long-term notes at up to 17%. But I like liquidity – and 8% for a product I can get out of almost anytime is still very strong in my book. If Debitum ever introduces a secondary market, I'd do the math again.
The loyalty program: Flow counts toward your tier, but earns no interest bonus
One more word on the loyalty program, because it matters for the reshuffle. Debitum has four tiers that raise your interest on other investments:
| Tier | Invested | Loyalty bonus |
|---|---|---|
| New Investor | under €6,000 | – |
| Investor | €6,000–24,999 | +0.50% p.a. |
| Investor Pro | €25,000–49,999 | +1.00% p.a. |
| Investor Elite | from €50,000 | +2.00% p.a. |
The key catch: the loyalty bonus does not apply to Flow itself – the interest bonus only counts for primary-market investments made via the normal "Invest" page. But: your Flow balance does count toward your tier and so helps you reach a higher loyalty level (and thus more bonus on your other Debitum notes). So moving into Flow doesn't cost me my tier.
Regulated and supervised – the difference from the competition
What I particularly value about Debitum: the platform has been licensed as an investment broker (investment firm) since September 2021 and is supervised by the Bank of Latvia (Latvijas Banka) under MiFID II. On top of that, an investor compensation scheme of up to 90% (max. €20,000) applies if Debitum can't return funds or financial instruments due to insolvency, fraud or misconduct.
One point I put a bit too broadly in the video and want to correct here: I said that "Go & Grow and Monefit aren't regulated." That's not quite right – the groups behind them (Bondora and Creditstar) are indeed supervised as consumer lenders. The decisive difference is a different one: the investment products Go & Grow and SmartSaver themselves are not regulated financial instruments, and – unlike at Debitum – no investor compensation scheme covers them. That is the real advantage of Debitum, and I wanted to lay it out cleanly.
Despite the regulation, the flip side remains: Flow is not a savings account, there's no deposit insurance, your capital is not guaranteed, and early withdrawal is within limits and not guaranteed. In the end, we're still investing in loan packages.
1% cashback via my link
If you want to try Debitum yourself: via my Debitum link* you secure 1% cashback on your investments in the first 30 days after registration. The bonus runs automatically through the link, no voucher code needed. As always: check the current promo terms directly with Debitum before you sign up. For transparency: this is a referral link – if you sign up through it, I get a small commission, and it doesn't cost you more. On the contrary, you get the extra cashback you otherwise wouldn't.
Conclusion
Debitum remains one of my most important P2P platforms: €10,000 invested, 10.65% XIRR, a stable interest base of a good €100 a month and, with the investor protection, a regulatory framework the flexible competition doesn't offer in this form. What I find especially interesting right now is Debitum Flow – not as a replacement for the high-yield long-term notes, but as a liquidity building block that I'm moving into step by step.
My plan for the coming months: increasingly let returning capital flow into Flow and steer toward a mix of locked notes and liquid Flow. If you want to try Debitum, it's best to lock in the cashback right away: try Debitum via my link and take the 1% cashback*.
Do you already hold Debitum or Debitum Flow – and how do you weigh return against liquidity? Let me know in the comments, I read and answer everything.
Links marked with * are partner/affiliate links. If you use them, you support my work – at no extra cost to you, and you secure the cashback. Thank you!
Frequently asked questions
How much has Lennard invested at Debitum?
Right now exactly €10,000.08 sits in my Debitum account, mostly in classic notes. My personal return (XIRR) is 10.65%, and the weighted average interest rate across all notes is around 11.96%. That makes Debitum one of my biggest P2P platforms.
How much interest does Debitum pay per month?
The pure interest is stable at around €105 to €130 a month. In September it came to €118.81 (€106.05 interest plus €12.76 in loyalty and referral bonuses). Some months are higher thanks to promo bonuses – in May it was over €244 including a one-off promotion.
What is Debitum Flow and how does it work?
Debitum Flow is Debitum's flexible, liquid product: 8% p.a. as a fixed coupon on regulated notes, paid out daily. You can withdraw up to €1,000 next day and up to €5,000 per week (the weekly amount includes the €1,000). The minimum investment is €10 per note, the maximum €5,000 per note – currently across two notes (Baltic Terra and LFDF II).
Why is Lennard moving into Debitum Flow?
The classic notes pay up to 17% interest, but my money is locked for several years – and Debitum has no secondary market yet. Flow offers less return at 8%, but almost anytime liquidity. I let returning capital flow into Flow step by step and I'm aiming for roughly a €5,000 / €5,000 split between long-term notes and Flow. The first €200 are already in.
Is Debitum regulated and safe?
Debitum has been licensed as an investment broker (investment firm) since September 2021 and is supervised by the Bank of Latvia (Latvijas Banka) under MiFID II. An investor compensation scheme of up to 90% (max. €20,000) applies. Even so: it is not a savings account, there is no deposit insurance, your capital is not guaranteed, and early withdrawal is not guaranteed.
How do I get the Debitum cashback bonus?
Via my partner link you secure 1% cashback on your investments in the first 30 days after registration. The bonus runs automatically through the link, no code needed. Still, check the current promo terms directly with Debitum before you sign up.
Disclaimer
⚠️ Not investment advice
All content is for information and entertainment purposes only and does not constitute investment advice, a buy recommendation or an invitation to enter into a financial product. Please do your own research and make decisions based on your personal situation and risk tolerance.
📉 Risk warning & total loss
Investments in securities and other financial instruments generally carry significant risks (e.g. price, market, currency, volatility and credit risks). A total loss of the capital invested cannot be ruled out.
📊 Returns & forecasts
All performance figures, whether historical or as a forecast/estimate, are not a reliable indicator of future results. Capital and returns are not guaranteed.
🔍 Transparency & conflicts of interest
I strictly distinguish between facts and personal estimates. Important: I am often invested in the assets discussed myself, which can create a conflict of interest.
✅ DYOR (Do Your Own Research)
All information has been compiled carefully but is non-binding, without warranty and without any claim to completeness. Please inform yourself thoroughly and consider all opportunities and risks in depth before making an investment decision.
Advertising & affiliate notice
Links marked with * are advertising or affiliate links. If you sign up or buy something through such a link, I may receive a commission – at no extra cost to you. This supports my work.