Revest Update October 2026: €1,559 in My Account, Up to 6% Cashback & My First Two Late Loans
My Revest update for October: I have added another €250 and now have more than €1,500 invested – account value €1,559.01. I show you the current platform statistics (€13.38m of acquired claims, 824 users), the new cashback campaign with up to 6% and the choice between Instant and Flexible, my portfolio settings with short-term loans, my sales on the secondary market – and my first two late loans, where the buyback is now running. And honestly: Revest is not regulated – which is why €5,000 is my limit.
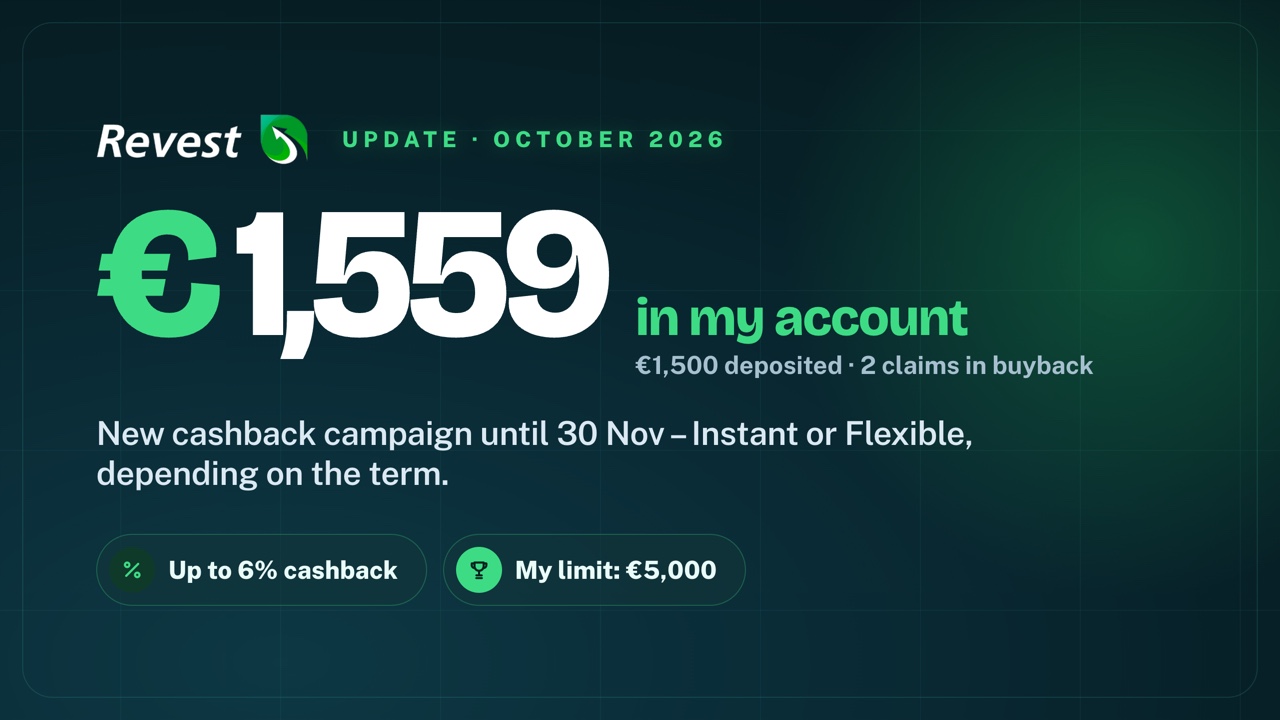
Table of contents
Two months ago I started my investment on the platform Revest. I have now actually topped up again and have more than €1,500 invested by now. In this post we look at my investment, go through the current statistics – and above all the current, strong cashback campaign, which does need a bit of explaining.
As always, the most important thing first: this is not investment advice and not a buy recommendation, just my personal opinion and my personal investments. I am responsible for my money, you are responsible for yours. P2P loans are high-risk – only invest money whose total loss you could handle, and make your own decisions. The Revest link is a referral link: if you use it, I receive a small commission, and it does not cost you anything extra.
Revest in numbers: €13.38m of acquired claims
First of all, let's look at Revest's current statistics. They share them very transparently on their website. The platform only launched in December 2025, so it is not even a year old – and you can see the development quite well.
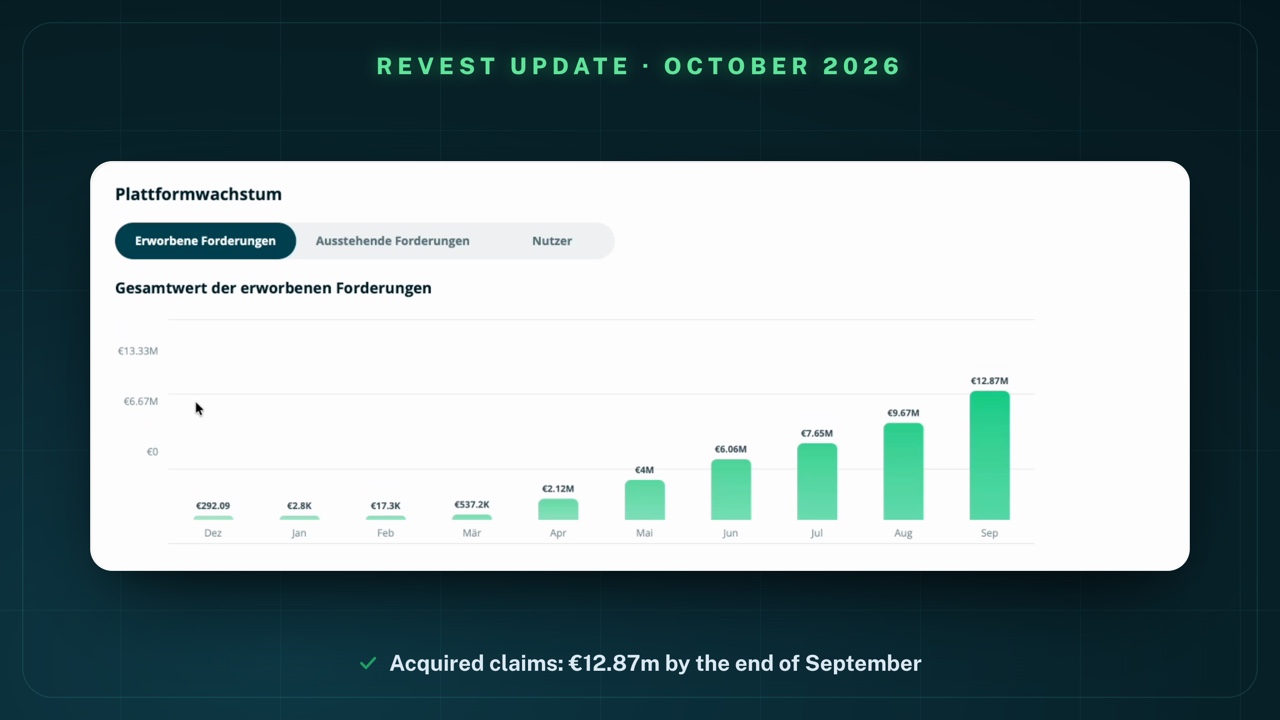
This is the total value of acquired claims: by the end of September it was already €12.87m. If we click on "outstanding claims" – which is of course far more relevant – we are at €3.95m:
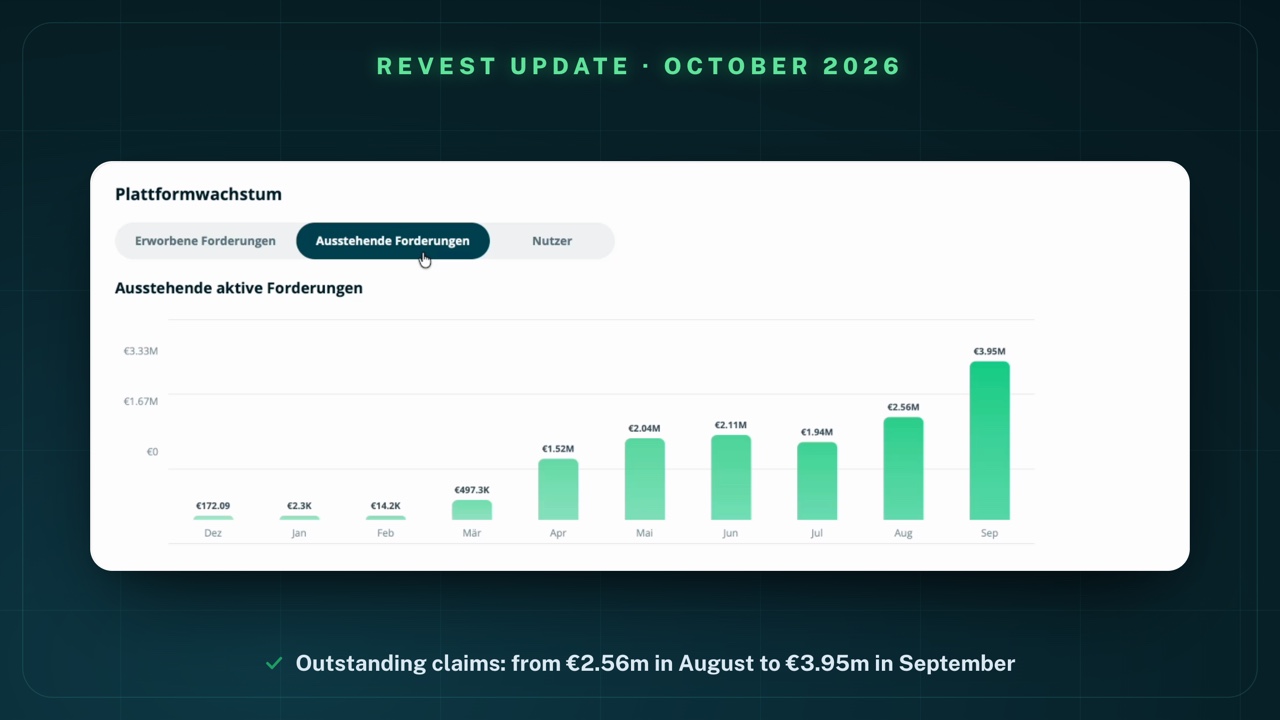
From August (€2.56m) to September that really was a huge jump. And with the users, too, we can see that things are moving along nicely – especially in the last month, from 629 to 803:
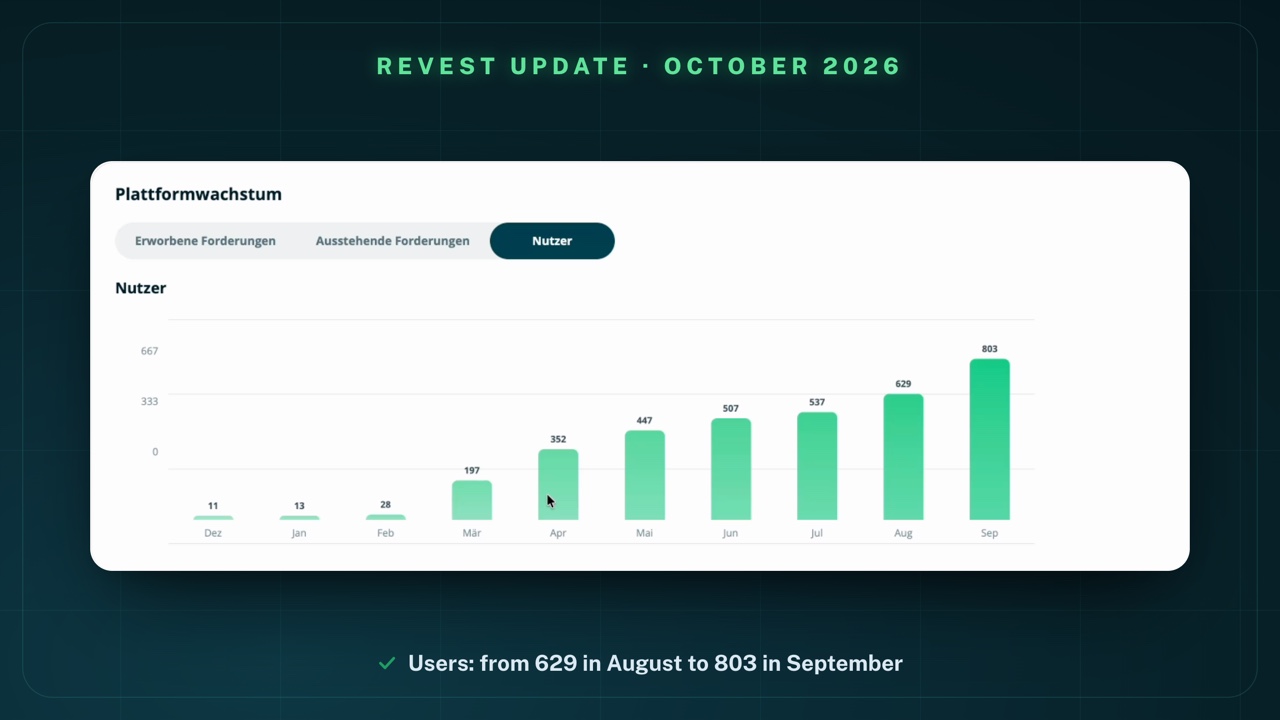
The charts end with September. The tiles below show the current figures, as of my recording on 6 October 2026:
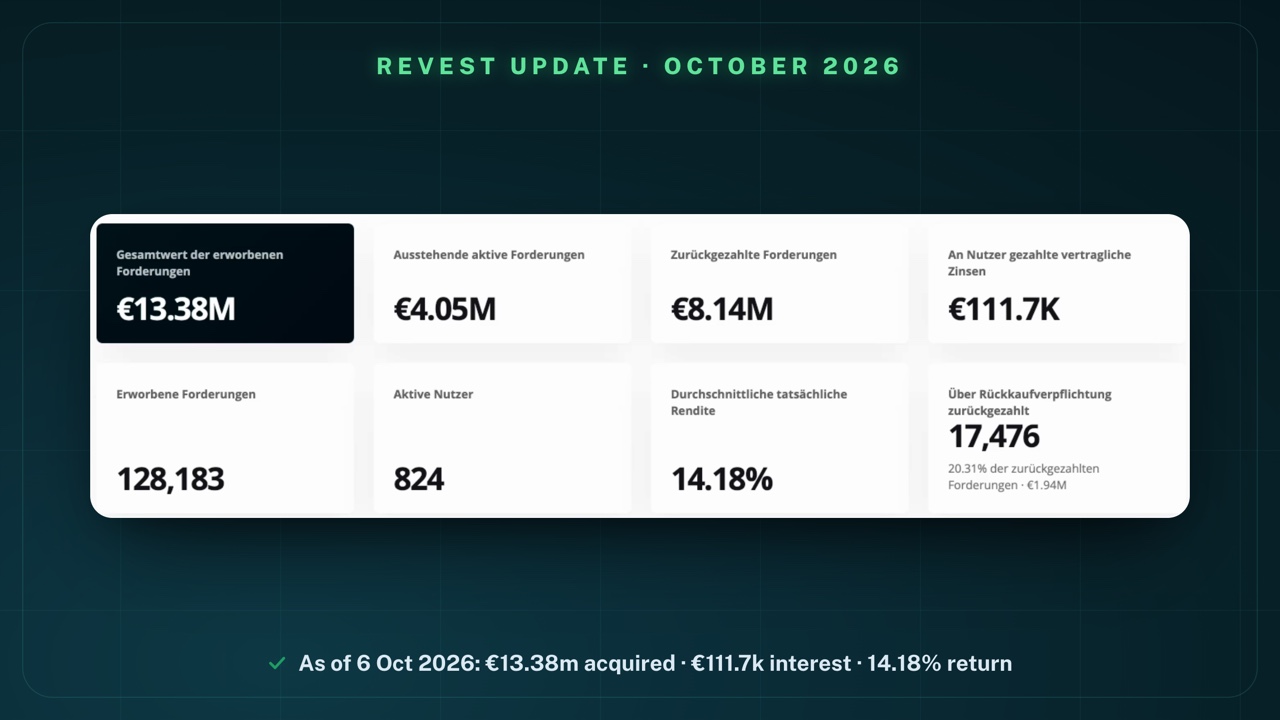
- Total acquired claims: €13.38m
- Outstanding active claims: €4.05m
- Interest paid to users: €111.7k already
- Active users: 824
- Average actual return: 14.18%
So it certainly reads well. How good the platform really is will of course only become clear over time.
The cashback campaign: up to 6% until 30 November
Then let's get to the current cashback campaign: from 5 October to 30 November 2026 you can get up to 6% cashback. It is a special kind of cashback, though, and you have to make a choice here – I'll show you why in a moment.
Briefly up front: you can get to Revest through my Revest link*. For transparency: this is a referral link. If you sign up through it, I receive a small commission. It does not cost you anything extra – and you support me and my channel. Revest describes the campaign itself in its own blog; there it applies to eligible acquisitions during the campaign period.
The most important thing first is the cashback rates:
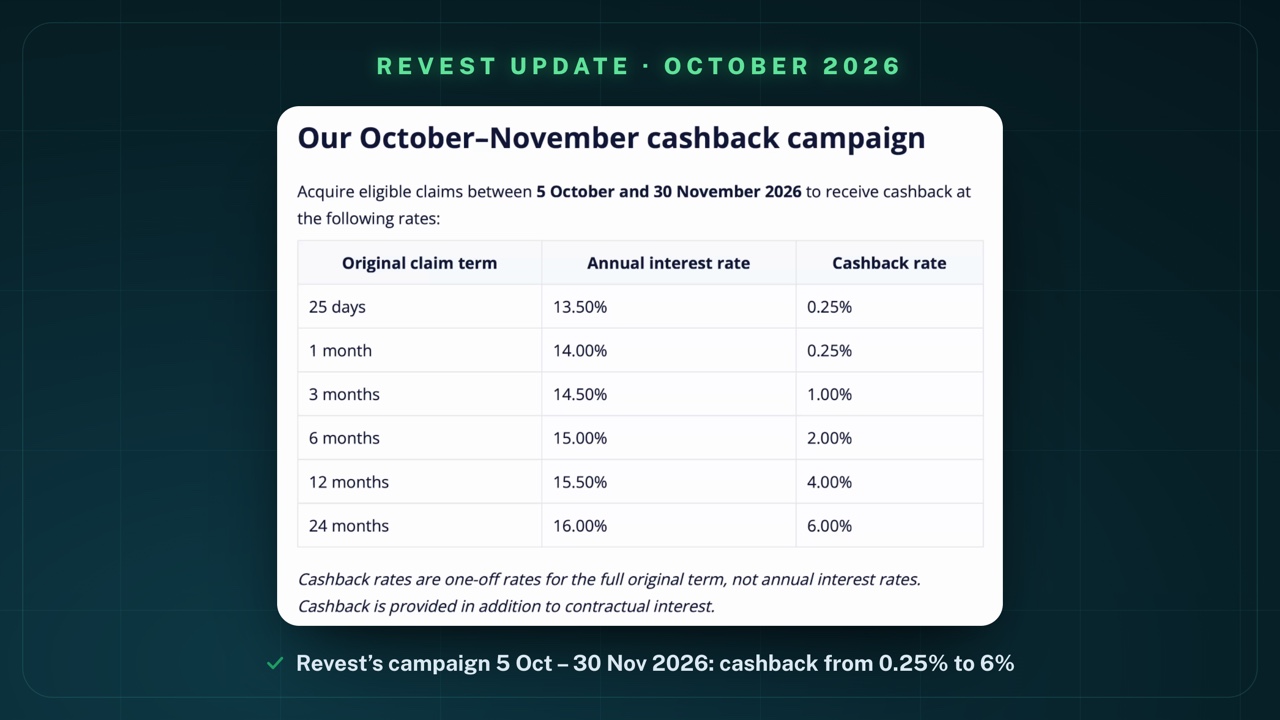
| Term | Interest per year | Cashback |
|---|---|---|
| 25 days | 13.5% | 0.25% |
| 1 month | 14.0% | 0.25% |
| 3 months | 14.5% | 1% |
| 6 months | 15.0% | 2% |
| 12 months | 15.5% | 4% |
| 24 months | 16.0% | 6% |
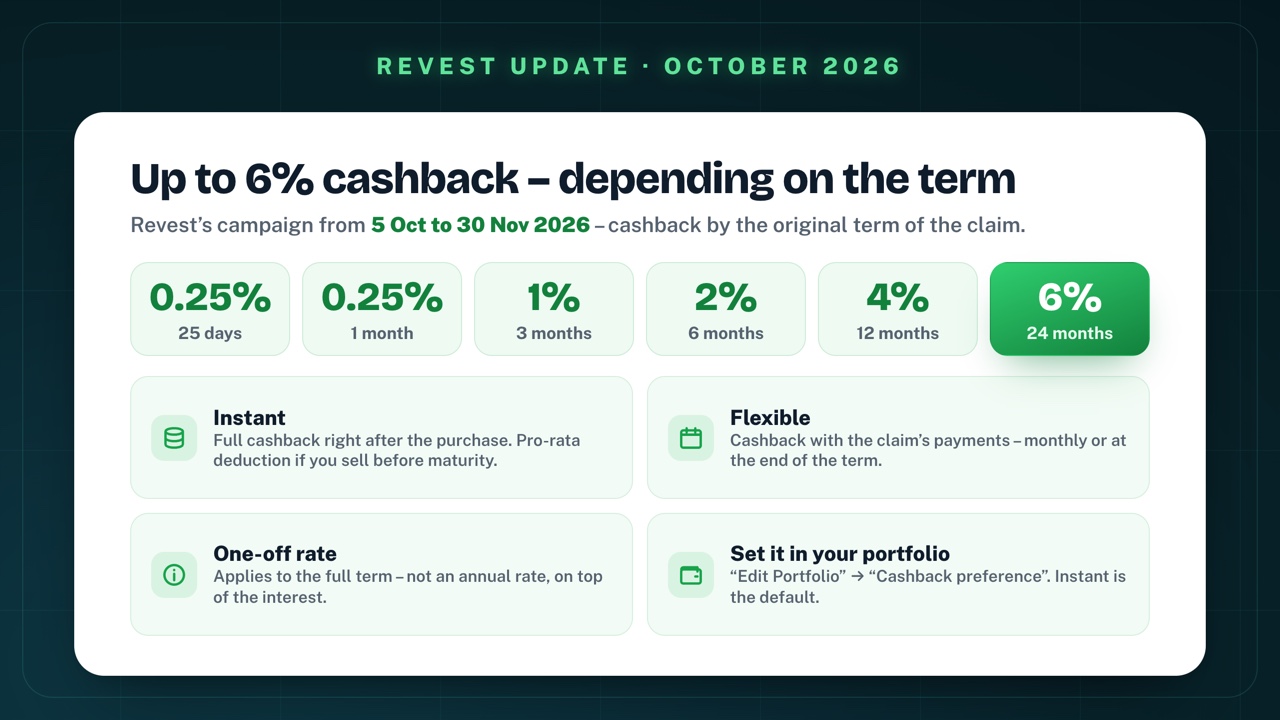
So with 24 months we really do have 6% cashback, which is quite a number. Important for context: this is a one-off rate for the full term, not an annual rate – it comes on top of the interest. Revest's own example: €1,000 over a full 24 months results in €60 of cashback.
Instant or Flexible
So what is special here? You can receive either Instant or Flexible cashback.
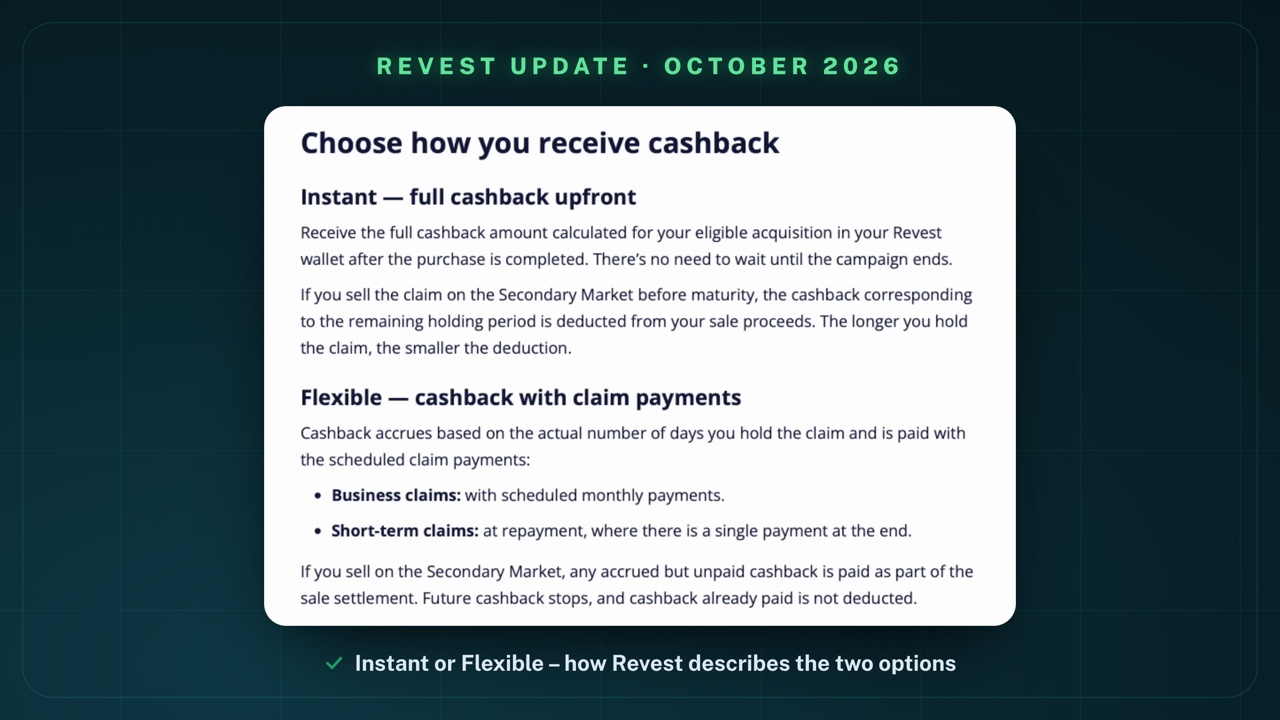
- Instant: as soon as the claim has been acquired, you get the cashback straight away.
- Flexible: the cashback comes with the claim's payments – always with the monthly interest payment for business loans, at the end of the term for the short-term loans.
Then there is the secondary market, which Revest launched last month: if you sell the claims on the market early, the cashback is deducted pro rata from the sale price. That makes sense, of course – otherwise you could simply take the 24-month term, sell straight away, pocket the 6% cashback and be done. Naturally it does not work like that. Strictly speaking, this deduction applies to Instant; with Flexible, according to Revest, nothing is deducted, but future cashback stops.
How to set it
You have to set this up yourself. If you go to "Portfolios" in your account, you see the portfolios through which you invest. Click edit there – and if you scroll down, you see which cashback preference is selected:
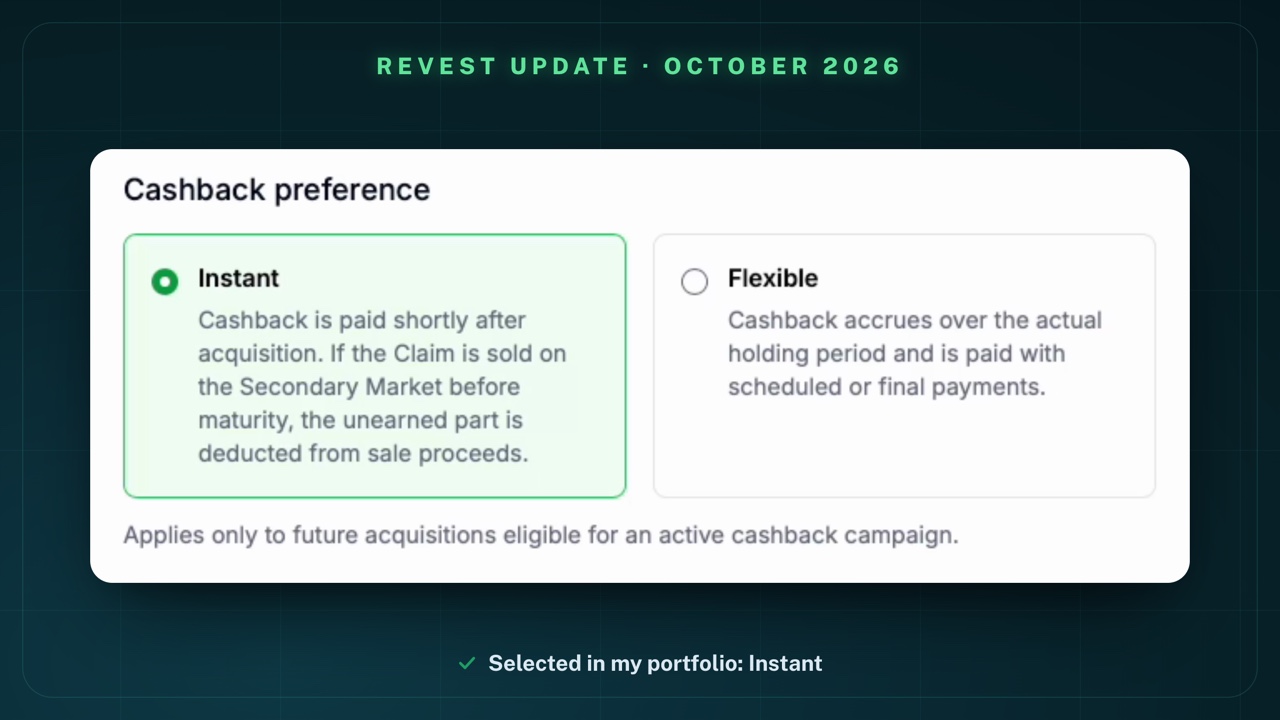
I have Instant, for example. That means: as soon as the claim is acquired, I get the cashback directly. According to Revest, Instant is also the default.
And you can see that in my account under "Accounting": on the day of the recording I had invested another €250, and each time I received this 0.25% cashback on the €25 directly.
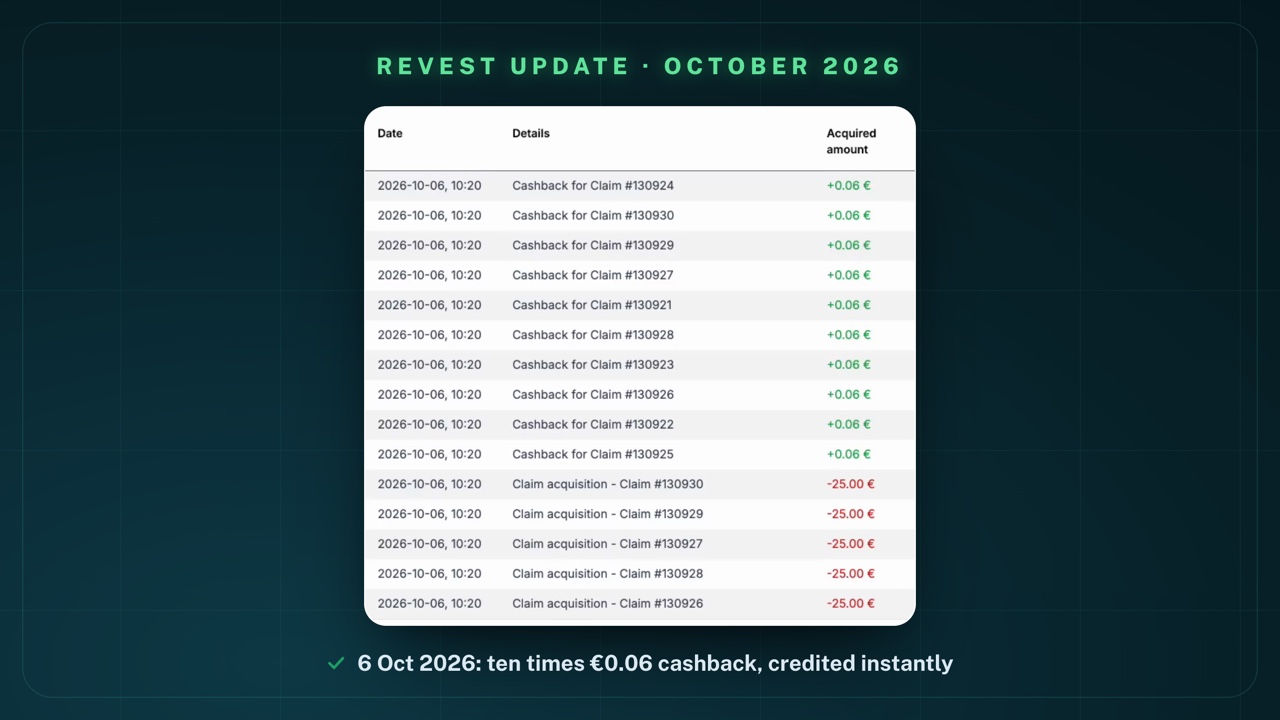
That is €0.06 per claim – so around 60 cents for ten claims. I invest in the short-term loans, so the cashback is small accordingly. Had I chosen Flexible, it would only have been paid at the end of the term for the short-term loans, otherwise monthly and pro rata with the interest.
Video: Revest Update October 2026: €1,559 in My Account, Up to 6% Cashback & My First Two Late Loans
The full update is also available as a video – I walk live through Revest's statistics page, the new cashback campaign, my dashboard, my portfolio settings and my claims. Feel free to watch, or read on below.
My Revest account: €1,559.01
Let's look at my investment in general (as of the recording: 6 October 2026):
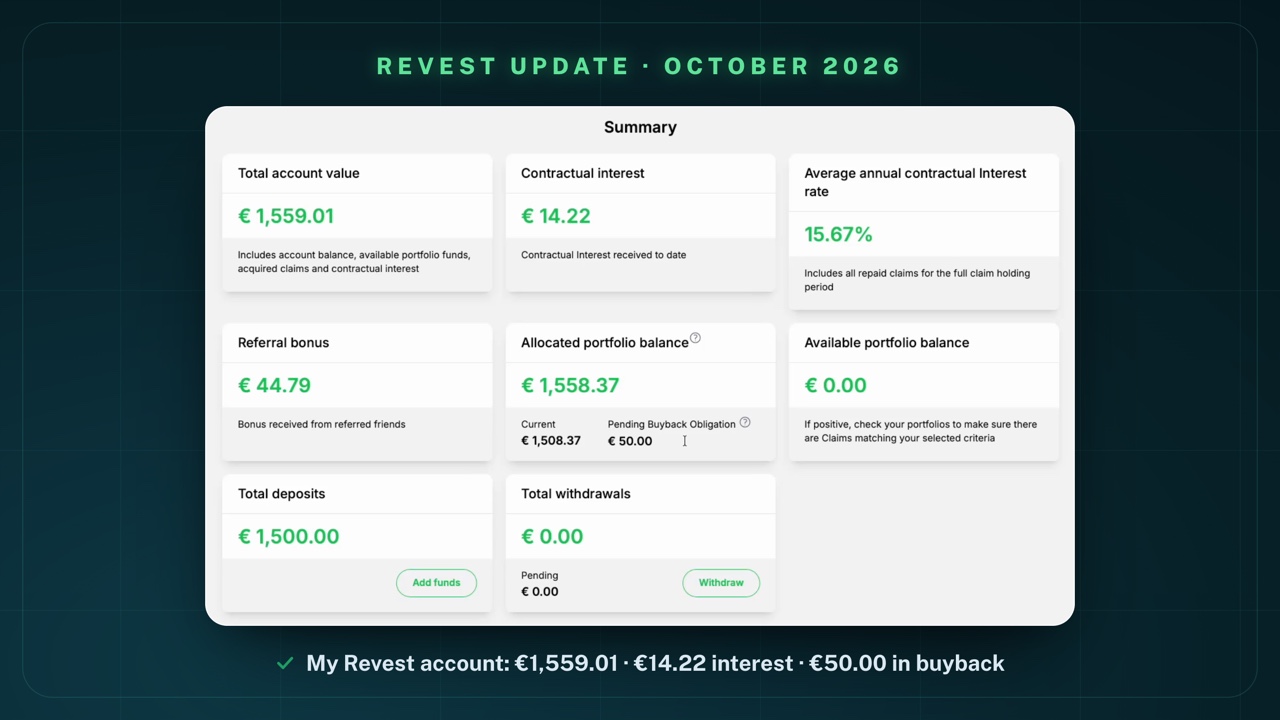
I started a good two months ago and deposited €1,000 the first time, another €250 last month and now another €250.
- Deposited: €1,500.00
- Account value: €1,559.01
- Allocated: €1,558.37 – of which €50.00 is in a pending buyback
- Interest so far: €14.22
- Bonus so far: €44.79 – shown in the dashboard as "Referral bonus"
- Average interest rate: 15.67%
In the video I say that the bonus is included in the 15.67%. Strictly speaking, the field is called "Average annual contractual Interest rate" – so it shows the contractual interest rate, and the dashboard lists the bonus separately. But something is definitely happening already.
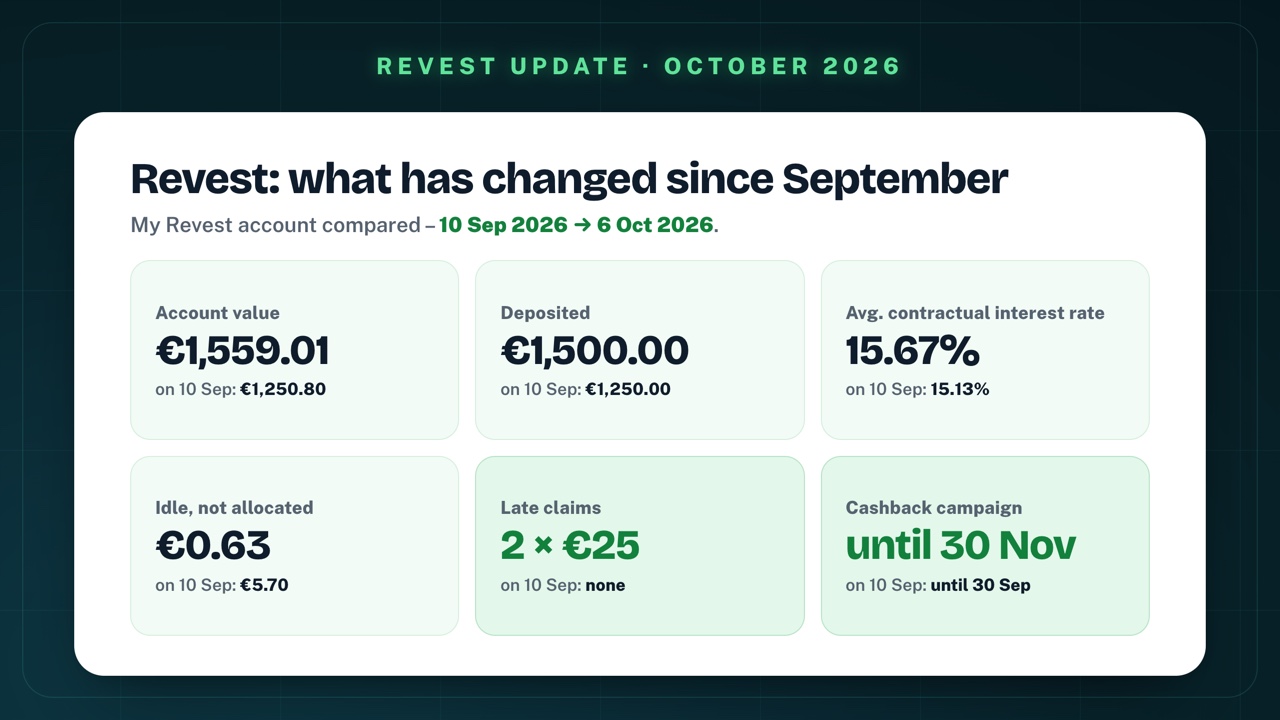
For comparison with my September figures from the Revest review:
My portfolio: short-term loans only
Let's look into my portfolio and what I have actually set. I only use the loans with a 25-day term and those with one month:
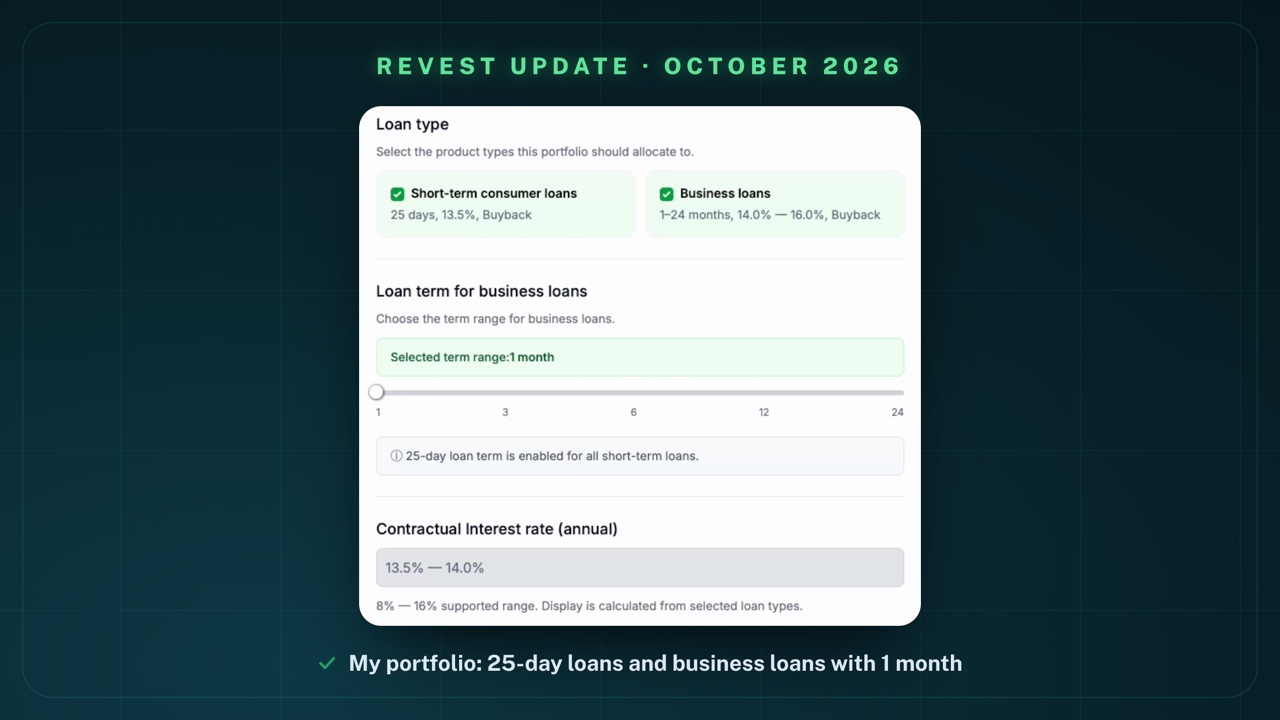
- Short-term consumer loans: 25 days at 13.5% interest, with buyback
- Business loans: of these I have only selected the ones with one month (14.0%)
I simply like this liquidity, that things move quickly. Sure, I could earn considerably more return here if I went for the long-term loans. But especially for testing, I like the fact that they are short-term loans for now. At the beginning I actually had long-term loans too – I sold those on the secondary market. That worked really well; more on that in a moment.
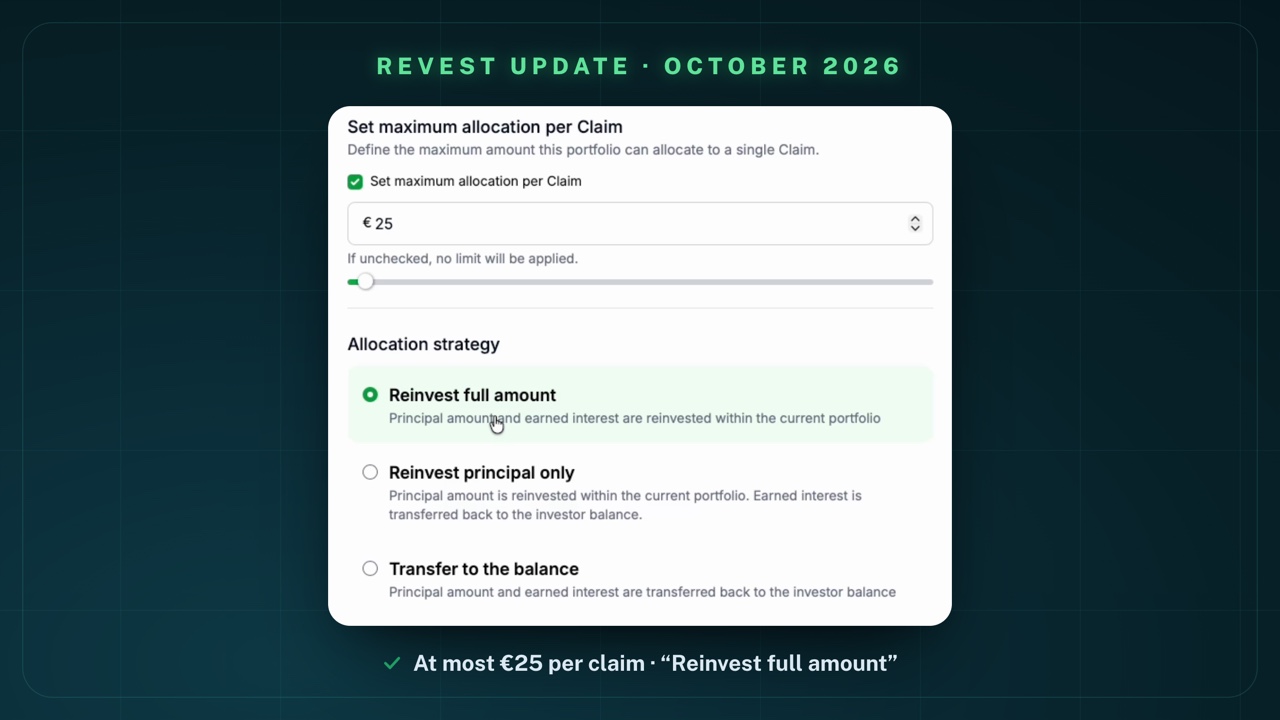
- Maximum per claim: €25 – simply to diversify more broadly
- Strategy: "Reinvest full amount", so that it keeps running automatically
- Lenders: I have ticked all of them – GMoney Group, MoneyPlus and GMoney, all from Kazakhstan
That is my setting for the auto-invest. By the way, on Revest everything always runs through an auto-invest: you have to set up a portfolio like this.
My Claims: what I actually hold
Under "My Claims" I can then see which claims I actually hold. At the very top are the purchases from the day of the recording, which now have 24 days left:
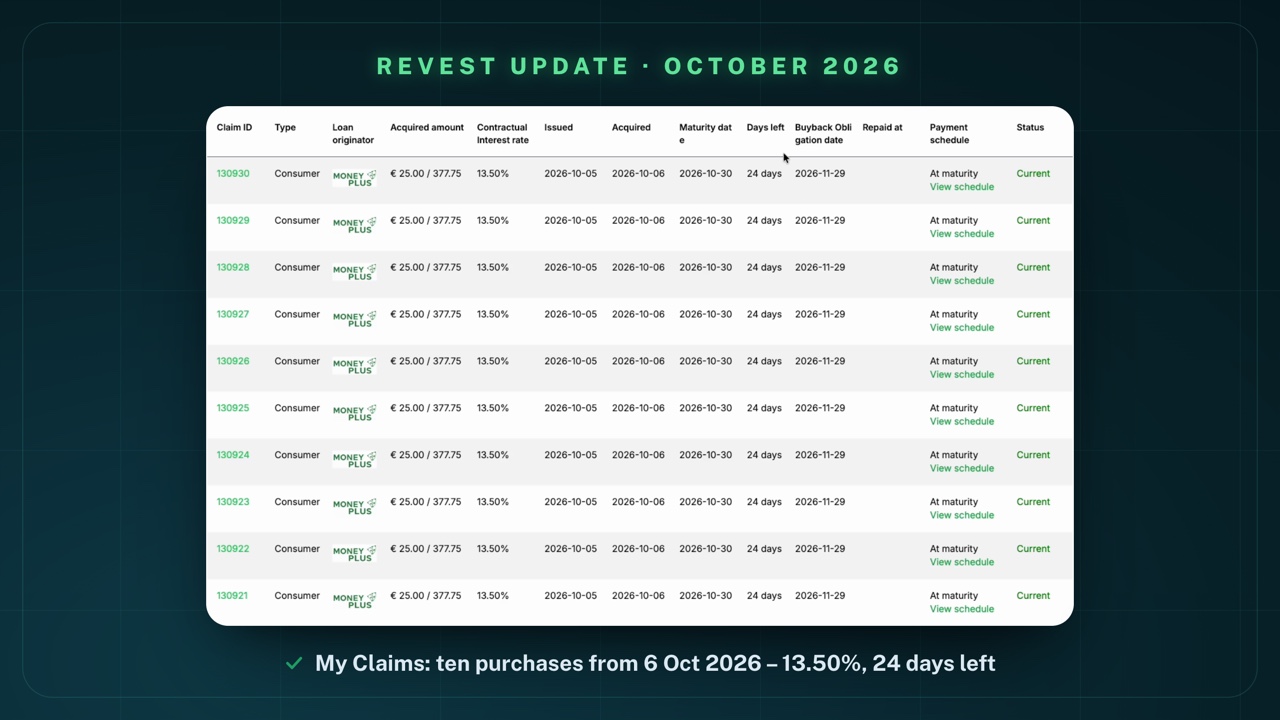
On the next page are the purchases from the days before – acquired on 2 October and on 30 September, with 23 and 24 days left. All fully automatic, of course.
If we go back even further, we also see the claims that I sold on the secondary market:
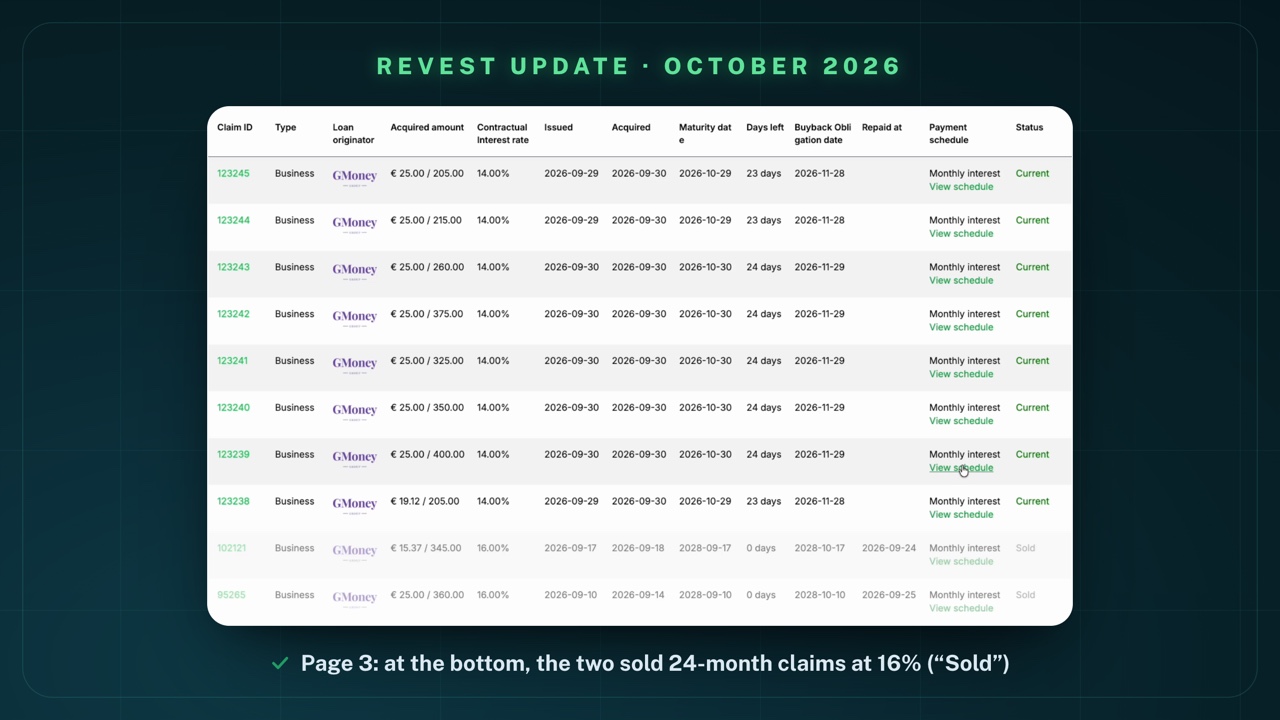
Those were the ones with 16% interest, i.e. with the long terms. I simply sold them, and that worked relatively quickly. And this is how it works: you tick the claims you want to sell and then press "List selected Claims". They are then listed on the secondary market.
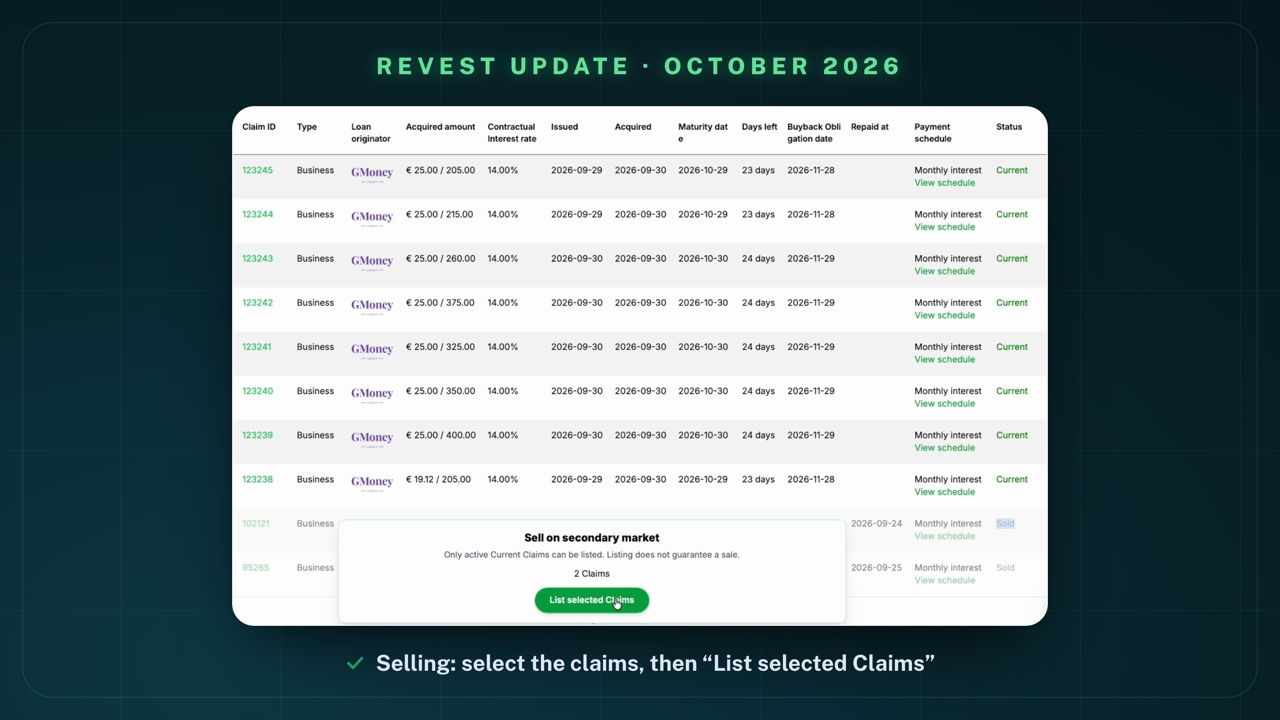
Revest states it right there: only current claims can be listed, and listing does not guarantee a sale.
My first two late loans
What is now getting interesting for me: if we set the status in "My Claims" to "Late", we see that I have two late loans.
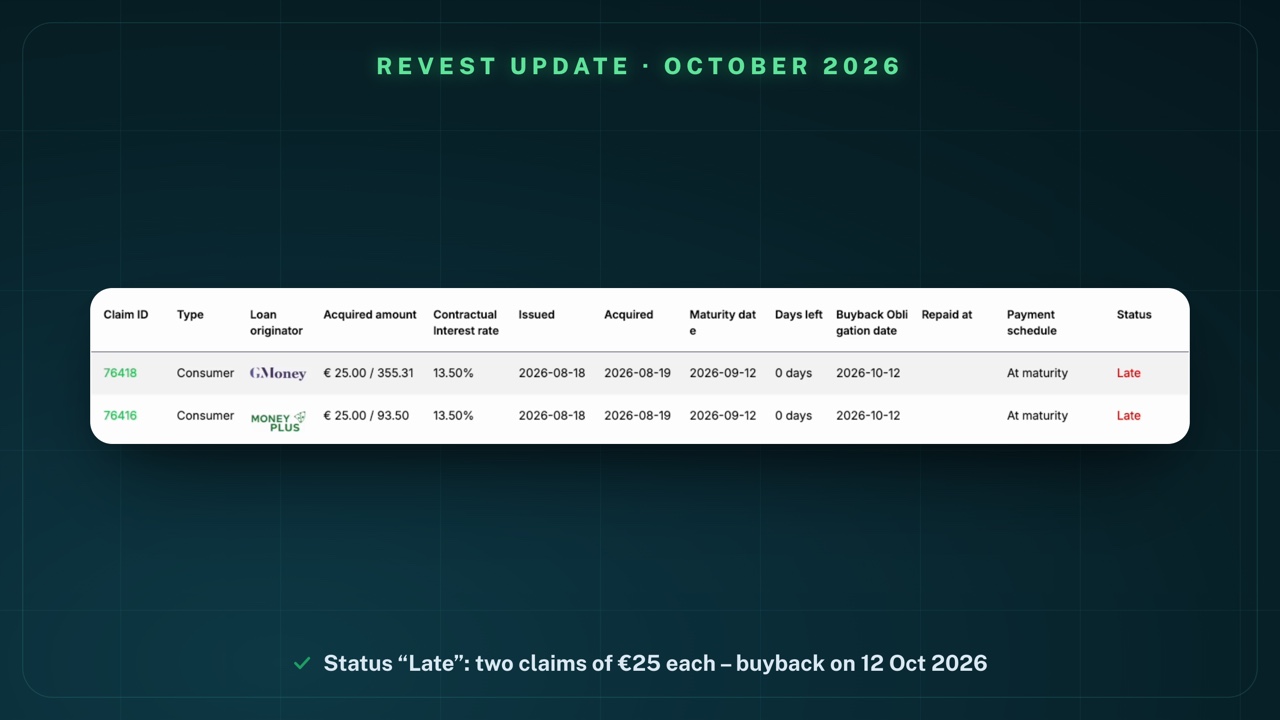
That is simply part of it, of course, especially when you invest this broadly. Both of them have a buyback obligation – the loan originator, i.e. the lender, has to buy them back. We can also see that on my dashboard: it shows €50 where the buyback is currently running.
My account shows 12 October 2026 as the buyback date for both. So they should be repaid in the next few days. I will definitely keep you posted on how it all went and whether it worked cleanly.
How safe is Revest?
The only shortcoming I see so far: Revest is not regulated. I hope something will happen there in the future.
- Not regulated. Revest says so itself in the footer: "FINTECH PLATFORM d.o.o. is not authorised as an investment firm. Revest does not provide investment services." There is no deposit guarantee.
- Operator. FINTECH PLATFORM d.o.o., based in Pula (Croatia).
- Buyback only by the lender. The buyback obligation is owed solely by the lender – so it is only worth as much as the lender itself.
- The secondary market is not an emergency exit. A sale only works if another investor buys.
So you always have to be aware of the risks: loans can default, a platform can fail.
Who is Revest worth it for?
- like short terms from 25 days and quick repayments
- want to work with 13.5 to 16% interest and let an auto-invest portfolio do everything
- value a secondary market for an early exit
- want to pick up the cashback campaign until 30 November 2026
- need a regulated platform with financial supervision
- don't want concentration risk on lenders from a single country (Kazakhstan)
- are looking for a platform with a long track record – Revest has only existed since December 2025
- want to invest money you couldn't afford to lose
My plan and conclusion
So much for the short update. I find the platform really exciting. But because it is not regulated, I will go up to €5,000 at most here.
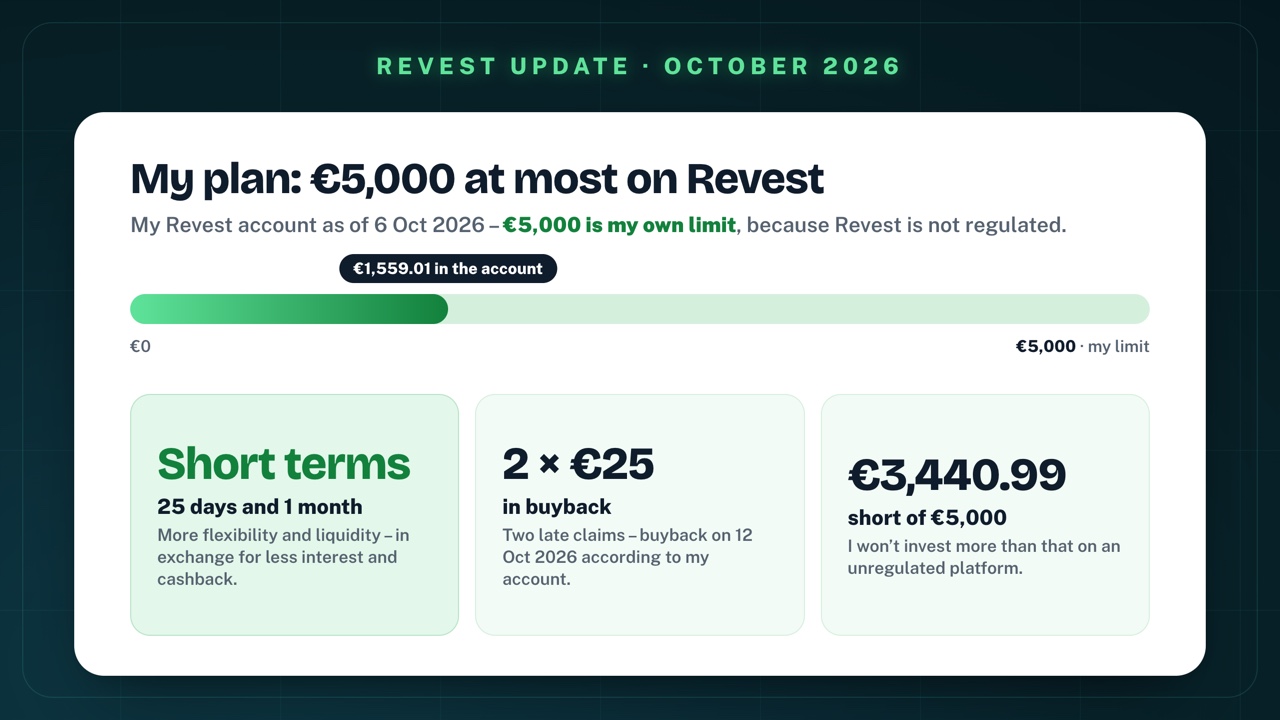
And I will mainly take the short-term loans, so that I simply have a bit more flexibility and liquidity. So far it has worked for me. Sure, I now have these two small loans of €25 each in the buyback obligation, which is of course part of it too. The question now is whether they come back and how it all plays out – I will keep you posted. You can see how Revest fits into my overall P2P portfolio in the P2P Portfolio Update October 2026.
The cashback campaign on Revest is simply very strong at the moment as well. If you want to try Revest: go to Revest through my link*.
Now I'm curious: what is your opinion of Revest, and what experiences have you had so far? I would also like to interview Revest for you – if you have questions for the management, feel free to write them in the comments under the video.
Links marked with * are partner links. If you invest through them, you support my work – at no extra cost to you. Thank you!
Frequently asked questions
How much has Lennard invested in Revest?
As of 6 October 2026 I have deposited €1,500 on Revest: first €1,000, then €250 in September and now another €250. The account value is €1,559.01, of which €1,558.37 is allocated. My upper limit for Revest is €5,000, because the platform is not regulated.
How much interest has Lennard earned on Revest so far?
My dashboard shows €14.22 of contractual interest plus €44.79 in the field "Referral bonus". According to the dashboard, the average annual contractual interest rate is 15.67%. These are figures from my account after around two months, not a guarantee for the future.
What cashback does Revest currently offer?
Revest is running a cashback campaign with up to 6% from 5 October to 30 November 2026. The rate depends on the original term: 0.25% for 25 days and for 1 month, 1% for 3 months, 2% for 6 months, 4% for 12 months and 6% for 24 months. It is a one-off rate for the full term, not an annual rate. So the full 6% is only available for 24-month claims.
What is the difference between Instant and Flexible cashback on Revest?
With Instant you receive the full cashback right after you acquire a claim. If you sell the claim on the secondary market before maturity, the cashback for the remaining term is deducted from your sale proceeds. With Flexible the cashback accrues over the holding period and is paid with the claim's payments – monthly for business loans, at repayment for the 25-day loans. Nothing is deducted on a sale there, but future cashback stops.
Where do you set the cashback preference on Revest?
In your account under "Portfolios": edit the portfolio ("Edit portfolio"), scroll down and choose between Instant and Flexible under "Cashback preference". According to Revest, Instant is the default, including for existing portfolios. The choice only applies to future acquisitions.
Does Lennard have late loans on Revest?
Yes, for the first time: on 6 October 2026 two claims of €25 each were marked "Late" – one from GMoney, one from MoneyPlus, both due on 12 September 2026. In the dashboard the €50 are shown under "Pending Buyback Obligation", and my account shows 12 October 2026 as the buyback date. I will report in the next update whether the buyback goes through cleanly.
Is Revest regulated?
No. Revest says so itself in the footer of its website: "FINTECH PLATFORM d.o.o. is not authorised as an investment firm. Revest does not provide investment services." The operator is FINTECH PLATFORM d.o.o., based in Pula (Croatia). There is no deposit guarantee; the buyback of late claims is owed solely by the lender.
How big is Revest by now?
According to Revest's statistics page, claims with a total value of €13.38m had been acquired by 6 October 2026, and €4.05m was outstanding. €111.7k of contractual interest has been paid to users, the page counted 824 active users and states an average actual return of 14.18%. The platform launched in December 2025.
Disclaimer
⚠️ Not investment advice
All content is for information and entertainment purposes only and does not constitute investment advice, a buy recommendation or an invitation to enter into a financial product. Please do your own research and make decisions based on your personal situation and risk tolerance.
📉 Risk warning & total loss
Investments in securities and other financial instruments generally carry significant risks (e.g. price, market, currency, volatility and credit risks). A total loss of the capital invested cannot be ruled out.
📊 Returns & forecasts
All performance figures, whether historical or as a forecast/estimate, are not a reliable indicator of future results. Capital and returns are not guaranteed.
🔍 Transparency & conflicts of interest
I strictly distinguish between facts and personal estimates. Important: I am often invested in the assets discussed myself, which can create a conflict of interest.
✅ DYOR (Do Your Own Research)
All information has been compiled carefully but is non-binding, without warranty and without any claim to completeness. Please inform yourself thoroughly and consider all opportunities and risks in depth before making an investment decision.
Advertising & affiliate notice
Links marked with * are advertising or affiliate links. If you sign up or buy something through such a link, I may receive a commission – at no extra cost to you. This supports my work.