TWINO Update October 2026: €3,648 in FLEXI, €36 Interest & up to 2% Cashback
My latest TWINO update: €3,648 invested – 100% in FLEXI at a fixed 6% – €36.09 in interest so far and more than €500 added every month. I'll show you my account in detail, why real 12-month securities sit behind FLEXI, what the manual securities pay at 10–12%, how the cashback promotion with up to 2% for new investors works, and the two FLEXI rules you should know.
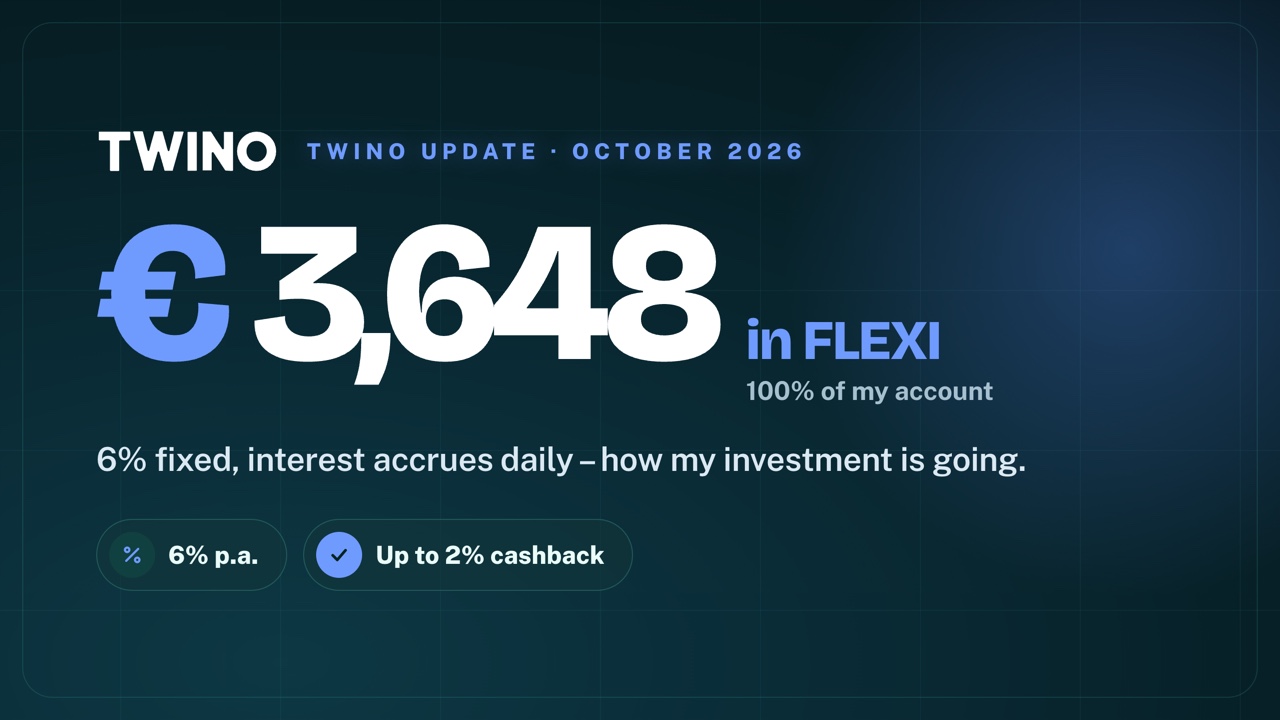
Table of contents
- My TWINO account in numbers
- What is TWINO FLEXI – and what's behind it?
- Video
- FLEXI: two rules you should know
- Investing manually: 10–12% on the primary market
- Liquidity or return?
- Cashback promotion: up to 2% for new investors
- The TWINO app keeps getting better
- CEO interview, Moneza and regulation
- Is TWINO right for you?
- My plan and verdict
- FAQ
Time for a new TWINO update. A few months ago the Latvian platform launched FLEXI, a liquidity product – a fixed 6% return, with your money remaining accessible at any time in principle. My FLEXI holding has kept growing since: I add more than €500 every month and am now at €3,648. In this post I'll show you my account in detail, what is really behind FLEXI, what the manual securities pay and how the current cashback promotion works.
First, as always, the most important note: this is not investment advice and not a buy recommendation, just my personal opinion and my own investment. P2P loans are a risky asset class – defaults, platform risk and a total loss of your capital are all possible. You are responsible for your money, I am responsible for mine – please always make your own decision. The TWINO link is a partner link: if you use it, you support my work at no extra cost to you.
My TWINO account in numbers
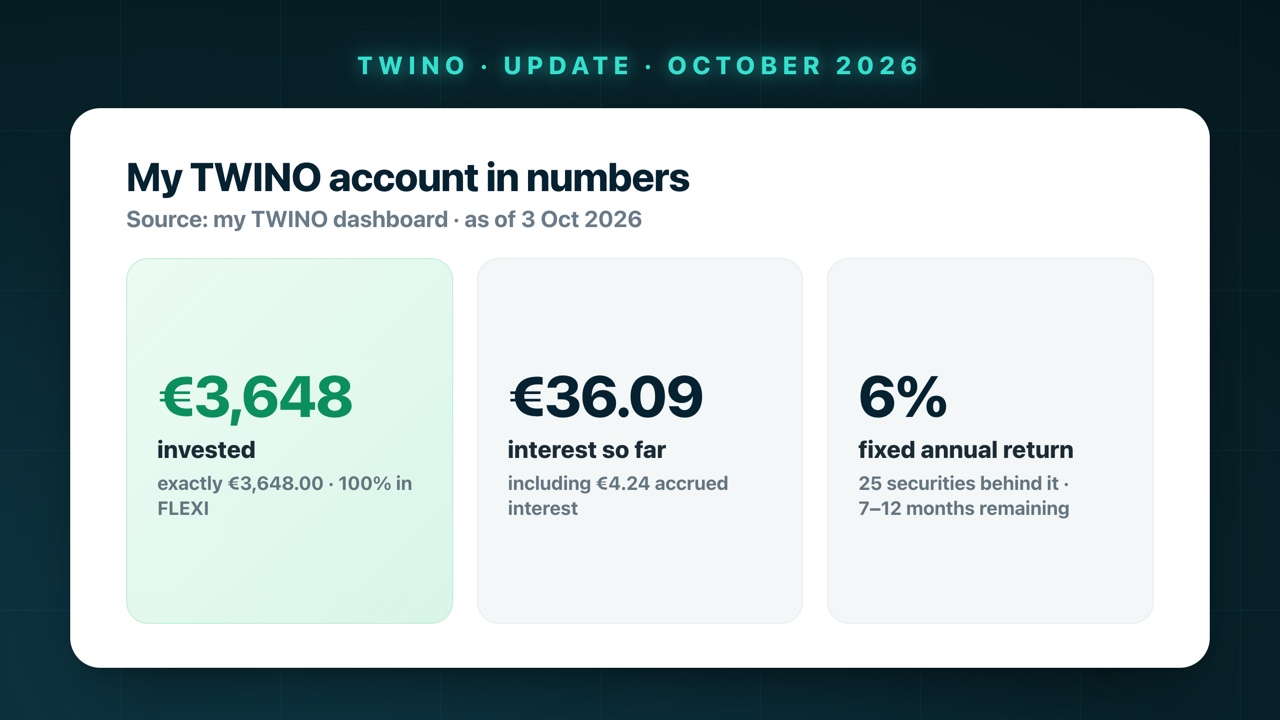
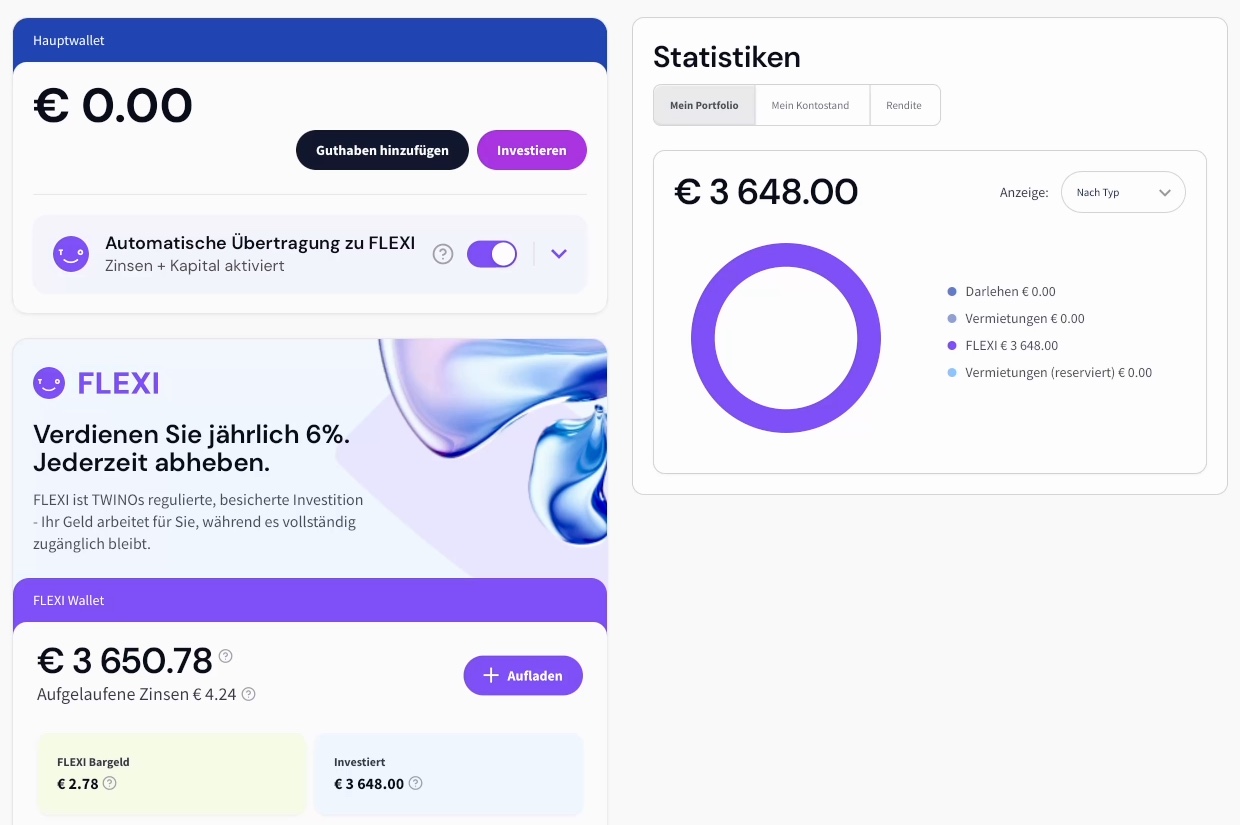
Let's start with the account. As of 3 October 2026 I'm invested with exactly €3,648.00 at TWINO – 100% in FLEXI. I currently hold nothing in regular loans or rentals (€0.00 each), and the main wallet is empty too.
This is what it looks like in the dashboard (my account is set to German):
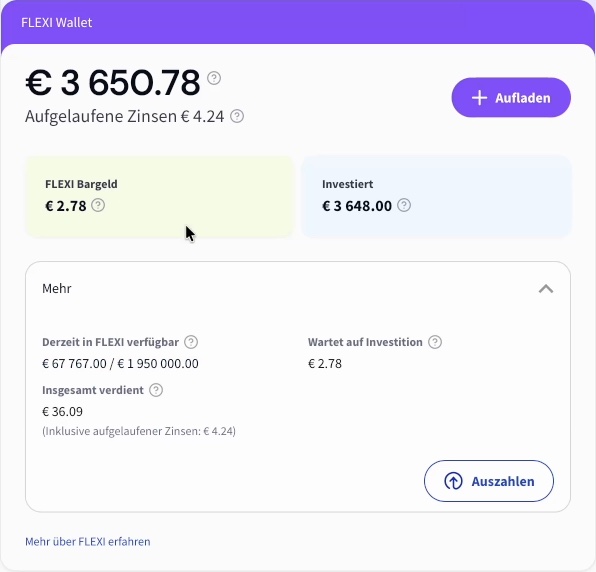
The FLEXI wallet totals €3,650.78: €3,648.00 is invested and €2.78 is currently sitting as "FLEXI cash", waiting for the next investment. In interest I have earned €36.09 so far – that includes €4.24 of accrued interest that hasn't been paid out yet:
For comparison: in the TWINO update from September my account stood at €3,138.24. So a good €500 has been added since – which matches my monthly contribution.
One thing I find practical is the automatic transfer to FLEXI: I have it enabled for interest and principal, so repayments don't sit in the main wallet earning nothing.
What is TWINO FLEXI – and what's behind it?
FLEXI is TWINO's liquidity product: a fixed 6% annual return, with interest accruing daily, and you can in principle pull your money out again at any time. That's exactly why all my TWINO money is there – I like the flexibility.
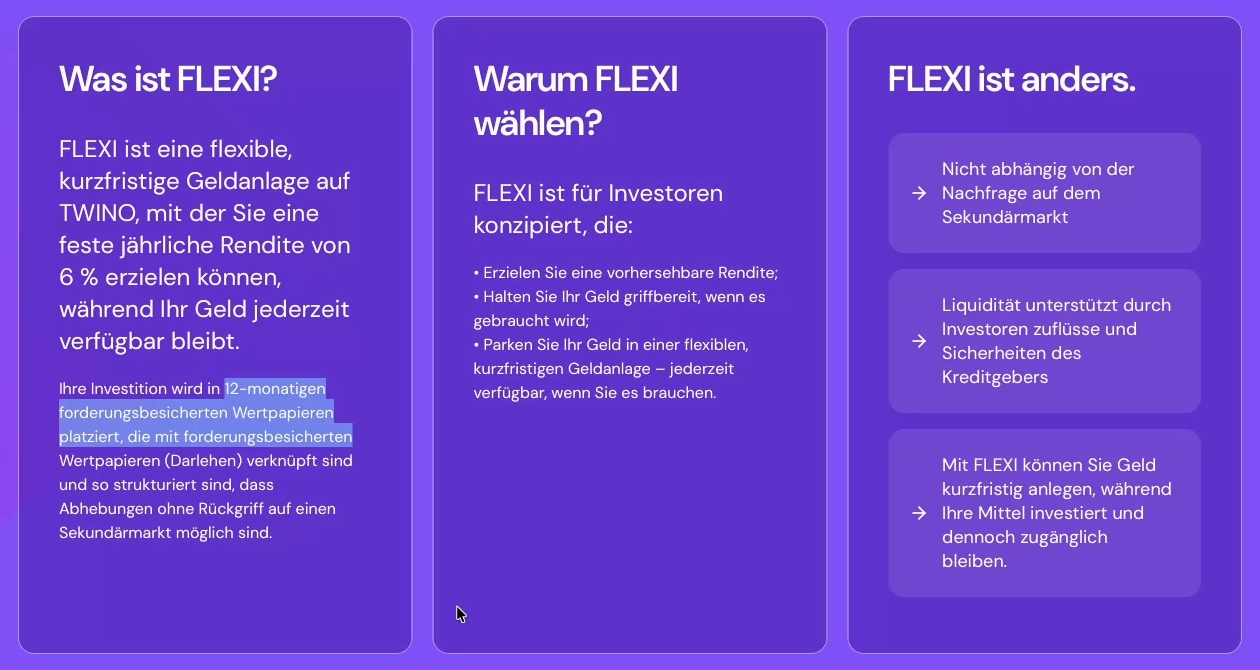
What you need to understand, though: with FLEXI you are not investing in a savings account either. TWINO itself states that the investment is placed in 12-month asset-backed securities linked to consumer loans:
You can see this directly in the account as well. Under "My portfolio" the tab with manual investments is empty for me – while the FLEXI tab lists the securities that actually sit behind it:
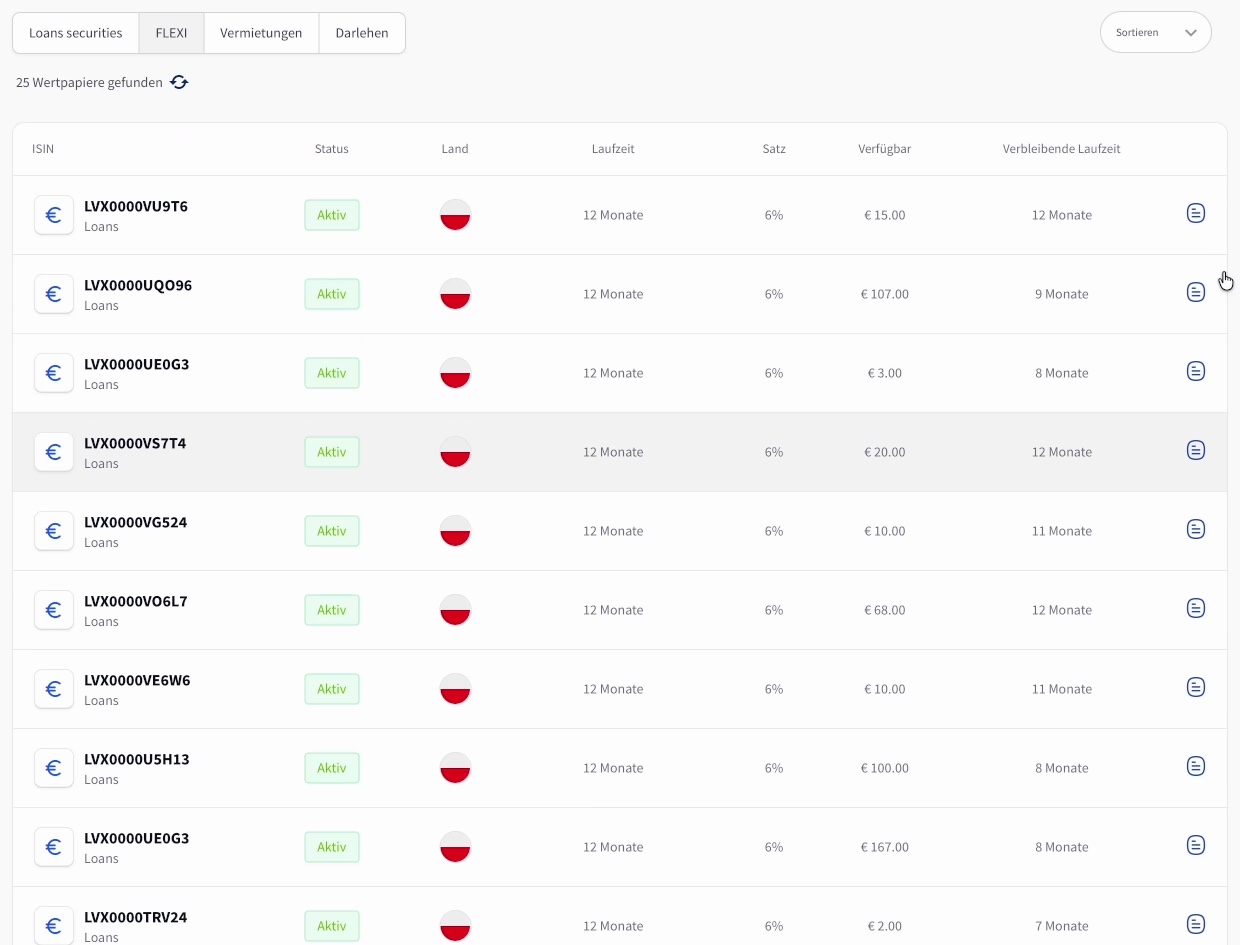
Right now that is 25 securities, all with a 12-month term and 6%, with remaining terms of between 7 and 12 months. My money is spread across them in small amounts – sometimes just a few euros, sometimes more than €100. So there are real loan packages behind it, all from Poland.
Video: TWINO Update October 2026: €3,648 in FLEXI, €36 Interest & up to 2% Cashback
The full update is also available as a video (in German) – I walk through my TWINO dashboard, FLEXI, the manual securities and the cashback promotion. Feel free to watch, or read on below.
FLEXI: two rules you should know
There are two points I don't mention in the video, but they are on TWINO's FLEXI product page – and they belong in an honest assessment:
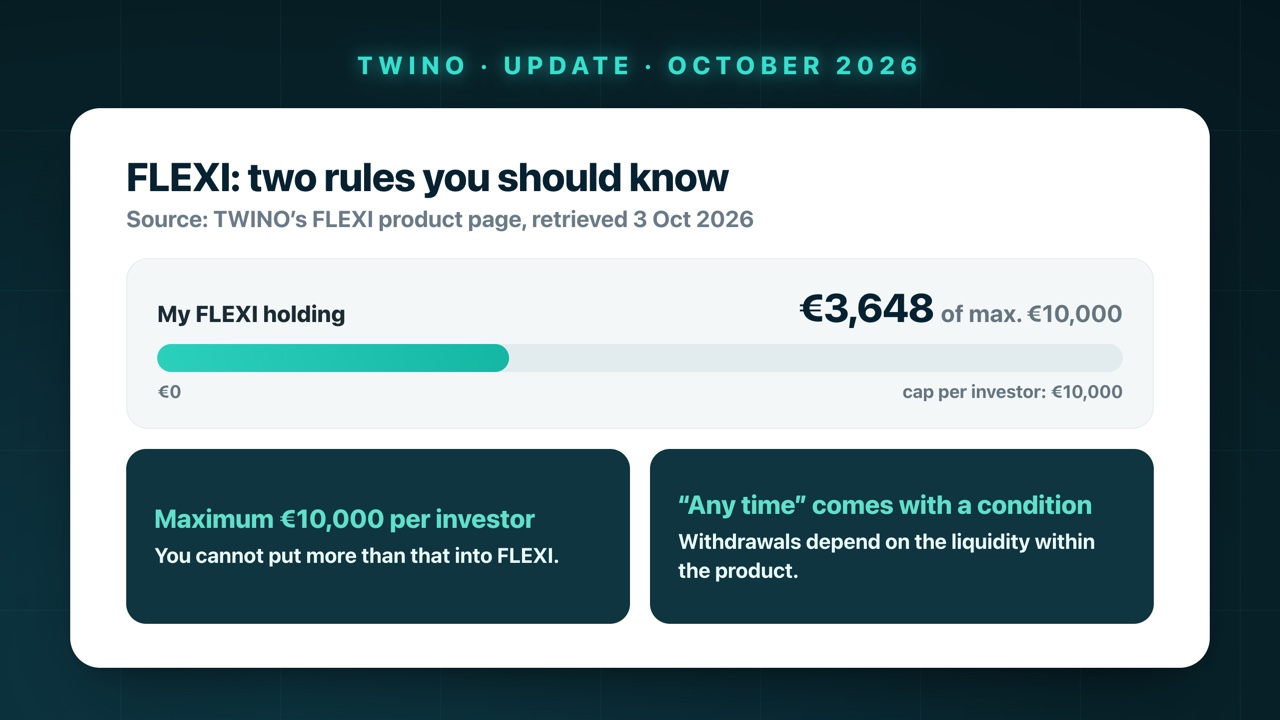
- A maximum of €10,000 per investor. You can't put more than that into FLEXI. At €3,648 I'm at a good third of that limit – in the September update I named the €10,000 as my target for FLEXI.
- "Withdraw any time" comes with a condition. According to TWINO, withdrawals depend on the available liquidity within the product. Normally they are processed quickly; in crisis situations it can take longer. That's why I deliberately say in the video: in and out at any time under normal conditions.
For me FLEXI is a liquidity building block, but it is not a savings account: no deposit insurance, no guarantee, your capital is at risk.
Investing manually: 10–12% on the primary market
Besides FLEXI you can still invest manually at TWINO – and that's where the higher returns are. On 3 October 2026 there were four offers on the primary market:
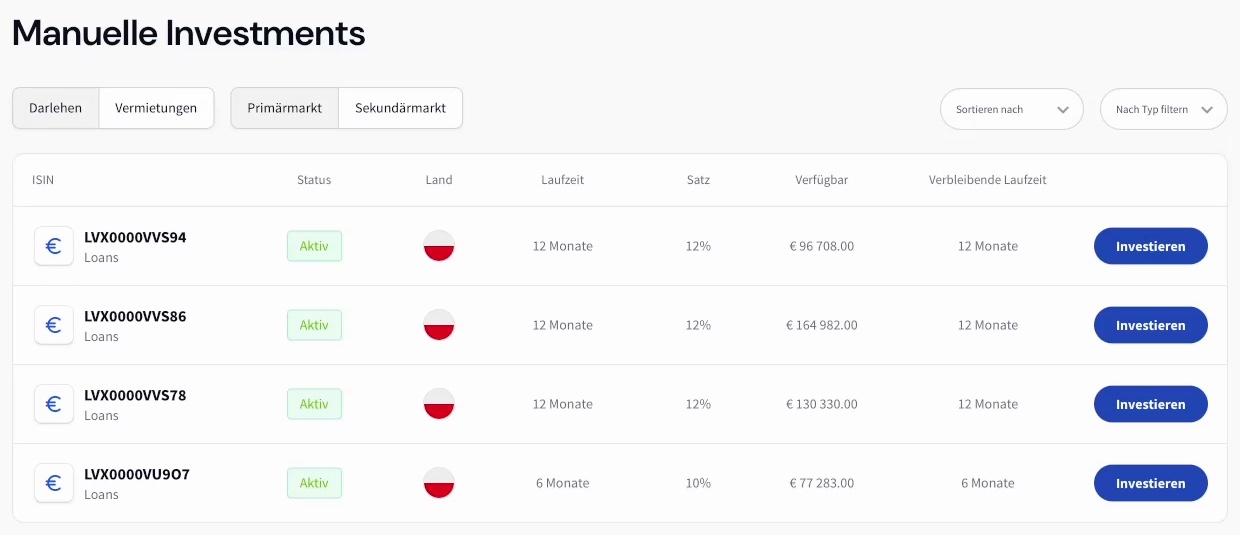
- three with a 12-month term at 12%
- one with a 6-month term at 10%
Securities with a 3-month term weren't on offer that day – in my experience they are rather rare. All four offers came from Poland.
Liquidity or return?
That brings us to the real decision. The same kind of 12-month securities sit behind FLEXI – you just get 6% instead of 12%. The difference is the price of not being locked in until maturity.
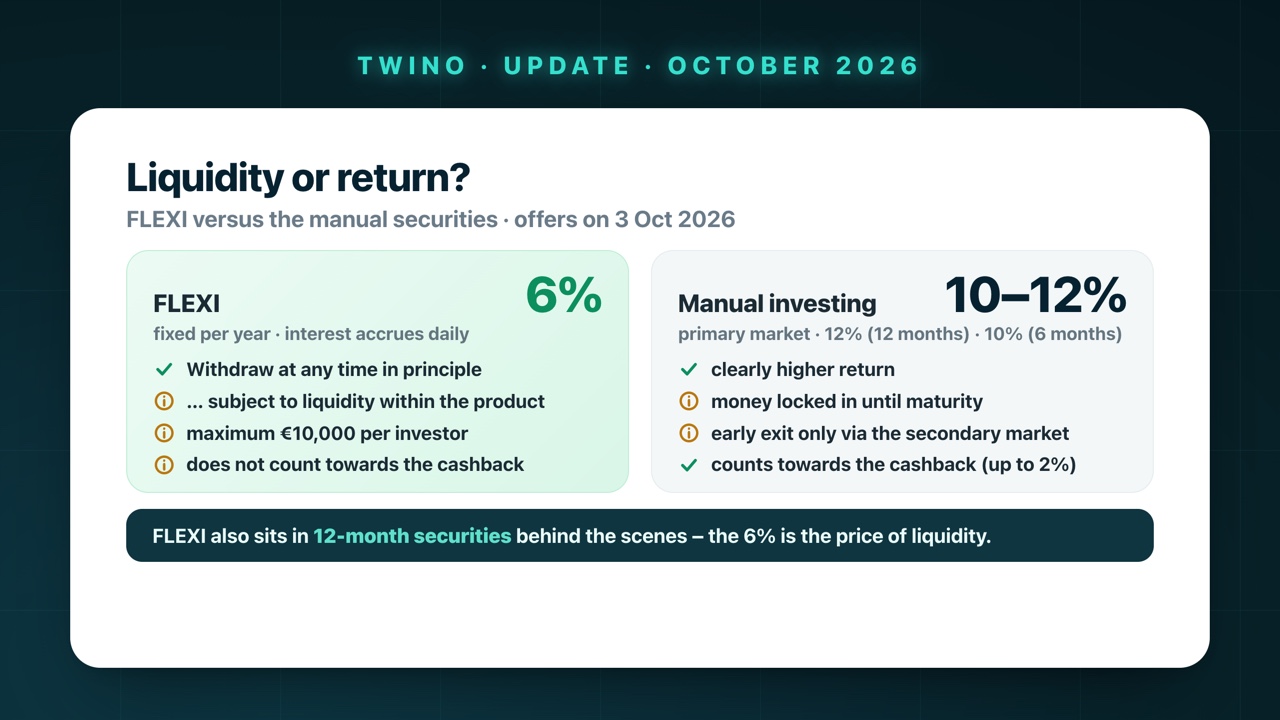
- FLEXI: 6% fixed, interest accrues daily, withdrawable at any time in principle – but a lower return, capped at €10,000 and no cashback.
- Manual on the primary market: 10–12%, but your money is locked in until maturity. The only way out earlier is the secondary market – in other words, only if someone buys the security from you.
Everyone has to answer this for themselves: high return or high liquidity? You don't really get both together anywhere. At TWINO I've deliberately chosen liquidity.
I briefly showed how withdrawing works in the video: click "Withdraw" in the FLEXI wallet and then choose whether the money should go to the main account at TWINO or straight to your bank account. I didn't withdraw anything – I'm leaving the money invested and will keep topping up.
Cashback promotion: up to 2% for new investors
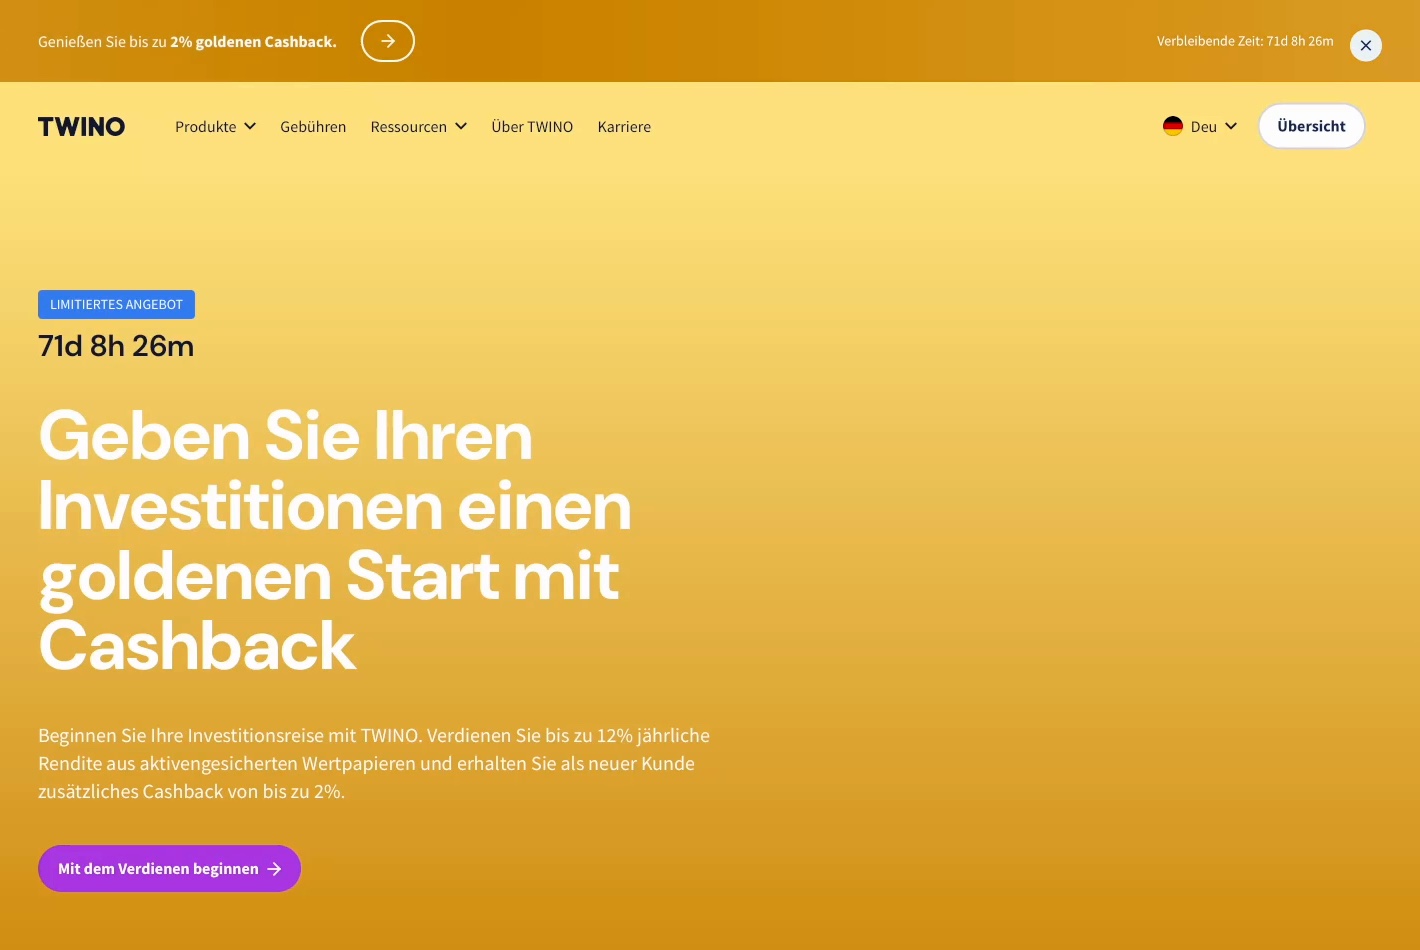
TWINO's cashback campaign for new investors is still running. On 3 October 2026 the countdown on the campaign page showed 71 days remaining – so the promotion runs until roughly mid-December 2026:
This is how it works according to TWINO:
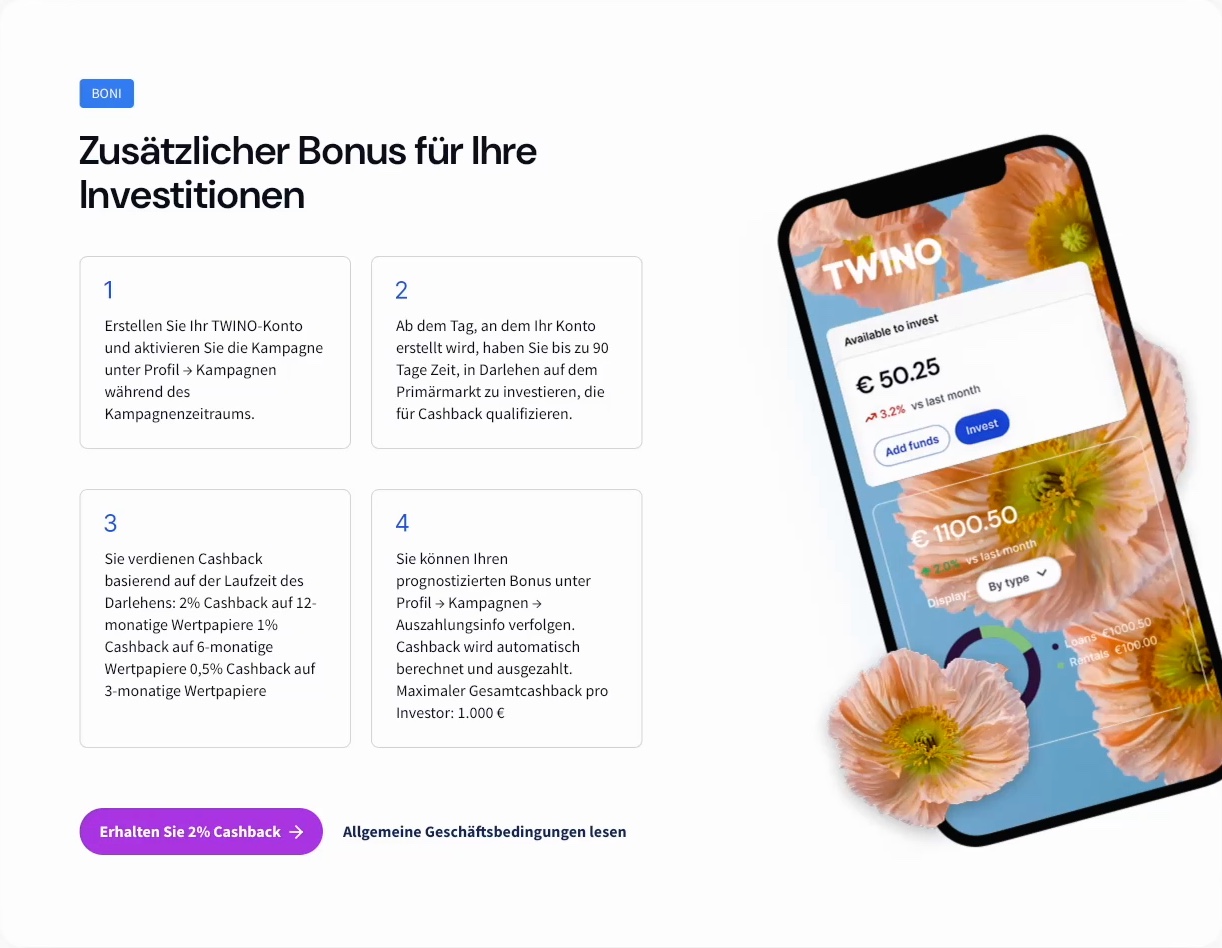
- Create an account via my link and activate: sign up through my link*. You have to switch the campaign on in your account under Profile → Campaigns – it doesn't happen automatically.
- 90 days: from the day your account is created you have up to 90 days to invest on the primary market.
- Tiered rates: 2% on 12-month, 1% on 6-month and 0.5% on 3-month securities.
- Cap: a maximum of €1,000 cashback per investor.
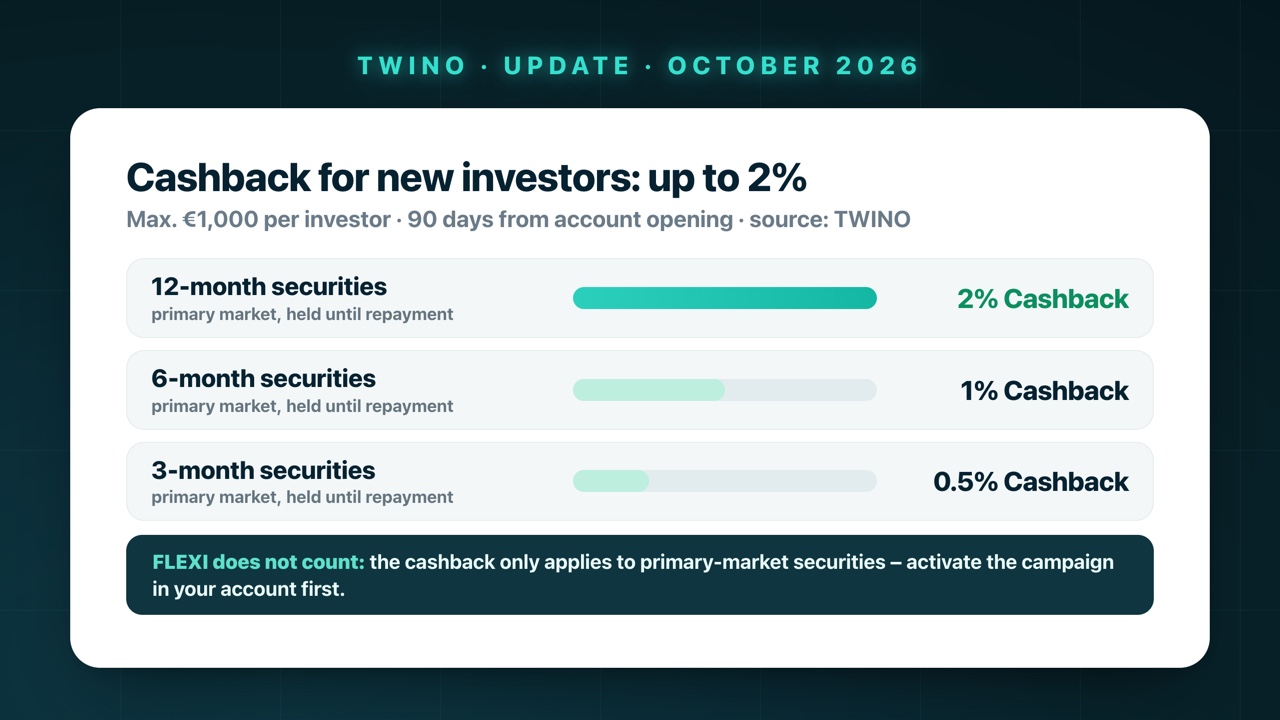
Three restrictions I want to state clearly:
- FLEXI does not count. This isn't on the campaign page but in the terms and conditions (clause 7.4): investments in FLEXI do not qualify for the cashback. So you need the regular securities on the primary market – exactly the ones from the section above.
- Hold until the end. According to the terms, you must still own the securities on the repayment or payout date, and they must not be listed for sale on the secondary market.
- New investors only. The promotion applies to new accounts; if you already had a TWINO account before, you're out.
A note for transparency: the terms PDF linked by TWINO (version 1.3 of 6 July 2026) still states the old campaign period ending 13 September 2026, although the countdown on the page keeps running. So the promotion has been extended without a new PDF being published yet. Please check the current terms directly with TWINO before you invest – under its own terms TWINO can change them at any time.
Important: to get the cashback, you need to sign up to TWINO via my link* and then activate the campaign in your account. For transparency: it's a referral link – if you sign up through it, I receive a small commission, and it doesn't cost you anything extra.
The TWINO app keeps getting better
One thing I really like about TWINO: the app is being developed continuously. When I started it wasn't really usable – by now it's genuinely good and very clear. I deposit through it, the money goes into FLEXI, I could withdraw there and I have the overview the whole time. If, like me, you only use FLEXI, in my experience you can now do everything via the app. I described what the app can do in detail in the September update.
CEO interview, Moneza and regulation
I visited TWINO on site, met the team and interviewed the CEO, Nauris Bloks. You can find the conversation on my channel (in German): Twino-CEO im Interview: 12 % Rendite, Krypto-Lizenz & Flexi erklärt. My impression of TWINO is that they know what they're doing.
On top of that there are a few solid points:
- Russian legacy settled: on 5 August 2026 TWINO announced that the outstanding claims around the former Russian lender Moneza have been recovered – remaining balance zero, principal and interest returned.
- Regulation: AS TWINO Investments is an investment firm supervised by the Bank of Latvia (Latvijas Banka). There is investor compensation of up to €20,000 – but it only applies if TWINO itself fails, not in the case of loan defaults.
- It's working for me: so far all interest has arrived on time and everything has run smoothly.
Still, as always: it works until it doesn't. These remain loan investments without deposit insurance. If something ever goes wrong at TWINO, I'll keep you posted here.
Who is TWINO right for?
- are looking for a flexible liquidity building block at 6% (FLEXI)
- want to take 10–12% on the primary market for fixed terms
- prefer a platform supervised by Latvijas Banka
- are a new investor and want up to 2% cashback on primary-market securities
- need a guaranteed return or deposit insurance
- rely on guaranteed instant access – withdrawals depend on the liquidity within the product
- want to put more than €10,000 into FLEXI or expect cashback on FLEXI alone
- can't bear the capital risk of consumer loans
My plan and verdict
I'm sticking to my course: the money stays invested in FLEXI and I keep topping up – more than €500 every month. You can see how TWINO fits into my overall P2P portfolio in the P2P portfolio update October 2026.
Bottom line: €3,648 invested, €36.09 in interest so far, a fixed 6% with a high degree of flexibility – on a supervised platform. Against that are the points you need to know: 12-month securities sit behind FLEXI, "any time" depends on the liquidity within the product, €10,000 is the limit, and the cashback only applies to the regular securities. If you want to try TWINO: here's my link to TWINO*.
Do you use TWINO FLEXI – or do you rely on other liquidity building blocks? Let me know in the comments, I read and answer everything.
Links marked with * are partner/affiliate links. If you use them, you support my work – at no extra cost to you. Thank you!
Frequently asked questions
How much has Lennard invested at TWINO?
As of 3 October 2026 it is €3,648.00 – entirely in FLEXI. The FLEXI wallet totals €3,650.78, because €2.78 is currently sitting as FLEXI cash waiting for the next investment. I add more than €500 every month.
How much interest has TWINO FLEXI paid so far?
€36.09 in total – including €4.24 of accrued interest that has not been paid out yet. FLEXI pays a fixed 6% annual return with interest accruing daily. Past interest is no guarantee of future returns.
What is behind TWINO FLEXI?
With FLEXI, too, your money is placed in 12-month asset-backed securities linked to consumer loans, according to TWINO. In my account that is currently 25 securities, each with a 12-month term, 6% and remaining terms of between 7 and 12 months. So FLEXI is not a savings account but a loan investment with built-in liquidity.
Can I really get my money out of FLEXI at any time?
In principle, yes – you can withdraw from the FLEXI wallet to the main account or straight to your bank account. But TWINO itself states that withdrawals depend on the available liquidity within the product: normally it is quick, in crisis situations it can take longer. There is no guarantee of instant availability.
What is the maximum I can put into FLEXI?
According to TWINO's FLEXI product page, the maximum investment amount is €10,000 per investor. If you want to invest more at TWINO, the rest has to go into the regular securities on the primary or secondary market.
How does the TWINO cashback promotion with up to 2% work?
The promotion is aimed at new investors: create an account via my link, activate the campaign under Profile → Campaigns and then invest on the primary market within 90 days of opening the account. You get 2% on 12-month, 1% on 6-month and 0.5% on 3-month securities, capped at €1,000 per investor in total. On 3 October 2026 the countdown on the campaign page showed 71 days remaining. Check the current terms directly with TWINO.
Does FLEXI count toward the cashback?
No. The campaign terms (clause 7.4) explicitly state that investments in FLEXI do not qualify for the cashback. You have to invest in securities on the primary market, hold them until repayment and must not offer them for sale on the secondary market.
Is TWINO regulated?
Yes. AS TWINO Investments is an investment firm supervised by the Bank of Latvia (Latvijas Banka). There is investor compensation of up to €20,000 – but it only applies if TWINO itself fails, not in the case of loan defaults. There is no deposit insurance like with a savings account, and your capital is at risk.
Disclaimer
⚠️ Not investment advice
All content is for information and entertainment purposes only and does not constitute investment advice, a buy recommendation or an invitation to enter into a financial product. Please do your own research and make decisions based on your personal situation and risk tolerance.
📉 Risk warning & total loss
Investments in securities and other financial instruments generally carry significant risks (e.g. price, market, currency, volatility and credit risks). A total loss of the capital invested cannot be ruled out.
📊 Returns & forecasts
All performance figures, whether historical or as a forecast/estimate, are not a reliable indicator of future results. Capital and returns are not guaranteed.
🔍 Transparency & conflicts of interest
I strictly distinguish between facts and personal estimates. Important: I am often invested in the assets discussed myself, which can create a conflict of interest.
✅ DYOR (Do Your Own Research)
All information has been compiled carefully but is non-binding, without warranty and without any claim to completeness. Please inform yourself thoroughly and consider all opportunities and risks in depth before making an investment decision.
Advertising & affiliate notice
Links marked with * are advertising or affiliate links. If you sign up or buy something through such a link, I may receive a commission – at no extra cost to you. This supports my work.